Generated by All in One SEO Pro v5.0.1.1, this is an llms-full.txt file, used by LLMs to index the site.
# Independent Investment Advisors
Independent, Fiduciary & Fee-Only Advisor
## Posts
### [Advisor Q&A: How to guide to tax optimized investing. Tax deductions and incentives.](https://independentadvisorsnw.com/advisor-qa-how-to-guide-to-tax-optimized-investing-tax-deductions-and-incentives/)
**Published:** January 17, 2024
**Author:** Investment Advisor
**Excerpt:** There are several tax deductions and incentives available for individuals planning for retirement and educational expenses. These incentives are designed to encourage saving for retirement and education.
**Content:**
**What tax deductions or incentives are available for those planning for retirement and educational expenses?**
There are several tax deductions and incentives available for individuals planning for retirement and educational expenses. These incentives are designed to encourage saving for retirement and education. Here are some key deductions and incentives:
Retirement Planning:
Contributions to Traditional IRAs:
Individuals can deduct contributions made to Traditional Individual Retirement Accounts (IRAs) up to certain limits. These deductions can lower taxable income in the year of contribution.
Contributions to 401(k) and Similar Plans:
Contributions made to employer-sponsored retirement plans, such as 401(k)s, are generally tax-deductible. This reduces taxable income and allows for tax-deferred growth on the contributed amount.
Saver’s Credit:
The Saver’s Credit provides a tax credit for eligible individuals who contribute to retirement accounts. This credit can be claimed in addition to the deduction for retirement plan contributions.
Contributions to Health Savings Accounts (HSAs):
Contributions to HSAs are tax-deductible, and the earnings within the HSA grow tax-free. Withdrawals for qualified medical expenses are also tax-free.
Roth IRA Contributions (Non-Deductible, but Tax-Free Withdrawals):
While contributions to Roth IRAs are not tax-deductible, qualified withdrawals (including earnings) are tax-free, providing tax advantages in retirement.
Catch-Up Contributions:
Individuals aged 50 and older can make additional “catch-up” contributions to retirement accounts, such as an extra contribution to IRAs or 401(k)s. These additional contributions can enhance retirement savings.
Educational Expenses:
American Opportunity Credit:
The American Opportunity Credit provides a tax credit for qualified education expenses incurred during the first four years of higher education. This credit can be up to $2,500 per eligible student.
Lifetime Learning Credit:
The Lifetime Learning Credit offers a tax credit for qualified education expenses for eligible students pursuing higher education. The credit can be up to $2,000 per tax return.
Tuition and Fees Deduction:
Taxpayers may be able to deduct qualified education expenses for themselves, their spouse, or their dependents. This deduction can be up to $4,000 and is taken as an adjustment to income.
529 College Savings Plans:
Contributions to 529 plans are not federally tax-deductible, but some states offer tax incentives. Earnings within the 529 plan grow tax-free, and withdrawals for qualified education expenses are also tax-free.
Student Loan Interest Deduction:
Taxpayers may be able to deduct up to $2,500 of interest paid on qualified student loans. This deduction is taken as an adjustment to income.
Educator Expenses Deduction:
Educators may be eligible to deduct up to $250 for unreimbursed expenses incurred for books, supplies, computer equipment, and other classroom-related expenses.
It’s important to note that tax laws are subject to change, and eligibility for these deductions and incentives depends on individual circumstances. Consulting with a tax professional or [financial advisor](https://independentadvisorsnw.com/homepage/education/how-to-choose-a-financial-advisor/) is recommended to ensure accurate and up-to-date information tailored to your specific situation.

Investment Advisor
[See Full Bio](https://independentadvisorsnw.com/author/investment-advisor/) [ ](https://independentadvisorsnw.com/author/investment-advisor/)
**Categories:** All Posts, Financial Planning, Investment Advisor
---
### [The One Big, Beautiful Bill Act: What It Means for Your Financial and Tax Planning](https://independentadvisorsnw.com/the-one-big-beautiful-bill-act-what-it-means-for-your-financial-and-tax-planning/)
**Published:** April 21, 2026
**Author:** Financial Planner
**Content:**
## The One Big, Beautiful Bill Act: What It Means for Your Financial and Tax Planning
Major tax legislation always creates headlines, but the real impact shows up quietly—in tax returns, investment decisions, retirement planning, and estate strategies over the next several years.
The **One Big, Beautiful Bill Act (OBBBA)** introduces a mix of permanent and temporary tax changes that will influence planning decisions for high-income professionals, retirees, and business owners. Some provisions create new opportunities. Others simply change the rules of the road.
What matters most is not memorizing every detail—it’s understanding where these changes intersect with your financial plan. Below is a practical breakdown of the provisions most likely to affect the types of households we typically work with.
---
## Income Taxes, Deductions, and Credits: What Actually Moves the Needle
Several core elements of the prior tax framework are now permanent, which removes a major source of uncertainty that had been hanging over long-term planning.
**Lower tax brackets and the higher standard deduction are now permanent.**
For many households, this simply means more predictability. From a planning standpoint, it allows us to make longer-term projections for retirement income, Roth conversion strategies, and tax-efficient withdrawal plans without worrying about an automatic tax increase in a few years.
**The SALT deduction cap increases to $40,000—but with income-based phaseouts.**
This will matter most to higher-income households in states with significant state income or property taxes. The benefit will not be uniform. At higher income levels, the deduction begins to phase out, so the planning conversation shifts from “How much is the deduction?” to “Is there a more efficient structure for income, deductions, or residency?”
**A new deduction for car loan interest—up to $10,000—has been introduced.**
This applies only to vehicles assembled in the United States and is temporary. For most high-income households, the benefit will be modest, but it is another example of how tax policy is increasingly tied to specific behaviors.
**Changes to the Child Tax Credit and other income-based credits continue to evolve.**
For families with dependents, eligibility and benefit amounts may shift based on income levels and filing status. These changes are worth reviewing annually, especially during years with large bonuses, equity compensation, or business income fluctuations.
---
## Retirement and Investment Planning: Where Strategy Still Matters Most
Some of the most meaningful changes affect retirees and investors—particularly those managing distributions, capital gains, and long-term income planning.
**A temporary “Senior Bonus” deduction of up to $6,000 is available for eligible retirees.**
For households nearing retirement, this may provide incremental tax relief, but it is unlikely to change the broader retirement strategy. The larger planning focus remains managing taxable income, coordinating Social Security timing, and controlling required distributions over time.
**Capital gains brackets will continue to adjust for inflation.**
This is helpful, particularly for investors managing concentrated stock positions or executing multi-year diversification strategies. It creates more flexibility to harvest gains gradually rather than triggering large one-time tax events.
**Relief from the Alternative Minimum Tax (AMT) becomes permanent.**
AMT exposure has already declined significantly over the past decade. This change reinforces that trend, although high-income households—especially those exercising stock options or recognizing large capital gains—can still encounter AMT in specific years.
---
## Estate Planning: The Window for Larger Transfers Is Now Permanent
One of the most consequential changes in the legislation is the permanent increase in transfer tax exemptions.
**Estate, gift, and generation-skipping transfer tax exemptions rise to approximately $15 million per individual.**
For many families, this effectively removes federal estate tax as a near-term concern. However, that does not eliminate the need for estate planning. Instead, the focus shifts toward:
- Efficient wealth transfer strategies
- Trust design and beneficiary planning
- State estate tax exposure
- Long-term asset protection
- Income tax efficiency for heirs
For households with significant assets, this change creates flexibility—but it does not replace thoughtful planning.
---
## Other Changes Worth Watching
A few additional provisions may affect specific households, depending on their situation.
**Medicaid eligibility rules are tightening.**
Funding reductions and new participation requirements may affect long-term care planning for some families, particularly those supporting aging parents or relatives.
**New tax-advantaged investment accounts for children have been introduced.**
These accounts allow structured contributions and tax-deferred or tax-free growth. For families already using 529 plans, custodial accounts, or trusts, this simply adds another planning tool—not a replacement.
**Clean energy and electric vehicle tax credits are scheduled to phase out.**
If a major purchase or home upgrade is already under consideration, timing may matter. Waiting too long could mean losing access to existing incentives.
---
## What This Means in Practice
Most tax law changes do not require immediate action—but they do require periodic review.
In our experience, the households most affected by legislation like this tend to have:
- High or variable income
- Significant investment assets
- Equity compensation or concentrated positions
- Business ownership
- Retirement transitions within the next 5–10 years
- Estate planning considerations
For these families, the opportunity is rarely about a single deduction. It is about coordinating decisions across taxes, investments, and long-term planning.
---
## The Bottom Line
The OBBBA introduces meaningful changes, but it does not fundamentally alter the principles of good planning.
Consistent monitoring, tax awareness, and disciplined decision-making remain the drivers of long-term success. The real risk is not missing a specific tax provision—it is failing to revisit your strategy as the rules evolve.
If you have not reviewed your tax and financial plan recently, this is a good time to do so—especially if your income, investments, or retirement timeline has changed.
***Disclosure:** This material is for informational purposes only and should not be construed as investment, tax, or legal advice. Individual results will vary, and planning decisions should be made in consultation with qualified professionals. Advisory services are offered by Independent Investment Advisors pursuant to a written agreement.*

Financial Planner
[See Full Bio](https://independentadvisorsnw.com/author/financial-planner/) [ ](https://independentadvisorsnw.com/author/financial-planner/)
**Categories:** All Posts, Financial Planning
---
### [Last-Minute Tax Strategies: IRA and HSA Contributions Before the Filing Deadline](https://independentadvisorsnw.com/last-minute-tax-strategies-ira-and-hsa-contributions-before-the-filing-deadline/)
**Published:** March 13, 2026
**Author:** Financial Planner
**Excerpt:** Every year as tax season approaches, most people focus on gathering documents and preparing their returns. But the weeks leading up to the federal tax filing deadline can also present one last opportunity to reduce your prior year’s tax liability.
**Content:**
Every year as tax season approaches, most people focus on gathering documents and preparing their returns. But the weeks leading up to the federal tax filing deadline can also present **one last opportunity to reduce your prior year’s tax liability**.
Two of the most commonly overlooked strategies involve **Individual Retirement Accounts (IRAs)** and **Health Savings Accounts (HSAs)**. Both accounts provide powerful tax advantages, and in many cases contributions can still be made **after the calendar year ends but before the tax filing deadline**.
For the **2025 tax year**, most taxpayers have until **April 15, 2026** to complete eligible contributions.
At our firm, **Independent Investment Advisors**, these contribution decisions are typically part of a broader [tax planning](https://independentadvisorsnw.com/advisor-qa-how-do-you-help-your-clients-adjust-their-retirement-and-investment-strategies-in-response-to-evolving-tax-laws/) discussion. The goal isn’t just contributing to accounts—it’s making sure those contributions align with long-term investment strategy, retirement planning, and overall tax efficiency.
Understanding the rules surrounding IRAs and HSAs can help ensure you don’t miss these valuable opportunities.
# Why the Tax Filing Deadline Still Matters for Retirement Contributions
Unlike most employer-sponsored retirement plans, which must be funded during the calendar year, **IRAs allow contributions for the prior year up until the federal filing deadline**.
This creates an important planning window.
Once income and deductions become clearer during tax preparation, investors may still have time to:
• Reduce taxable income
• Increase retirement savings
• Adjust tax strategies for the previous year
• Improve long-term tax diversification
For example, someone who unexpectedly receives a year-end bonus or realizes their tax bill is higher than anticipated may be able to **offset part of that income with an IRA contribution**.
Because these contributions can be made after the year ends, they offer flexibility that many other retirement accounts do not.
---
# 2025 IRA Contribution Limits
For the **2025 tax year**, the IRS allows the following IRA contributions:
- **$7,000** for individuals under age 50
- **$8,000** for individuals age 50 or older (includes catch-up contribution)
These limits apply **across all IRA accounts combined**, including:
- Traditional IRAs
- Roth IRAs
- Multiple IRA accounts held at different custodians
For example, if someone contributes $4,000 to a Roth IRA and $3,000 to a Traditional IRA, they have reached the total $7,000 limit.
Another important rule is that **your IRA contribution cannot exceed your earned income for the year**. Earned income generally includes wages, salaries, bonuses, and self-employment income.
However, married couples may still contribute using what’s known as a **spousal IRA strategy**. This allows a working spouse’s income to support IRA contributions for both spouses, even if one partner has little or no earned income.
---
# Understanding Traditional IRA Tax Deductions
A common misunderstanding is that higher earners cannot contribute to a Traditional IRA. In reality, **income does not prevent the contribution itself**. Instead, income determines whether that contribution is **tax-deductible**.
The deductibility rules depend largely on whether you or your spouse participates in an employer-sponsored retirement plan, such as a 401(k).
For the **2025 tax year**, the deduction begins to phase out at certain income levels.
### Single Filers Covered by a Workplace Retirement Plan
- Full deduction if Modified Adjusted Gross Income (MAGI) is **$79,000 or less**
- Partial deduction between **$79,000 and $89,000**
- No deduction above **$89,000**
### Married Filing Jointly (Both Covered by Workplace Plans)
- Full deduction if MAGI is **$126,000 or less**
- Partial deduction between **$126,000 and $146,000**
- No deduction above **$146,000**
Even if the deduction is unavailable, contributing to a Traditional IRA may still provide value because investments grow **tax-deferred until withdrawal**.
For some investors, nondeductible IRA contributions may also play a role in more advanced strategies such as Roth conversion planning.
---
# Roth IRA Contributions and Income Limits
While Traditional IRAs focus on upfront deductions, **Roth IRAs provide tax-free growth and tax-free withdrawals in retirement** if certain conditions are met.
However, Roth IRAs have strict **income eligibility limits**.
As income increases, the amount you are allowed to contribute gradually decreases and eventually phases out completely.
Because these thresholds adjust periodically, it is important to verify eligibility before making a contribution. Investors who exceed the limits may need to explore alternative strategies if Roth savings remain a priority.
Many high-income professionals, particularly those working in the technology sector, eventually encounter these income restrictions.
---
# Health Savings Accounts: One of the Most Powerful Tax Tools Available
For individuals enrolled in a **High Deductible Health Plan (HDHP)**, a **Health Savings Account (HSA)** can offer one of the most tax-efficient savings vehicles available.
HSAs are unique because they provide **three separate tax advantages**, often referred to as a “triple tax benefit.”
### 1. Tax-Deductible Contributions
Contributions to an HSA may reduce taxable income for the year.
### 2. Tax-Free Investment Growth
Funds inside the account can be invested and grow without annual taxation.
### 3. Tax-Free Withdrawals for Medical Expenses
Withdrawals used for qualified healthcare expenses are not taxed.
For the **2025 tax year**, HSA contribution limits are:
- **$4,300** for individual coverage
- **$8,550** for family coverage
- **Additional $1,000 catch-up contribution** for individuals age 55 or older
Many investors initially view HSAs as short-term healthcare spending accounts. However, when used strategically, they can become **an additional long-term retirement savings vehicle**.
Some individuals choose to pay current medical expenses out-of-pocket while allowing HSA investments to grow over time.
---
# Important HSA Rules to Know
While HSAs offer substantial tax benefits, there are several rules that should be understood before contributing.
### Employer Contributions Count Toward the Limit
If your employer contributes to your HSA, those contributions **count toward the annual limit**. It’s important to track total contributions to avoid exceeding the maximum.
### Eligibility Depends on Health Plan Type
To contribute to an HSA, you must be enrolled in a **qualified high deductible health plan (HDHP)** and cannot be covered by certain other health plans.
### The Last-Month Rule
In some situations, individuals who become eligible for an HSA late in the year may still contribute the **full annual amount** under what is known as the “last-month rule.”
However, this rule comes with additional requirements that must be satisfied the following year to avoid penalties.
---
# Avoiding Excess Contributions
One of the most common issues during tax season involves **excess contributions to tax-advantaged accounts**.
If too much money is contributed to an IRA or HSA and the error is not corrected, the IRS may impose a **6% penalty each year the excess remains in the account**.
Excess contributions often occur when:
- Investors contribute to multiple IRA accounts and lose track of totals
- Employer HSA contributions are not included in personal calculations
- Roth IRA contributions are made before income exceeds eligibility limits
Fortunately, many of these mistakes can be corrected if discovered **before the tax filing deadline**.
---
# Why Tax Planning Should Be Year-Round
While the filing deadline provides a final opportunity to adjust certain contributions, effective tax planning rarely happens in a single conversation each spring.
For many high-income professionals and business owners, the largest [tax opportunities involve coordinating multiple strategies](https://independentadvisorsnw.com/homepage/education/tax-optimization-strategies-for-high-earners/) throughout the year.
These may include:
- Managing capital gains within investment portfolios
- Planning around restricted stock units (RSUs) and stock options
- Coordinating charitable giving strategies
- Evaluating Roth conversion opportunities
- Optimizing retirement plan contributions
IRA and HSA contributions are often just **one component of a larger tax optimization strategy** designed to improve long-term outcomes.
---
# Final Thoughts
If you want IRA or HSA [contributions to apply to the **2025**](https://independentadvisorsnw.com/?post_type=dlm_download&p=2968) tax year, they generally must be completed before **April 15, 2026**.
Before making a contribution, it’s important to confirm:
- Income eligibility requirements
- Deduction limitations
- Employer contributions
- Coordination with other retirement and tax strategies
A brief review before the filing deadline can often uncover opportunities to **reduce taxes while strengthening long-term financial planning**.
For individuals with more complex financial situations—such as equity compensation, multiple retirement accounts, or significant investment income—professional guidance can help ensure these opportunities are fully utilized.
If you would like help evaluating your options, the team at **Independent Investment Advisors** can help review how IRA and HSA strategies fit within your broader financial and tax plan.

Financial Planner
[See Full Bio](https://independentadvisorsnw.com/author/financial-planner/) [ ](https://independentadvisorsnw.com/author/financial-planner/)
**Categories:** All Posts, Financial Planning
---
### [A Fresh Look at Trump Savings Accounts for Families](https://independentadvisorsnw.com/a-fresh-look-at-trump-savings-accounts-for-families/)
**Published:** February 27, 2026
**Author:** Financial Planner
**Excerpt:** Planning ahead for a child’s financial wellbeing is a priority for many families. Whether parents are thinking about future education expenses, saving for a first home, or wanting to give their child a head start, long-term savings tools can play a major role. One option that has recently started gaining attention is the Trump Savings Account, formally known as a Section 530A account.
**Content:**
Family saving money in piggy bank
Planning ahead for a child’s financial wellbeing is a priority for many families. Whether parents are thinking about future education expenses, saving for a first home, or wanting to give their child a head start, long-term savings tools can play a major role. One option that has recently started gaining attention is the Trump Savings Account, formally known as a Section 530A account. This program was introduced as part of the One Big Beautiful Bill Act (OBBBA) and is designed to support children from infancy through young adulthood.
If you are reviewing your family’s financial plan or exploring new ways to invest for the future, it’s helpful to understand how these accounts work, who can open one, and how they stack up against more established savings vehicles.
### What Are Trump Savings Accounts?
Trump Savings Accounts were created to function as tax-deferred investment accounts for individuals under the age of 18. Unlike short-term savings tools, these accounts are structured to encourage long‑range financial growth. Their core purpose is to help young people build savings they can later use for major life milestones.
A key highlight of these accounts is the one‑time federal seed deposit. Children born between January 1, 2025, and December 31, 2028, are eligible to receive a $1,000 initial contribution from the federal government. This early deposit is intended to jump‑start long-term investing and help families benefit from compounding growth over time.
Funds in these accounts can later support significant adult financial goals, including higher education, homeownership, or even the launch of a small business.
### Who Qualifies for an Account?
Eligibility is determined by age and birth year. Any child under age 18 with a valid Social Security number may have an account established for them. However, only children born within the 2025–2028 window qualify for the federal seed deposit.
Families with children born outside this range can still open an account and contribute, but they will not receive the government‑funded boost. Understanding these distinctions can help parents evaluate the potential value of opening an account for their child.
### Contribution Guidelines and Investment Approach
These accounts are structured to allow contributions from a variety of sources. Parents and guardians can add funds, and extended family members, such as grandparents, may also participate. In some situations, employers or nonprofit groups can contribute as well, as long as annual contribution rules are followed.
All money placed into the account is invested in low‑cost, diversified index funds. This investment strategy focuses on long-term market exposure rather than active management. Because earnings grow tax‑deferred, the account has the potential to build meaningful value over many years without immediate tax consequences.
### How Custodial Management Works
Trump Savings Accounts follow a custodial structure. Although the child legally owns the account, an adult—typically a parent or guardian—oversees it until the child turns 18. This includes managing contributions and ensuring the investment allocation remains consistent with the family’s long-term goals.
When the child reaches adulthood, full control of the account transfers to them. At that point, they can choose how to use the funds within the program’s guidelines.
### Withdrawals and Tax Treatment
One of the defining features of these accounts is their emphasis on long-term planning. Money in the account is generally locked in until the account owner reaches age 18. This restriction is designed to reinforce the account’s purpose as a future‑focused investment tool.
Once the account holder becomes an adult, withdrawals can be made for several major life expenses. Eligible uses include higher education costs, starting a business, buying a first home, or covering other substantial financial needs. Withdrawals are taxed as ordinary income, similar to traditional retirement accounts.
Because contributions are made with after‑tax dollars and earnings grow on a tax‑deferred basis, families may benefit from compounding over many years. However, early or non‑qualified withdrawals may result in penalties, so it is important to review the rules carefully before accessing funds.
### How Trump Savings Accounts Compare to 529 Plans
Many families are familiar with 529 plans, which are widely used for education‑focused savings. Although both tools support long-term planning, they operate differently.
529 plans are built specifically for education and provide tax advantages when used for qualified education expenses. Trump Savings Accounts, on the other hand, offer broader flexibility in adulthood but do not allow for early withdrawals related to education before age 18.
Rather than replacing a 529 plan, a Trump Savings Account may serve as an additional piece of a well‑rounded savings strategy.
### Important Planning Factors
Before opening a Trump Savings Account, it’s essential to consider how it aligns with your broader financial priorities. Parents should review whether retirement savings are on track, whether an emergency fund is in place, and how this account would complement current education savings tools.
Evaluating the tax impact, long-term implications, and overall financial fit can help ensure that adding this account strengthens the family’s planning framework.
### When Professional Advice Can Help
Planning for a child’s financial future often requires careful thought. A registered investment advisor can help clarify eligibility rules, contribution limits, tax considerations, and the account’s long‑term investment strategy. Because each family’s goals and financial situation are unique, professional guidance can help determine whether this type of account aligns with your overall wealth‑building approach.
Trump Savings Accounts offer a structured way to invest in a child’s future through tax‑deferred growth, diversified investments, and—when eligible—a federal seed contribution. For families looking to build long-term financial stability for their children, these accounts may provide valuable opportunities.
If you would like help determining whether a Trump Savings Account fits into your plan, our team is here to support you. We can walk through your options and help you make confident, informed decisions.

Financial Planner
[See Full Bio](https://independentadvisorsnw.com/author/financial-planner/) [ ](https://independentadvisorsnw.com/author/financial-planner/)
**Categories:** All Posts, Financial Planning
---
### [Fed Takes a Cautious Pause: Understanding the January 2026 Interest Rate Decision](https://independentadvisorsnw.com/fed-takes-a-cautious-pause-understanding-the-january-2026-interest-rate-decision/)
**Published:** February 18, 2026
**Author:** Goran Ognjenovic
**Excerpt:** The Federal Reserve kicked off 2026 with a careful and deliberate move, choosing to keep interest rates unchanged after lowering them several times at the end of 2025. During its January 28 meeting, the Fed held the federal funds rate between 3.50% and 3.75%.
**Content:**

The Federal Reserve kicked off 2026 with a careful and deliberate move, choosing to keep interest rates unchanged after lowering them several times at the end of 2025. During its January 28 meeting, the Fed held the federal funds rate between 3.50% and 3.75%. This decision reflects a measured approach as policymakers evaluate how the economy is adjusting. Below is a breakdown of what the Fed’s announcement means and how it could influence your financial outlook this year.
### The Fed Holds Rates After Late-2025 Reductions
After delivering three quarter-point cuts in the final stretch of 2025, the Fed paused its easing cycle heading into the new year. Ten members of the Federal Open Market Committee (FOMC) supported holding rates steady, while two members pushed for another cut.
Fed Chair Jerome Powell stressed that policymakers are not following a predetermined plan. Instead, each rate decision will depend on economic data available at the time. This approach highlights the Fed’s ongoing commitment to balancing its goals of stable prices and sustained employment.
### Labor Market Stabilizing, but Growth Remains Slow
One of the more positive signals noted during the meeting was the gradual stabilization of the labor market. Job creation has been modest, and the unemployment rate settled at 4.4% in December 2025. Other employment metrics — including job openings, layoffs, and wage increases — have shown minimal movement recently.
Powell also mentioned that slower labor force expansion plays a role in muted hiring. Lower immigration levels and reduced participation in the workforce are contributing to labor shortages. These limitations could continue to weigh on hiring trends and wage acceleration over the coming months.
### Inflation Still Above Target, but Cooling Continues
Although inflation remains higher than the Fed’s preferred 2% benchmark, recent numbers show a gradual cooling. Much of the upward pressure is tied to higher prices for goods, with Powell pointing out that increased import tariffs have been a key factor.
Meanwhile, inflation in the services sector — including housing, medical care, and transportation — is showing consistent signs of slowing. Importantly, long‑term inflation expectations remain anchored near the Fed’s target, indicating that consumers and businesses still anticipate a return to more stable pricing.
### A Solid Start to 2026 for the U.S. Economy
Despite certain challenges, the economy overall appears relatively steady as the year begins. Powell described the broader outlook as being on “firm footing,” supported by resilient consumer spending and steady levels of business investment.
Still, some areas are under pressure. The housing sector continues to struggle, and the temporary government shutdowns in late 2025 likely dragged on economic activity. Even so, the Fed believes current interest rates remain appropriate for supporting growth without overstimulating the economy.
### Policy Outlook: Prioritizing Flexibility
The Fed made it clear that it is not committing to a set trajectory for monetary policy. Instead, upcoming decisions will hinge on data related to employment, inflation, and financial conditions. This nimble approach recognizes the many uncertainties still present in the political and economic environment.
Powell reiterated that the Fed remains prepared to adjust as needed to maintain long‑run economic stability, emphasizing responsiveness over forecasting.
### What This Means for Your Financial Life
While interest rate announcements may feel distant from everyday concerns, they influence several aspects of personal finance. Here are some ways the January decision may impact your wallet:
**1. Mortgage Rates May Stay Attractive**
Mortgage rates dropped significantly after last year’s cuts and are currently near their lowest point in three years. Because the Fed’s pause was widely expected, markets have already priced it in. Going forward, mortgage rate movements will depend more on inflation trends and overall economic sentiment.
**2. Credit Card Rates Could Stabilize**
Borrowers saw small reductions in credit card interest rates toward the end of 2025. With no new cut in January, further declines may be limited for now. High APRs are still common, so any additional relief is likely to happen gradually.
**3. Savings Returns Likely to Hold Steady**
High-yield savings accounts and CDs continue to offer competitive returns. Because deposit rates tend to track the Fed’s benchmark rate, the pause suggests savers can expect similar yields for the time being. While inflation still eats into some returns, today’s savings rates remain historically appealing.
**4. Financial Markets May Stay Unpredictable**
Differences of opinion among FOMC members, lingering inflation issues, and the impact of recent political disruptions could all contribute to ongoing market swings. Investors should be prepared for potential ups and downs as the Fed navigates evolving conditions.
**5. Long‑Term Planning Remains a Priority**
With mixed economic signals and shifting financial dynamics, maintaining focus on long‑term goals is more important than ever. Reviewing your financial strategy periodically — whether it involves paying down debt, building savings, or planning for retirement — can help keep you on track.
### Stay Aware and Stay Prepared
The Fed’s opening meeting of 2026 reflects cautious optimism. Although challenges persist, the economy is showing resilience. For individuals and families, this means relative stability in borrowing and saving conditions, but it’s still wise to stay informed.
If you’re uncertain about how these shifts might affect your financial strategy or want guidance on adapting your plan, we’re always here to help. Reach out anytime to talk through your goals and how you can stay confident in a changing environment.

Goran Ognjenovic
[See Full Bio](https://independentadvisorsnw.com/author/gognjenovic/) [ ](https://independentadvisorsnw.com/author/gognjenovic/)
**Categories:** All Posts, Portfolio & Market Reviews
---
### [February 2026 Financial Market Update: A Fresh Look at Recent Trends](https://independentadvisorsnw.com/february-2026-financial-market-update-a-fresh-look-at-recent-trends/)
**Published:** February 16, 2026
**Author:** Goran Ognjenovic
**Excerpt:** January brought another month of steady economic momentum across the United States, marked by strong household spending and ongoing strength in the services sector.
**Content:**

January brought another month of steady economic momentum across the United States, marked by strong household spending and ongoing strength in the services sector. Lower [home loan rates](https://www.freddiemac.com/pmms) helped revive buyer interest, giving the housing market a noticeable lift as the new year began.
Even so, economic signals remain mixed. The manufacturing industry has now [posted declines](https://www.prnewswire.com/news-releases/manufacturing-pmi-at-47-9-december-2025-ism-manufacturing-pmi-report-302649307.html) for ten straight months, and while [inflation](https://www.cbsnews.com/news/cpi-report-today-inflation-december-2025-tariffs/) has eased from its highs, it’s still running warmer than policymakers would prefer. Meanwhile, the Federal Reserve is maintaining a cautious stance on rate cuts, despite rising calls for a more aggressive approach.
Here’s a breakdown of what took place in January, what’s driving the headlines, and the areas we’re watching closely.
### Major U.S. Stock Indices
After spending much of the past few years overshadowed, small-cap companies staged an impressive comeback early in 2026. The Russell 2000 outpaced the S&P 500 and Nasdaq for [14 consecutive trading days](https://www.nasdaq.com/articles/market-just-did-1st-time-30-years-heres-what-history-says-happens-next#:~:text=See%20the%20stocks%20%C2%BB,caps%20begin%20outperforming%20large%20caps), marking a notable shift in market leadership.
This trend suggests that investors are widening their search for opportunities, moving beyond mega-cap technology names to areas more tied to local economic conditions and companies that benefit from more favorable financing environments.
Overall performance for January included:
- The S&P 500 [rose](https://www.tradingview.com/x/RVL93OXo/) by 1.37%.
- The Nasdaq 100 [added](https://www.tradingview.com/x/Yp0VkvKB/) 1.20%.
- The Dow Jones Industrial Average [led the group](https://www.tradingview.com/x/S2vy8n27/) with a 1.73% gain.
### Economic Snapshot
The economy carried strong momentum into 2026. Third-quarter 2025 GDP [reached](https://www.ey.com/en_us/insights/strategy/macroeconomics/us-gdp) an annualized rate of 4.4%, the best in two years, while early estimates for Q4 pointed to continued strength in the 3–4% range. However, signs indicate that growth may now be leveling off.
Recent high-frequency indicators show activity narrowing, with services and government spending doing more of the heavy lifting while private-sector demand becomes more uneven. Most economists anticipate a shift toward a steadier 2% trend for the remainder of 2026—solid, but far from the brisk pace of last year.
Labor data reflected a cooling job market. December payrolls increased by just 50,000 compared with 2024’s monthly average of 168,000, with reductions concentrated in retail and manufacturing roles. The unemployment rate stayed at 4.4%, reinforcing the idea of a gradual slowdown rather than an abrupt downturn.
Wage pressures have eased, helping keep household purchasing power intact while also reducing the risk of renewed inflation. The Consumer Price Index registered a 2.7% increase year over year in December, inching closer to the Federal Reserve’s target but not quite reaching it. A complicating factor: producer prices saw their fastest monthly increase in five months, reflecting higher costs tied to new tariffs.
At its late-January meeting, the Federal Reserve held interest rates [unchanged](https://www.cnbc.com/2026/01/28/fed-rate-decision-january-2026.html) at 3.5–3.75% and indicated that only one potential rate cut remains on the table for 2026. The Fed emphasized a data-driven approach and reaffirmed its independence as political voices push for a different course.
The ISM manufacturing index stayed in contraction territory for the tenth month at 47.9. Soft order volumes, declining inventories, and increased layoffs—exacerbated by tariff-related pressures—continue to weigh on the sector. In contrast, services industries are still expanding, existing-home sales climbed 5% in December thanks to lower mortgage rates, and credit markets remain calm with spreads near historic lows. The result is a split economy: manufacturing softness on one side and consumer resilience on the other.
### Our Outlook
We’re operating in an environment characterized by moderate growth, ongoing disinflation, and a Federal Reserve nearing the end of its easing cycle. One encouraging trend is the widening of market leadership. After years of outsized returns in mega-cap technology, smaller companies and cyclical sectors are beginning to catch up, offering fresh opportunities for diversification.
Still, this late-phase expansion brings its own uncertainties. Policy shifts, geopolitical tensions, and uneven data are likely to create occasional bouts of volatility. Our approach balances participation in cyclical areas with a continued focus on high-quality assets, disciplined valuations, and maintaining liquidity for new openings that may emerge.
As always, if you’d like to talk through these developments or review your portfolio, our team is here and ready to help.

Goran Ognjenovic
[See Full Bio](https://independentadvisorsnw.com/author/gognjenovic/) [ ](https://independentadvisorsnw.com/author/gognjenovic/)
**Categories:** All Posts, Portfolio & Market Reviews
---
### [Protecting Your Wealth: Estate Planning Essentials for Tech Families](https://independentadvisorsnw.com/protecting-your-wealth-estate-planning-essentials-for-tech-families/)
**Published:** June 3, 2025
**Author:** Goran Ognjenovic
**Content:**
In today’s fast-moving tech-driven world, estate planning is no longer optional—especially for professionals in the technology industry. Whether you’re building equity through stock options, scaling a startup, or managing a high-income household, having a thoughtful estate plan ensures your assets are protected, your wishes are honored, and your loved ones are provided for.
Here are the estate planning essentials every tech family should consider:
---
### 1. **Start with a Will and Revocable Living Trust**
For many tech professionals, equity compensation (such as RSUs or stock options) forms a large part of net worth. A will ensures your basic wishes are honored, but a **revocable living trust** allows for greater control, avoids probate, and provides privacy. It also streamlines asset transfer and protects heirs from unnecessary legal delays.
---
### 2. **Understand How Tech-Specific Assets Pass**
From cryptocurrency wallets to intellectual property and stock grants, digital assets require tailored planning. Make sure:
- Your estate documents reference **digital assets**
- You leave **secure instructions for access** to digital accounts and wallets
- You understand **vesting schedules and transferability** of stock options or startup shares
---
### 3. **Update Beneficiary Designations**
401(k)s, IRAs, and life insurance policies **pass outside of your will or trust**. Make sure your beneficiary designations align with your broader estate plan, especially if you experience major life changes (marriage, divorce, children, liquidity events).
---
### 4. **Plan for Income and Estate Taxes**
Tech wealth can grow rapidly, sometimes unexpectedly. Without careful planning, your estate may face significant tax consequences. Consider:
- **Gifting strategies** to reduce taxable estate size
- **Trust structures** (e.g., SLATs, GRATs, ILITs)
- Working with a **financial advisor and estate attorney** to coordinate tax-smart asset transitions
---
### 5. **Include Powers of Attorney and Advance Directives**
Wealth protection includes **incapacity planning**. Designate financial and healthcare power of attorney and create a living will so decisions are made according to your wishes if you’re unable to speak for yourself.
---
### 6. **Involve the Right Professionals**
Work with a team that understands both **complex equity compensation** and **estate planning law**. Your team should ideally include:
- A fiduciary financial advisor (like us!)
- An estate planning attorney
- A tax strategist or CPA
---
### Final Thoughts
Estate planning is not just about distributing assets after you’re gone—it’s about protecting your family, your values, and your legacy. For tech families in **Portland, Beaverton, and Hillsboro**, we specialize in bridging the gap between equity-based wealth and long-term financial security.
**Need help navigating your estate plan? [Schedule a free consultation](https://outlook.office365.com/book/IndependentInvestmentAdvisors@mlignw.com/)** to start building your family’s blueprint for the future.

Goran Ognjenovic
[See Full Bio](https://independentadvisorsnw.com/author/gognjenovic/) [ ](https://independentadvisorsnw.com/author/gognjenovic/)
**Categories:** All Posts, Financial Planning, Investment Advisor
---
### [MSN Article: Goran Ognjenovic Wealth Management Blueprint: Charting a Path to Secure Retirement](https://independentadvisorsnw.com/goran-ognjenovic-featured-in-a-msn-article-wealth-management-blueprint-charting-a-path-to-secure-retirement-december-8th-2023/)
**Published:** December 8, 2023
**Author:** Investment Advisor
**Content:**
In an era where financial security in retirement is increasingly a societal concern, Goran Ognjenovic, founder and principal advisor of Independent Investment Advisors, emerges as a key figure in navigating these turbulent waters. With a career spanning over 18 years, Ognjenovic has established himself as an authority in wealth management, particularly in the critical areas of retirement and investment planning. His Oregon-based firm, established in 2017, is a testament to his commitment to providing comprehensive financial solutions across the United States, mirroring the functionality of a multifamily wealth management office.
Goran’s expertise is especially relevant in today’s context, where the retirement landscape is undergoing a seismic shift. The move away from traditional pension plans to self-directed retirement strategies has placed a greater onus on individuals to secure their financial future. Goran’s approach, characterized by its depth and adaptability, addresses the pressing concerns faced by clients: ensuring a sustainable financial future in retirement, adept tax optimization, and managing the burdens of rising healthcare costs. Amidst an investment climate marked by uncertainty and shifting economic patterns, his advocacy for a proactive and varied management strategy is both timely and prudent.
At the core of Goran’s advisory methodology are tax-deductible strategies, which he likens to a set of precise tools, each selected and applied based on the unique financial circumstances of an individual. His focus on tax optimization takes into account a comprehensive range of factors, from federal and state tax implications to inheritance considerations and Required Minimum Distributions.
Ognjenovic also sheds light on the evolution brought about by ETFs in investment options that offer retirement benefits and tax advantages. This revolution in financial instruments has democratized access to sophisticated strategies, allowing individual investors to compete with large institutions. He further explores the crucial role of asset location in managing tax-deferred and tax-free accounts, emphasizing the nuanced interplay between various investment options and account strategies.
In delineating the differences between tax-deferred and tax-exempt investments, Goran provides clarity in a complex area. Tax-deferred investments like Traditional IRAs or 401(k)s offer immediate tax benefits and are ideal during peak earning years. In contrast, tax-exempt investments such as Roth IRAs offer the advantage of tax-free withdrawals, enhancing flexibility in retirement income management.
For individuals navigating the maze of tax-advantaged retirement and investment options, Goran’s counsel is invaluable. He advises on considering factors like current and future tax situations, contribution limits, and the potential of underutilized tax deductions and credits. His endorsement of Health Savings Accounts (HSAs) as a long-term retirement savings vehicle, for their triple tax advantage, is particularly noteworthy.
In a society grappling with the complexities of retirement planning, Goran’s firm stands out for its integrated approach, combining financial planning, tax planning, and investment management. This holistic strategy is vital in an environment where tax planning is an essential, year-round activity.
Goran explains how diversification in a portfolio is essential in supporting tax efficiency in retirement and investment strategies. This strategy includes strategic placement of different types of investments across various account types and tax-efficient asset allocation. It also encompasses the management of Required Minimum Distributions from tax-deferred accounts, potentially minimizing their tax impact.
He outlines strategies that merge tax efficiency with effective retirement planning, such as Roth IRA Conversions and Municipal Bond Investments. These strategies not only mitigate the tax impact of investment decisions but also align with long-term retirement aspirations.
Amid the current social dialogue on retirement planning, Ognjenovic discusses various tax deductions and incentives for retirement and educational expenses. His emphasis on understanding tax-advantaged retirement accounts, their tax treatments, and the implications of Required Minimum Distributions is particularly relevant.
In a landscape where tax laws are constantly evolving, Ognjenovic underscores the importance of adapting retirement and investment strategies. He points to the Secure Act 2.0 as a prime example of significant legislative changes that present new opportunities for enhanced tax planning.
The benefits of incorporating tax-efficient methods in retirement and investment portfolios are profound. These methods help to alleviate the tax burden on investment returns, preserve wealth, and provide estate planning advantages. Ognjenovic guidance, rooted in relentless diligence, discipline, and planning, is critical for achieving tax-efficient outcomes in retirement and investment savings.
He also discusses the role of an individual’s risk tolerance in shaping tax-efficient retirement and investment decisions. This aspect is crucial in selecting investment vehicles, determining asset allocation, and formulating tax-efficient strategies.
Through disciplined processes and frameworks, his firm assists clients in adjusting their strategies in response to changing tax laws and market conditions. This approach ensures that clients are well-equipped to capitalize on new opportunities and navigate the challenges presented by the evolving economic landscape.
He also highlights investment options that align with social responsibility goals, catering to investors who seek to integrate their financial objectives with broader societal and environmental considerations.
Sharing success stories, Goran illustrates how clients, especially those with substantial amounts in tax-deferred accounts, have realized significant benefits from tax optimization and tax-advantaged allocation, often achieving tax savings in the seven-figure range over their lifetimes.
In a world where securing a financially stable retirement is increasingly a focal point of social discourse, Goran Ognjenovic expertise and strategic approach in wealth management offer indispensable guidance. His insights not only pave the way for financial stability and growth but also exemplify the convergence of tax efficiency and effective retirement planning in addressing this critical societal challenge.
[https://www.msn.com/en-us/news/news/goran-ognjenovics-wealth-management-blueprint-charting-a-path-to-secure-retirement/ar-AA1lc98A?disableErrorRedirect=true&infiniteContentCount=0](https://www.msn.com/en-us/news/news/goran-ognjenovics-wealth-management-blueprint-charting-a-path-to-secure-retirement/ar-AA1lc98A?disableErrorRedirect=true&infiniteContentCount=0)

Investment Advisor
[See Full Bio](https://independentadvisorsnw.com/author/investment-advisor/) [ ](https://independentadvisorsnw.com/author/investment-advisor/)
**Categories:** Featured Article
---
### [ETF.com: Recognized as a Top 100 Financial Advisor by ETF.com!](https://independentadvisorsnw.com/exciting-news-recognized-as-a-top-100-financial-advisor-by-etf-com/)
**Published:** November 18, 2024
**Author:** Investment Advisor
**Content:**
I am honored to share that I have been named to the [**ETF.com Leaders Top 100 Financial Advisors List**! ](https://www.etf.com/top-100-advisors/goran-ognjenovic)
[](https://www.etf.com/top-100-advisors/goran-ognjenovic)This recognition is a testament to the dedication and care I bring to serving my clients and helping them navigate the complexities of wealth management.
Being included in this prestigious list is not just a personal achievement—it’s a reflection of the incredible relationships I’ve built with my clients and the trust they place in me. At the heart of my practice is a commitment to providing thoughtful, personalized solutions that empower individuals and families to achieve their financial goals.
This recognition fuels my passion to keep delivering holistic, forward-thinking financial strategies that integrate everything from [investment management to tax](https://independentadvisorsnw.com/advisor-qa-how-to-guide-to-tax-optimized-investing-tax-deductions-and-incentives/) and estate planning. The ever-changing financial landscape presents unique challenges, but it also offers opportunities to grow, adapt, and refine the ways I help my clients succeed.
Thank you to ETF.com for this honor, and most importantly, thank you to my clients. You are the reason I strive for excellence every day.

Investment Advisor
[See Full Bio](https://independentadvisorsnw.com/author/investment-advisor/) [ ](https://independentadvisorsnw.com/author/investment-advisor/)
**Categories:** All Posts, Featured Article
---
### [Nasdaq.com: Goran Ognjenovic on Holistic Approach to Wealth Management for Financial Success](https://independentadvisorsnw.com/goran-ognjenovic-featured-in-a-nasdaq-article-a-holistic-approach-to-wealth-management-for-financial-success-march-5th-2024/)
**Published:** March 5, 2024
**Author:** Investment Advisor
**Content:**
Sustained financial success requires a nuanced strategy that extends beyond basic investment decisions. Embracing a holistic perspective on wealth management, which encompasses financial planning, investment strategy, and tax optimization, is crucial for attaining enduring financial prosperity and stability.
## The Pillars of Holistic Wealth Management
Financial Planning: The foundation of any successful wealth management strategy is comprehensive financial planning. This process involves setting short-term and long-term financial goals and developing a roadmap to achieve them. It encompasses budgeting, saving, debt management, and planning for life’s significant events, such as purchasing a home, funding education, and retirement. Effective financial planning provides a clear overview of one’s financial situation to make informed decisions and adjust strategies as circumstances change.
Investment Strategy: While financial planning sets the stage, a tailored investment strategy plays a crucial role in achieving financial goals. This involves the selection of investment vehicles that align with the individual’s risk tolerance, time horizon, and financial objectives. Diversification across asset classes (stocks, bonds, real estate, etc.) is a key principle, helping to mitigate risk and capitalize on growth opportunities. A dynamic investment strategy that adapts to market changes and personal life transitions is essential for long-term wealth accumulation.
Tax Optimization: Often overlooked, tax optimization is a critical component of holistic wealth management. It involves structuring investments and financial activities in a way that minimizes tax liabilities and maximizes after-tax returns. Strategies such as tax-loss harvesting, making the most of tax-advantaged accounts (like IRAs and 401(k)s), and considering the tax implications of investment choices can significantly impact net wealth. Understanding and leveraging tax laws require expertise but offer substantial rewards in enhancing wealth preservation and growth.
## The Role of Professionals in Holistic Wealth Management
Achieving a holistic approach to wealth management can be complex, requiring expertise across various financial disciplines. This is where professionals like Goran Ognjenovic from Independent Investment Advisors come into play. By leveraging their expertise, individuals can benefit from tailored advice that considers all aspects of their financial lives. These professionals can offer insights into market trends, tax laws, and financial planning strategies, ensuring that their clients’ wealth management approach is comprehensive, integrated, and aligned with their unique goals and circumstances.
## A Holistic Approach and Your Future
A holistic approach to wealth management, integrating financial planning, investment strategy, and tax optimization, is not just a luxury but a necessity for those looking to secure their financial future. By considering the interconnections between different financial areas, you can make informed decisions that propel you toward your goals. For example, investment choices are made with an understanding of their tax implications and in the context of your broader financial objectives. Similarly, financial planning takes into account the need for sufficient liquidity to fund short-term plans without compromising long-term investment growth.
Moreover, by considering the full spectrum of financial activities, you can identify synergies and opportunities that might be missed when these areas are managed in isolation. Finally, a holistic strategy is adaptable. This flexibility is crucial in maintaining a path toward financial objectives despite the inevitable uncertainties of life.
With the guidance of professionals like Goran Ognjenovic, achieving a balanced and effective wealth management strategy is within reach. Among the many benefits is peace of mind and financial security for yourself and future generations.

Investment Advisor
[See Full Bio](https://independentadvisorsnw.com/author/investment-advisor/) [ ](https://independentadvisorsnw.com/author/investment-advisor/)
**Categories:** Featured Article
---
### [How to Teach Kids About Money: A Guide to Raising Financially Savvy Children](https://independentadvisorsnw.com/how-to-teach-kids-about-money-a-guide-to-raising-financially-savvy-children/)
**Published:** May 9, 2025
**Author:** Ian Teh
**Content:**
**Raising Financially Confident Kids: Why Early Money Lessons Matter**
Financial literacy isn’t just a nice-to-have—it’s an essential life skill. Studies from the National Endowment for Financial Education (NEFE) and the Federal Reserve consistently show that early, consistent financial education leads to smarter money decisions in adulthood. From choosing student loans wisely to building retirement savings, financially literate individuals are more likely to avoid debt traps and reach long-term financial goals.
**Start Early: Money Lessons for Young Children**
Children as young as three can start learning about money through play and simple observation. Their natural curiosity about numbers, coins, and everyday purchases creates the perfect opportunity for informal learning.
- **Use transparent piggy banks** with separate compartments for **spending, saving, investing, and giving** to teach budgeting and goal setting.
- Turn everyday activities into teachable moments. For example, **grocery shopping** can become a lesson in comparison shopping and needs vs. wants.
- Play-based tools like **Monopoly**, **storefront pretend games**, or apps that simulate transactions can make abstract concepts tangible.
**Smart Allowance Strategies**
An allowance isn’t just pocket change—it’s a hands-on classroom for real-world money decisions. Surveys show nearly 80% of parents use allowances to teach financial responsibility.
- The popular **“one dollar per year of age” rule** provides a consistent structure.
- Tie allowances to age-appropriate financial goals, but consider keeping **chore expectations separate** to promote a sense of family teamwork.
- Encourage kids to **divide their allowance** into jars or subaccounts (e.g., for spending, saving, giving), helping them develop early budgeting habits.
**Make Compound Interest Come to Life**
You don’t need a finance degree to teach kids about the power of compound growth. Simple visuals can drive the point home:
- Compare two jars—one with regular deposits, the other with “interest” added weekly.
- Use the **penny-doubling experiment** to show how even small amounts grow dramatically over time.
**Preteens and Teens: Investing, Credit, and Retirement Planning**
As children mature, expand financial lessons to include investing and credit fundamentals:
- **Custodial brokerage accounts** (UGMA/UTMA) allow kids to experience stock ownership and tax basics under adult supervision.
- **Roth IRAs for kids** with earned income (including self-employment) provide a powerful introduction to tax-advantaged retirement saving.
- Add teens as **authorized users on a credit card** (with responsible use) to help establish credit history early.
**Digital Tools That Make Learning About Money Fun**
Tech-savvy kids respond well to interactive platforms. Apps like:
- **BusyKid** – Combines chores, allowance, and real investing options.
- **KidVestors** – Focuses on stock market literacy for youth.
- **Greenlight** – Offers debit cards and customizable savings goals with parental controls.
These tools gamify personal finance and build habits through real-time learning.
**Financial Education in Schools: A Critical Piece**
Formal education matters, too. Research from GFLEC and NEFE shows that **school-based personal finance courses** lead to better outcomes—including improved credit scores and reduced delinquency. States that mandate financial literacy report stronger student knowledge and healthier long-term behaviors.
- Schools can integrate lessons into **math, economics, or social studies**.
- Partnering with teachers or offering volunteer classroom sessions can extend reach into underserved communities.
**Lead by Example: The Power of Parental Modeling**
Ultimately, children learn most from what they see. Normalize discussions about money—budgeting, saving, charitable giving, and even investing. Let your children see you making thoughtful financial decisions and include them in age-appropriate conversations.
---
**Conclusion: Financial Education is the Greatest Gift You Can Give Your Child**
By combining **early exposure**, **hands-on experiences**, **structured tools**, and **positive modeling**, families can help children grow into confident and capable adults. Financial literacy is more than dollars and cents—it’s about freedom, opportunity, and security. Start early, stay consistent, and you’ll set your children up for a lifetime of smart decisions and financial independence.

Ian Teh
[See Full Bio](https://independentadvisorsnw.com/author/infomlignw-com/) [ ](https://independentadvisorsnw.com/author/infomlignw-com/)
**Categories:** All Posts, Financial Planning
---
### [Tech Stocks & Your Portfolio: How to Avoid Overconcentration Risk](https://independentadvisorsnw.com/tech-stocks-your-portfolio-how-to-avoid-overconcentration-risk/)
**Published:** February 21, 2025
**Author:** Ian Teh
**Content:**
# Tech Stocks & Your Portfolio: How to Avoid Overconcentration Risk
## Why Too Much Company Stock Can Hurt Your Financial Future—And How to Fix It
For many technology professionals, company stock is a significant wealth-building tool. Generous equity compensation—through **Restricted Stock Units (RSUs), Stock Options, Employee Stock Purchase Plans (ESPPs), or stock grants**—can lead to substantial gains.
However, holding too much company stock can expose your portfolio to excessive volatility, leaving your wealth vulnerable to market downturns, company-specific risks, and unexpected economic shifts.
## The Risks of Overconcentration in Company Stock
### 1️⃣ Lack of Diversification = Increased Volatility
- **Meta (Facebook)** stock lost over 70% in 2022 before rebounding.
- **Netflix** dropped 75% in six months during 2022.
- **Amazon** declined nearly 50% in the same year.
If your portfolio is too concentrated in one stock, a single bad earnings report, regulatory change, or economic downturn could significantly impact your financial security.
### 2️⃣ Double Exposure: Your Job + Your Investments
Tech professionals face a unique risk:
- Your **income** (salary, bonuses, RSUs) is already dependent on your employer.
- Your **investment portfolio** is also heavily tied to the same company.
## How Much Company Stock is Too Much?
Financial professionals often recommend keeping **no more than 10-15% of your portfolio in a single stock**. If your employer’s stock represents more than 20% of your total portfolio, it’s time to consider diversification strategies.
## Strategies to Reduce Overconcentration Risk
### 1️⃣ Diversify with Thoughtful Evaluation
- Assess your company’s **growth potential**.
- Align with your **long-term financial goals**.
- Consider your **overall risk tolerance**.
### 2️⃣ Gradual Selling Plans (Systematic Diversification)
- Sell a percentage of shares quarterly or annually.
- Use proceeds to diversify into ETFs, bonds, real estate, or alternative investments.
### 3️⃣ Options Strategies for Risk Management
- **Covered Calls**: Generate extra income while limiting downside risk.
- **Collars**: Use covered calls and protective puts to cap losses while preserving upside.
- **Protective Puts**: Lock in a minimum price for shares.
### 4️⃣ Tax-Loss Harvesting
Example: If you realize a **$50,000 gain** from selling company stock, you could sell other investments that are down **$30,000**, reducing taxable gains to **$20,000**.
### 5️⃣ Reinvest ESPP Proceeds
Consider selling ESPP shares as soon as they are eligible and reinvesting for diversification.
## Final Takeaway: Be Strategic, Not Emotional
- Set a target allocation—keep company stock under **10-15%** of your portfolio.
- Gradually reduce exposure using systematic selling and tax-efficient strategies.
- Diversify your portfolio to ensure long-term financial security.

Ian Teh
[See Full Bio](https://independentadvisorsnw.com/author/infomlignw-com/) [ ](https://independentadvisorsnw.com/author/infomlignw-com/)
**Categories:** All Posts, Investment Advisor
---
### [The "Great Resignation"](https://independentadvisorsnw.com/the-great-resignation/)
**Published:** October 29, 2021
**Author:** Investment Advisor
**Excerpt:** How are you feeling about work these days? Are you taking stock of your life and thinking about moving on? (You're not alone.) Are you a boss struggling to fill roles and retain your people? (You're in good company.)
**Content:**
[< back to Market Insights Blog](https://independentadvisorsnw.com/homepage/markets-insights/)
How are you feeling about work these days?
Are you taking stock of your life and thinking about moving on? (You’re not alone.)
Are you a boss struggling to fill roles and retain your people? (You’re in good company.)
America is going through a pretty major reconfiguration of the labor market.
Headlines are calling it the Great Resignation but I think its deeper than that The pandemic threw many assumptions out of the window It caused us to think long and hard about a lot of thingsHeadlines are calling it the “Great Resignation” but I think it’s deeper than that.
The pandemic threw many assumptions out of the window. It caused us to think long and hard about a lot of things.
Where we work. How we work. What work means. What we want out of life.
**That existential crisis is visible on the supply side of the labor market:**
Folks retiring ahead of schedule (not all by choice).1
Folks quitting their jobs.2
Folks (primarily women) caring for kids and family instead of going back to work.3
Folks striking over pay and working conditions.4
Folks starting new businesses.5
**And it’s visible on the demand side as well:**
Restaurants struggling to staff up.6
Shipping ports clogging up because there aren’t enough truckers to haul goods away.7
Employers offering higher wages and perks to attract job seekers.8
**At its most basic level, employment is a transaction: a certain amount of work for a certain amount of pay.**
But it’s really much more than that.
For many of us, who we are as a worker…
A business owner…
A boss…
Is central to our identity.
And the ground is shifting under our feet. That makes folks anxious.
High-anxiety times like these bring plenty of judgment, blame, and dramatic headlines.
**Are workers who don’t want to take low-paying, high burnout jobs lazy?**
Of course not.
Are [business owners](https://independentadvisorsnw.com/solutions/financial-investment-solutions-for-small-business-owners/) worried about keeping their doors open evil capitalists?
Nope.
Are employees organizing strikes or leaving for better opportunities disloyal?
No way.
We’re all doing the best we can every day.
When we see talking heads griping about “entitled” workers or “greedy” businesses, let’s remember that behind the numbers are real people with real struggles.
A parent with a medically fragile kid who is afraid to go back to work.
A business owner who worries the staffing shortage will put her out of business.
A laid-off worker who doesn’t have the skills needed to get a different job.
A manager who is doing two jobs because he can’t fill a key role.
Let’s be compassionate toward one another.
**What does the labor market upheaval mean for the economy?**
That’s hard to say.
It could cause a slowdown in some sectors if businesses struggle to fulfill demand.
It could lead to increased inflation if higher wages get passed on as higher prices.
It could be a factor in a market correction.
It could also accelerate trends toward automation, remote work, and offshoring.
**Bottom line: Like most major events in history, the overall consequences won’t be fully visible for a long time.**
I’ll close by asking: what’s your take on all this, Goran?
Are you pondering any big work or life changes?
Hit “reply”and let me know.
Be well,
**Goran Ognjenovic**
Independent Investment Advisors
(971) 350-8068
[www.independentadvisorsnw.com](https://independentadvisorsnw.com)
---
P.S. What else do you think the pandemic will change? Any thoughts to share?
1
2
3
4
5
6
7
8
The following posts and commentary are to be used solely as educational tools and do not contain investment advice. Investment advice must be tailored to a particular investor’s specific needs. None of the information contained should be construed to be investment advice. Individuals wishing to tailor a plan to their own needs should seek the help of a Registered Investment Advisor.
There is a high degree of risk in investing and trading. Independent Investment Advisors assumes no responsibility. Principles of Independent Investment Advisors may, at times, maintain directly or indirectly, positions in securities or derivatives mentioned in these comments.

Investment Advisor
[See Full Bio](https://independentadvisorsnw.com/author/investment-advisor/) [ ](https://independentadvisorsnw.com/author/investment-advisor/)
**Categories:** All Posts, Investment Advisor
---
### [USA Today: Goran Ognjenovic on Life Holistic Wealth Management](https://independentadvisorsnw.com/goran-ognjenovic-featured-in-a-usa-today-article-independent-investment-advisors-offers-a-holistic-approach-to-wealth-management-aug-27th-2024/)
**Published:** September 18, 2024
**Author:** Investment Advisor
**Content:**
It takes a lot of time and hard work to build wealth, but only a moment to lose it. Many high-earners and small business owners underestimate the effort it takes to maintain wealth and ensure their future financial success. While plenty of companies help clients manage their investments and navigate risk, many of them neglect areas like tax or estate planning. To achieve financial freedom, clients need an advisor who can help them navigate the ins and outs of wealth management.

That’s the goal of [Independent Investment Advisors](https://independentadvisorsnw.com/), a multi-family wealth management office led by Goran Ognjenovic. Independent Investment Advisors works with high-net-worth individuals, families, and [small business owners](https://independentadvisorsnw.com/solutions/financial-investment-solutions-for-small-business-owners/) to help them manage every aspect of their finances. Unlike other wealth management companies, IIA provides a comprehensive set of services including financial planning, retirement planning, tax planning, estate planning, investment management, and risk management.
“Nowadays, you need much more than just investment returns to achieve wealth success,” says Goran. “We believe in a holistic, comprehensive approach to wealth management that includes financial, tax, and estate planning.”
Before founding Independent Investment Advisors in 2017, Goran began his career in 2003 as an independent investor. It was there that he developed a deep understanding of the markets and learned how to build successful investment portfolios.
“It’s hard to believe, but financial markets and tax rules seem to be in constant flux,” says Goran. “Something is always changing and staying on top of those changes and helping our clients adapt is our ongoing purpose and mission.”
The upcoming end to the Tax Cuts and Jobs Act is one of the biggest fluctuations in tax planning that Goran fears most taxpayers aren’t prepared for. With the current tax rates set to end on Dec 31st, 2025, the top tax rate will increase while the standard deduction will be cut almost in half. It’s these kinds of changes that Independent Investment Advisors wants to help their clients navigate.
A 20+ year veteran of the investing markets, Goran makes sure to always stay up-to-date on the latest financial trends. One of his biggest assets is the ability to explain complex financial concepts to his clients in a way they can understand. Client relationships are Independent Investment Advisors’ number one priority, which is why they work with a limited number of clients to provide ongoing financial planning and advice. The low advisor-to-client ratio helps them build deeper relationships with their clients, creating custom financial plans and portfolios to deliver better results.
As Goran puts it, the biggest takeaway he wants for his clients is the understanding that anything worth doing takes time, focus, patience, and hard work. “There will be plenty of challenges along the way,” he says.
“You just have to rise above, look at things logically, and focus on the next task.” It’s part of what Goran refers to as continuous incremental improvement, the idea that focusing on small tasks rather than the big picture is what helps people find success. “If I can just improve one thing and be better tomorrow than I am today,” says Goran,” over time it will make a huge difference.”
*Investing involves risk and your investment may lose value. Past performance gives no indication of future results. These statements do not constitute and cannot replace investment advice.*

Investment Advisor
[See Full Bio](https://independentadvisorsnw.com/author/investment-advisor/) [ ](https://independentadvisorsnw.com/author/investment-advisor/)
**Categories:** Featured Article
---
### [New Hampshire investigates Merrill Lynch after clients allege $200 million in damages](https://independentadvisorsnw.com/new-hampshire-investigates-merrill-lynch-after-clients-allege-200-million-in-damages/)
**Published:** July 13, 2020
**Author:** Investment Advisor
**Content:**
Here is another one. This one is a high profile Investment/Finacial Advisor horror story involving no less than a state governor and a well-known asset manager. I will get on my soapbox again! Investors have to understand how their advisor is getting compensated and who is the custodian of their assets. Regulators have enacted new laws and fiduciary rules, but in essence, all they mean/require is more disclosure. Rules and rotten advisors are difficult to enforce and monitor. The best advice I can give to investors is to [choose your advisor](https://iiaproduction.wpengine.com/homepage/investor-education-center/how-to-choose-a-financial-advisor/) and make the relationship personal. Independent, fiduciary, fee-only advisors can make all the difference.
You can find the original CNBC Story here:
[https://www.cnbc.com/2020/07/13/new-hampshire-investigates-merrill-lynch-after-clients-allege-200-million-in-damages.html?\_\_source=sharebar|email&par=sharebar](https://www.cnbc.com/2020/07/13/new-hampshire-investigates-merrill-lynch-after-clients-allege-200-million-in-damages.html?__source=sharebar|email&par=sharebar)
**KEY POINTS**
· New Hampshire’s Bureau of Securities Regulation is investigating Merrill Lynch and at least one former top broker over alleged churning of customer accounts to generate millions of dollars in excess commissions.
· Separately, former New Hampshire Gov. Craig Benson has alleged in an arbitration claim that he lost $100 million due to churning and unauthorized trading.
· Merrill Lynch fired the broker in charge of the accounts, but says the claim by Benson, whom the firm calls a sophisticated investor, “doesn’t add up.”
· A CNBC investigation has found the firm previously paid a record $40 million to settle similar allegations by Robert Levine, Benson’s former business partner and co-founder of Cabletron.
New Hampshire authorities are investigating Merrill Lynch and at least one former top broker over customer complaints of alleged misconduct that resulted in staggering losses, according to multiple sources familiar with the investigation.
According to the sources, the state regulator has approached Merrill Lynch, a subsidiary of Bank of America, with its findings. In addition, two sources say settlement talks are underway.
A spokesman for the New Hampshire Bureau of Securities Regulation declined to comment, while a spokesman for Merrill Lynch said the firm “does not comment on the existence of regulatory inquiries.”
The disclosure of the investigation is on Charles Kenahan’s Financial Industry Regulatory Authority (FINRA) BrokerCheck report, which says “the state of New Hampshire is conducting an investigation into certain trading practices of Mr. Kenahan.”
**This is a fight I never chose. … Both Bob and I caught Merrill Lynch with our wallets in their hands.**
**Craig Benson**
**FORMER GOVERNOR OF NEW HAMPSHIRE**
One of Kenahan’s former clients who alerted the state securities regulator of the alleged wrongdoings is Craig Benson, New Hampshire’s governor from 2003 to 2005.
“I certainly didn’t sign a document and say it’s OK to steal from me,” Benson told CNBC. “This is a fight I never chose. … “Both Bob and I caught Merrill Lynch with our wallets in their hands.”
Bob is Robert Levine, a long-time friend and business partner who has already received a [record $40 million](https://www.cnbc.com/2019/07/19/merrill-lynch-pays-40m-to-cabletron-co-founder-after-alleged-churning.html) payout from Merrill Lynch after the firm decided to settle allegations of unsuitable investment recommendations, excessive trading and misrepresentation brought by Levine through a FINRA arbitration complaint. Levine alleged in his complaint he sustained damages of more than $100 million.
A CNBC investigation obtained FINRA arbitration documents that contain allegations of widespread misconduct by two former top Boston-based Merrill Lynch brokers. These allegations include excessive trading, unauthorized trading, overcharging commissions, failure to supervise and breach of fiduciary duty.
The arbitration documents show that initially, Merrill Lynch argued that Levine was a sophisticated investor who approved every trade. But following a 2018 hearing before a FINRA arbitration panel, the firm agreed to the settlement without admitting wrongdoing.
FINRA arbitration is not a public forum and is used as an alternative to litigation or mediation in order to resolve a dispute.
Benson has filed his own FINRA arbitration claim, which is pending, against Merrill Lynch, and two of the firm’s former brokers, Kenahan and Dermod Cavanaugh, alleging losses of more than $50 million and market-adjusted damages of over $100 million.
“We disagree with the claim that has been filed,” a spokesman for Merrill Lynch said in an emailed statement. “This is a case that doesn’t add up: a sophisticated, high net worth investor who claims to have been unaware of activity in their account for 11 years.”
The firm’s stance on Benson’s case is similar to the one it initially took in Levine’s case — that Benson was a sophisticated investor who approved every trade, which Benson denies.
“If I wanted to day-trade my own account, I would’ve done it myself. I didn’t need to pay $26 million to Merrill Lynch to do it,” Benson said.
Levine and Benson say they trusted their longtime friends to responsibly manage their wealth.
“He knew everything about Bob and my financial situation, where everything was, how it was set up, how we did the taxes,” Benson said referring to Cavanaugh.
They allege that their trust was grossly misplaced and say they have collectively lost around more than $200 million at the hands of Merrill Lynch and their advisors.
″\[My\] account was churned in large part for the benefit of generating commissions that benefited both Charles Kenahan, Derm Cavanaugh, but mostly Merrill Lynch,” Benson said.
Churning is an illegal practice in which a broker engages in excessive trading in a client’s account to generate commissions.
CNBC could not reach Levine for a comment. Repeated calls and emails to his attorney over several months were not returned.
**Cabletron Systems**
Levine and Benson are highly accomplished and successful businessmen. They built their wealth together, from the bottom up — something Levine calls in his arbitration filing the “quintessential American success story.”
In the early 1980s, the two friends co-founded their company, Cabletron Systems, out of Levine’s garage after discovering a niche market in the cable industry for companies that needed custom lengths of cable, delivered quickly.
“What started as something that we’d be able to save for, in my case, I wanted a refrigerator and a freezer, Bob wanted a little bit more than that. And we thought we’d sell a few things and be done. Turned out, it went to 7,000 employees and $1.6 billion in sales, and listed on the New York Stock Exchange,” Benson said.
Merrill Lynch was the underwriter for the company’s initial public offering in 1989.
In 1990, the cable and local area networking equipment manufacturer was named Fortune Magazine’s number one stock for return on investment. Cabletron’s stock price went from $16 to $23 per share that year, giving the company a market value of around $600 million. By 1997, when Levine stepped down as CEO, the company had grown to a $1.5 billion company, making Levine and Benson very rich, with millions to invest.
Both men acknowledge they are not experts on the market and that’s why they sought a financial advisor to manage their assets professionally. Levine says in his complaint he had little experience with finance or investments prior to the Cabletron IPO. Benson, who obtained his MBA from Syracuse University in 1979, says he knows balance sheets, income statements and cash flow but had never been a professional investor.
“I’m not a trader,” Benson said. “I’m not an investment professional, Merrill Lynch is, and that’s why I hired them.”
**Full trust in their brokers**
The two met Kenahan through Cavanaugh, Cabletron’s accountant in the years before the IPO. After leaving Cabletron, Cavanaugh began a career in the financial services industry, and in 1999 began working at a Boston-based branch of Morgan Stanley, according to his employment record on the FINRA site.
At Morgan Stanley, Cavanaugh partnered with Kenahan, an experienced financial advisor who was licensed in 1985. Kenahan, who is also an accomplished sailor and won the Swan 42 U.S. sailing championship in 2015, is described by Benson as “gregarious,” someone who “enjoyed the finer things.”
At the height of his career, Kenahan appeared to be the epitome of success. He was described by the Newport, Rhode Island, news site RhodyBeat.com as being the head of one of the country’s largest wealth management teams for Merrill Lynch. He was even asked to deliver the 2017 commencement speech at the prestigious Portsmouth Abbey School in Rhode Island, where his three sons graduated from in 2012.
“One of the reasons I’m so happy in life, and I truly am a happy guy, is that I do try to live my life with as much humility as I can,” Kenahan told the graduates.
“He seemed like a nice guy and he seemed like he knew what he was doing,” Benson said about his first impression of Kenahan.
Levine and Benson said they thought they had found a financial advisor they could trust and that Cavanaugh and Kenahan would act in their best financial interests. So, Levine and Benson decided to move their individual investment accounts to Morgan Stanley and into the care of the two men. According to arbitration documents, Benson’s accounts with Kenahan and Cavanaugh totaled approximately $200 million, while Levine’s accounts totaled around $180 million.
Kenahan told Levine the goal would be to keep his accounts safe, assured him that the accounts would never be exposed to a high concentration of a single stock, that his investments would be a mix of stock and bonds, and that his commissions would be lower than what he paid to his former financial advisors, according to Levine’s FINRA arbitration filing.
Similar assurances were made to Benson, according to his claim, which also says he made it clear to Kenahan and Cavanaugh that he wanted to avoid trading strategies that would result in short-term capital gains.
In late 2007, Kenahan and Cavanaugh had an offer to move to Merrill Lynch. In his arbitration claim, Levine says Kenahan “explained that in terms of the investments, everything would be the same and that Bob could expect the same low commissions.”
Benson said he remembers receiving an urgent call from Kenahan, who later came to Benson’s house with stacks of papers that needed to be signed in order to move his accounts from Morgan Stanley to Merrill Lynch.
“The pressure to do it was now,” Benson told CNBC, adding he was given little to no time to read and review the documents with counsel but signed them anyway because he trusted Kenahan. Ultimately, Levine and Benson moved their accounts, collectively worth hundreds of millions of dollars, to Merrill Lynch.
In his complaint, Benson says neither Kenahan nor Cavanaugh disclosed to him that the brokers’ compensation at Merrill Lynch included multi-million-dollar loans that wouldn’t have to be repaid if the brokers hit certain predetermined commission targets. Such loans, called “Promissory Notes” or “Employee Forgivable Loans,” are legal and are common practice on Wall Street.
However, what Benson alleges happened next is not legal. For the next decade, Benson says, Kenahan and Cavanaugh churned his account — excessively trading in his account in order to generate increased commissions.
**Forensic Account Analysis**
“Merrill Lynch made $26 million in fees to lose me $5 million,” Benson told CNBC. “But if I had put that money in a passbook savings account, let’s say, it would have been a $50 million gain.”
That analysis is based on a report compiled by Craig McCann, founder and principal of Securities Litigation and Consulting Group. McCann was hired to do a forensic audit on Benson’s investing accounts and was also an expert witness for Levine’s case.
“We sent the data to him and then he sends back a report,” Benson said. “It took me about two months to open the box, ’cause I didn’t want to admit that there was really a problem.”
However, once he reviewed the extensive report, Benson says he realized there was indeed a problem.
In his arbitration claim against Merrill Lynch, Benson says he sustained damages in excess of $50 million, including short-term equity trading losses of over $20 million and more than $15 million in excessive trading costs. McCann’s analysis found that if Benson’s money had simply been put into an S&P 500 index fund and left to grow, he would have earned more than $100 million.
“I think Merrill Lynch has to be held accountable for what they did,” Benson said.
Benson also alleges that Kenahan executed thousands of trades, most of which Benson says he knew nothing about, which resulted in tens of millions of dollars of additional losses. Among the trades he says he never authorized were small-cap stocks in China.
“I see a lot of trades and millions of shares, and things like Want Want China and Bank Mandiri,” Benson said.
The forensic analysis showed that the trades in Want Want China, a Shanghai based rice cracker and snack manufacturer, alone generated $1 million in commissions.
Benson acknowledges he did not always read his account statements.
“I get about 300 or 400 e-mails a day, and then multiple, many multiple phone calls a day. It’s just, it’s hard to keep up with all the paperwork that’s generated,” he said. But he maintains that he thought he could trust his brokers.
Levine also alleges his accounts were churned, saying in his filing that “the trading defies logic, except to the extent that it was obviously designed to further the interests of Kenahan and Merrill Lynch at \[his\] expense.”
**Levine’s record settlement**
It was Levine who first uncovered suspicious trading activity in his Merrill Lynch accounts after deciding to move the majority of his accounts back to Morgan Stanley, his claim details.
“I thought Charles had just done a poor job with my account, I had no idea I had been defrauded,” Levine said in the filing.
In late 2017, Benson says he received a call from Levine to tell him about the issues he discovered, and that there appeared to be evidence of improper activity and self-dealing.
“He said, ‘Charles is taking advantage of me. You better check your portfolio,’” Benson said.
Seeking to recoup some of his losses, Levine filed an arbitration claim with FINRA, the industry’s self-policing regulatory agency, against Merrill Lynch and Kenahan. The allegations include relentlessly churning his accounts for more than $26 million in commissions, fees, margin interest, concessions, mark-ups and marks-downs, as well as gambling more than $20 million of Levine’s money on a single penny stock, resulting in more than $16 million in losses on that stock.
“No one, not myself nor anyone that I knew, suspected Charles because everyone thought he was my friend and a caring investment advisor. He would only do the right thing for me, and I thought would be supervised by Merrill Lynch,” Levine said in his statement of claim.
“Kenahan had an absolute duty to refrain from excessive trading, charge reasonable commissions, to only recommend securities that were suitable, and to refrain from self-dealing,” Levine said in the FINRA arbitration filing. Adding that Kenahan “failed on all counts.”
Levine says the monetary damages he suffered at the hands of Kenahan and Merrill Lynch exceeded $100 million.
**Merrill Lynch fights the allegations**
Merrill Lynch aggressively fought the claims. In a brief obtained by CNBC, it said Levine’s case “fails as a matter of law,” and that the “astronomical monetary award” he sought had “no basis.” It referred to his statement of claim as a “fantasy, not reality.”
“As the panel will see, this entire case boils down to a false allegation: Bob Levine’s claim that he was deceived for more than a decade about the purchases and sales in his Merrill Lynch brokerage accounts,” the filing says.
Merrill Lynch added that “every legal theory in this case requires Claimants to prove that Merrill Lynch executed trades that Mr. Levine did not know about and did not want — and then lied to Mr. Levine about it. … There is no such evidence because that never happened.”
In 2019, the case eventually went to a final hearing in front of an arbitration panel, and despite the strongly worded assertions by the firm denying Levine’s allegations, Merrill Lynch decided to settle, before the arbitration panel announced its decision, for a record $40 million. The settlement is the largest single payout to an individual claimant in at least a decade, according to an analysis of FINRA’s BrokerCheck system data done by McCann’s Securities Litigation and Consulting Group.
Merrill Lynch fired Kenahan in July, following the final arbitration hearing, citing “customers’ allegations of unauthorized trading, unsuitable investment recommendations and excessive trading,” his BrokerCheck report shows. CNBC has learned that the firm is still paying for his legal defense.
Attorneys for Kenahan and Cavanaugh declined to comment for this story. However, Kenahan’s BrokerCheck report does include his comments on the matter. That section states that “the transactions giving rise to the customers’ allegations were executed at the customers’ direction. The allegations resulted in arbitrations and settlements. I was not a party to the arbitrations; I had no say in the firm’s decision to settle the claims; and I was not asked to make any payment as part of the settlements.”
**It can happen to anyone**
Benson says his story should be a cautionary tale for anyone who uses a financial advisor to oversee their wealth.
“If they can do it to me who has a big account and served as a governor of a state, who else can they do it to?” Benson told CNBC.
**If they can do it to me who has a big account and served as a governor of a state, who else can they do it to?**
**Craig Benson**
Louis Straney, who testified as an expert witness in Levine’s case and is a consultant for Benson, says the responsibility is supposed to go beyond the individual broker.
“It really is the firm’s job to supervise all of their associated persons,” said Straney, a managing partner at Arbitration Insight. “It is not the duties of the individual investor to supervise themselves.”
Levine also alleges that Kenahan, being a “huge producer” for Merrill Lynch, could have played a role in the firm turning a blind eye to his “profitable behavior.”
Merrill Lynch “had an absolute duty to supervise its registered representative, Charles Kenahan, and it utterly failed to do so,” Levine’s claim says.
For Benson, his case is scheduled to be heard by a FINRA arbitration panel located in New Hampshire in September.

Investment Advisor
[See Full Bio](https://independentadvisorsnw.com/author/investment-advisor/) [ ](https://independentadvisorsnw.com/author/investment-advisor/)
**Categories:** All Posts
---
### [How to find a financial advisor who won't make your money disappear?](https://independentadvisorsnw.com/how-to-find-a-financial-advisor-who-wont-make-your-money-disappear/)
**Published:** February 10, 2020
**Author:** Investment Advisor
**Content:**
This horrific story and others like it are the reasons I got into this business twenty years ago. This kind of thing was happening then, and it’s still happening now. Regulators have enacted new laws and fiduciary rules, but in essence, all they mean/require is more disclosure. Rules and rotten advisors are difficult to enforce and monitor. The best advice I can give to investors is to [choose your advisor](https://iiaproduction.wpengine.com/homepage/investor-education-center/how-to-choose-a-financial-advisor/) carefully and make the relationship personal. Please get to know them, their families, and their values. Investors have to understand how their advisor is getting compensated and who is the custodian of their assets.
Original CNBC Article:
## How to find a financial advisor who won’t make your money disappear?
Scott Cohn | @ScottCohnTV 10:01 AM ET Fri, 7 Feb 2020
Of all the professionals we entrust with various aspects of our lives, few hold more sway than a financial advisor. A good one can show you how to turn your hard-earned cash into a secure financial future.
“Buying a house, graduating from college, seeking retirement, supporting individuals that may be dependents of yours. There’s so many reasons why someone needs to have a better understanding of their financial future,” Fordham University accounting professor Barbara Porco told CNBC’s “American Greed.”
But then there are advisors like Dawn Bennett.
A radio show host who was listed by Barron’s as one of the nation’s top financial advisors, Bennett, 57, was in fact running a massive Ponzi scheme. Prosecutors said that rather than investing her clients’ money as she claimed, she spent much of it on her outrageously lavish lifestyle including clothes, shoes, and a $500,000-a-year luxury suite at AT&T Stadium, home of the Dallas Cowboys. She also persuaded clients to invest millions in her online luxury sporting-goods business, which ended up being a spectacular flop.
It turned out that she earned the coveted Barron’s rankings — not to mention millions of dollars in credit lines — by vastly overstating her finances. At least 46 people invested some $20 million, and Bennett lost or spent almost all of it.
“This was money that these folks had set aside for ailing family members, for their own long-term care, for their grandchildren’s education, so that they could retire and so that they wouldn’t have to return to the workplace,” Assistant U.S. Attorney Erin Pulice told “American Greed.” “So, the loss of these funds was just absolutely devastating.”
Bennett even spent some of her money on religious ceremonies and other rituals including something called a “beef tongue shut-up hoodoo spell,” which, as the name implies, employed a beef tongue, various spices and incantations apparently aimed at getting investigators to hold their tongues and stay silent. The spells did not work.
A jury convicted her in 2018 on 17 counts. including fraud, conspiracy and making false statements. She is serving a 20-year prison sentence while she appeals the verdict. A judge ordered her to pay $14.5 million in restitution to her victims.
“I would love to see Dawn Bennett face to face again in jail,” said author and relationship expert Steve Santagati, who lost more than $1 million. “I want to look her in the eyes as a victim of her theft and just be able to say, ‘I know. We all know who you are now.'”
### Choose wisely
To avoid your own Dawn Bennett-style nightmare, Porco said investors should put prospective financial advisors to the test. Even though you want an advisor who will be able to answer all your financial questions, start by asking questions you know the answers to.
“Ask them what the difference between nonqualified dividends and qualified dividends are. Ask them the tax difference,” Porco said. “If they give you the correct one, that’ll make you feel good, but if they don’t, I think you need to rethink your financial advisor.”
(For the record, a qualified dividend is one that is paid by a U.S. corporation or a foreign corporation that has a tax treaty with the United States. Qualified dividends are taxed at the same, lower rate as capital gains. Other dividends are nonqualified and are taxed as ordinary income.)
Be sure to look into your advisor’s past. The Financial Industry Regulatory Authority offers an online tool to check a professional’s disciplinary record, including customer complaints. FINRA’s system is not foolproof, but it can help weed out advisors with checkered backgrounds.
If the advisor passes those tests, it is time for some bigger questions. One of those involves how your advisor will be paid. If you are a novice with only a small amount of money to invest, you might be able to find an advisor who will take you on at no charge with the idea that you will become a paying customer later.
Otherwise, Porco suggested finding an advisor who will charge a flat fee based on their time, or on the amount of money in your portfolio.
“One percent would probably be appropriate,” she said.
Beware of fee structures that sound too good or do not align with the market.
“You want to make sure that the fee structure is appropriate and the person that you’re working with doesn’t start using language like, ‘You’re very special to me,’ or ‘I have an exclusive deal that I think is just perfect for you,’ or if there’s an air of secrecy about the investment strategy, those kinds of things might be very uncomfortable,” Porco said.
### Loyalty test
You have the right to know how your advisor is compensated. Some financial advisors receive a portion of their compensation through commissions, and while there is nothing inherently wrong with that, it could be an incentive for them to excessively trade your account or steer you toward financial products that may not be the best for your situation.
To make certain your advisor’s loyalties are not misplaced, look for someone who is registered. Look for the designation RIA (Registered Investment Advisor) or CFP (Certified Financial Planner). The idea is to find an advisor who will act as your fiduciary.
“When you have fiduciary responsibility, what you’re saying is that, ‘I’m going to put your interests above mine, above my firm’s, above the companies that I’m interested in investing in. Your interest is paramount in the decisions that we will make together’,” Porco said.
The Securities and Exchange Commission requires most financial advisors to operate under the fiduciary standard, but there are exceptions. Certain advisors — including those employed by broker-dealers — can operate under the less rigorous “suitability standard,” which requires them to make recommendations that are appropriate for your financial situation. Make certain you understand which standard your advisor follows.
The idea is to sniff out any conflicts that might separate your advisor’s interests from your own.
“In order to guard against a conflict of interest, you need to know about it,” Porc saod. “So I often recommend to people to keep a certain skepticism when you meet individuals when you’re trying to vet your financial advisor.”
In Bennett’s case, some of the conflicts were blatant, including selling her clients promissory notes tied to her online luxury apparel business.
“She was encouraging individuals that were investing with her in the financial markets and in funds, taking money out of those investments and taking that portfolio fund and moving it into her personal investment,” Porco said.
### On guard
Once you have chosen an advisor, your work has only just begun. Keep tabs on your investments’ performance. Read your account statements. Ask questions about the recommendations your advisor makes.
“If your financial advisor is continually encouraging to reinvest or discouraging to withdraw from money that would give me a pause, because with Dawn Bennett, ultimately what she was doing is conducting a gigantic Ponzi scheme,” Porco said. “So, if your financial advisor continually discourages you from removing any of your own cash, pause and think about why, and if they can’t give you a good answer, find someone else.”
See how Dawn Bennett worked her magic on dozens of investors, making $20 million disappear. And learn how a “beef tongue shut-up hoodoo spell” is supposed to work. Watch an ALL NEW episode of “American Greed,” Monday, Feb. 10, at 10pm ET/PT only on CNBC.

Investment Advisor
[See Full Bio](https://independentadvisorsnw.com/author/investment-advisor/) [ ](https://independentadvisorsnw.com/author/investment-advisor/)
**Categories:** All Posts
---
### [How does an individual's risk tolerance influence their tax-efficient retirement and investment decisions?](https://independentadvisorsnw.com/how-does-an-individuals-risk-tolerance-influence-their-tax-efficient-retirement-and-investment-decisions/)
**Published:** January 31, 2024
**Author:** Financial Planner
**Excerpt:** An individual's risk tolerance plays a significant role in shaping their tax-efficient retirement and investment decisions. Risk tolerance reflects an individual's willingness and ability to endure fluctuations in the value of their investments.
**Content:**
An individual’s risk tolerance plays a significant role in shaping their tax-efficient retirement and investment decisions. Risk tolerance reflects an individual’s willingness and ability to endure fluctuations in the value of their investments. It influences various aspects of financial planning, including the selection of investment vehicles, asset allocation, and the overall approach to tax-efficient strategies. Here’s how risk tolerance intersects with tax-efficient decisions:
1\. Asset Allocation:
Low Risk Tolerance:
Individuals with a low risk tolerance may favor more conservative asset allocations, such as a higher proportion of fixed-income investments like bonds. These investments often generate interest income, which is taxed at ordinary income rates. To enhance tax efficiency, individuals with low risk tolerance may consider holding these interest-bearing assets in tax-advantaged accounts.
High Risk Tolerance:
Those with a higher risk tolerance may be comfortable with a more aggressive allocation, such as a higher percentage of equities. Equities, especially if held for the long term, can benefit from lower capital gains tax rates. Tax-efficient strategies for individuals with higher risk tolerance might involve focusing on tax-efficient equity investments and optimizing the timing of capital gains realization.
2\. Tax-Efficient Investments:
Low Risk Tolerance:
Individuals with lower risk tolerance might prioritize investments with more stable returns and potentially lower volatility, even if those investments are less tax-efficient. They may lean towards tax-advantaged options like municipal bonds or tax-deferred annuities, accepting a potentially lower return in exchange for reduced risk.
High Risk Tolerance:
Those with a higher risk tolerance may be more willing to invest in tax-efficient but potentially more volatile assets, such as tax-managed funds or growth-oriented stocks. They may prioritize investments that have the potential for capital gains and are mindful of the tax implications when managing their portfolio.
3\. Tax-Efficient Strategies:
Low Risk Tolerance:
Conservative investors with lower risk tolerance may prioritize strategies that minimize tax liability and provide a more predictable income stream in retirement. This might involve a focus on tax-deferred or tax-exempt investments and a more conservative withdrawal strategy.
High Risk Tolerance:
More risk-tolerant individuals may be open to tax-efficient strategies that involve active management of their portfolio, such as tax-loss harvesting, asset location optimization, and strategic Roth conversions. They may be more comfortable with the potential variability in returns associated with these strategies.
4\. Long-Term Perspective:
Low Risk Tolerance:
Individuals with a lower risk tolerance may have a shorter investment horizon and prioritize capital preservation. Their tax-efficient strategies might involve planning for a more predictable income stream in retirement and a focus on minimizing immediate tax liabilities.
High Risk Tolerance:
Those with a higher risk tolerance often have a longer-term perspective and may be more inclined to take advantage of tax-efficient strategies that involve holding investments for an extended period. They may prioritize growth and tax-deferred compounding over the short-term tax implications.
5\. Withdrawal Strategies in Retirement:
Low Risk Tolerance:
Conservative investors may prefer a more stable income stream in retirement, possibly relying more on income generated by interest-bearing investments. Withdrawal strategies may be designed to minimize the impact of market volatility and unexpected expenses.
High Risk Tolerance:
More aggressive investors may be willing to accept greater variability in retirement income, potentially relying on a combination of interest, dividends, and capital gains. Withdrawal strategies might involve a more flexible approach, [adjusting based on market conditions and tax](https://independentadvisorsnw.com/?p=2801) considerations.
In summary, an individual’s risk tolerance is a key determinant of their investment preferences and choices. It influences the trade-offs between risk and return and shapes the overall approach to tax-efficient retirement and investment planning. Tailoring strategies to align with an individual’s risk tolerance helps ensure that the chosen investment and tax planning approach is consistent with their financial goals and psychological comfort level.

Financial Planner
[See Full Bio](https://independentadvisorsnw.com/author/financial-planner/) [ ](https://independentadvisorsnw.com/author/financial-planner/)
**Categories:** All Posts, Financial Planning, Investment Advisor
---
### [Tax Law Shifts: Adapt Your Retirement & Investment Plan](https://independentadvisorsnw.com/advisor-qa-how-do-you-help-your-clients-adjust-their-retirement-and-investment-strategies-in-response-to-evolving-tax-laws/)
**Published:** February 8, 2024
**Author:** Investment Advisor
**Excerpt:** I can offer general guidance on how individuals might adjust their retirement and investment strategies in response to evolving tax laws. Keep in mind that this information is not a substitute for professional financial advice.
**Content:**
I can offer general guidance on how individuals might adjust their retirement and investment strategies in response to evolving tax laws. Keep in mind that this information is not a substitute for professional financial advice, and individuals should consult with a qualified financial advisor to address their specific circumstances. Here are some general steps:
1\. Stay Informed:
Regularly stay informed about changes in tax laws. This involves monitoring updates from relevant government agencies, financial news sources, and industry publications. Tax laws can impact various aspects of [retirement and investment planning,](https://independentadvisorsnw.com/advisor-qa-how-to-guide-to-tax-optimized-investing-examples-of-strategies-that-combine-tax-efficiency-with-effective-retirement-planning/) so being aware of changes is crucial.
2\. Assess Impact on Current Strategy:
Evaluate how changes in tax laws may impact your current retirement and investment strategy. Consider how alterations in tax rates, contribution limits, or other rules could affect your overall financial plan.
3\. Review Investment Portfolio:
Assess your investment portfolio in light of potential tax law changes. Consider the [tax implications of each investment,](https://independentadvisorsnw.com/advisor-qa-how-to-guide-to-tax-optimized-investing-tax-deductions-and-incentives/) including capital gains, dividends, and interest income. Adjust the portfolio composition if needed to optimize for tax efficiency.
4\. Revisit Retirement Contributions:
Reevaluate your retirement contributions in response to changes in contribution limits or tax-deductibility rules. Adjust your contributions to retirement accounts based on the updated regulations to maximize tax benefits.
5\. Explore New Tax-Advantaged Options:
Explore new tax-advantaged retirement options that may become available due to changes in tax laws. For example, new legislation might introduce different types of accounts or modify existing ones, providing additional opportunities for tax-efficient savings.
6\. Adjust Tax Strategies:
Adjust tax strategies based on changes in laws. For instance, changes in tax rates might influence the timing of capital gains realizations or Roth conversions. Adapt your strategy to optimize for the current tax environment.
7\. Consider Estate Planning Implications:
Review your estate planning [strategies in response to any changes in estate tax](https://independentadvisorsnw.com/homepage/education/tax-optimization-strategies-for-high-earners/) laws. Adjust plans for wealth transfer, gifting, and inheritance based on the latest regulations.
8\. Consult with Financial Professionals:
Seek guidance from financial professionals, including financial advisors, tax professionals, and estate planning experts. Professionals can provide insights tailored to your specific situation and help you navigate the complexities of evolving tax laws.
9\. Regularly Review and Adjust:
Establish a routine for regularly reviewing and adjusting your retirement and investment strategies. Tax laws, as well as personal circumstances, can change over time, and regular reviews ensure that your financial plan remains aligned with your goals.
10\. Stay Proactive:
Be proactive in responding to tax law changes. Waiting until the last minute to make adjustments may limit your options. Staying proactive allows you to make well-informed decisions that align with your financial objectives.
It’s important to note that tax planning is complex, and the impact of changes in tax laws can vary based on individual circumstances. Consulting with professionals who have expertise in tax planning and financial management is crucial to making informed decisions.

Investment Advisor
[See Full Bio](https://independentadvisorsnw.com/author/investment-advisor/) [ ](https://independentadvisorsnw.com/author/investment-advisor/)
**Categories:** All Posts, Financial Planning, Investment Advisor
---
### [Goran Ognjenovic on Mastering Wealth: A CEO Weekly Feature](https://independentadvisorsnw.com/goran-ognjenovic-featured-in-a-ceo-weekly-article-mastering-wealth-with-ognjenovics-strategic-insights-sep-9th-2024/)
**Published:** September 18, 2024
**Author:** Investment Advisor
**Content:**
Independent Investment Advisors has made a name for itself with its holistic and tailored approach to serving high-net-worth individuals and families. Ognjenovic’s visionary leadership and dedication have set a new benchmark in the industry.
# A Financial Visionary’s Journey
Goran Ognjenovic began his career in 2003 as an independent investor. His deep understanding of the markets and investment strategies led him to establish Independent Investment Advisors. Today, he leads a team of experts dedicated to helping clients achieve financial freedom. “Seeing my clients transition from anxiety to enjoyment in their lives is incredibly inspiring,” Ognjenovic reflects.
# Comprehensive Wealth Management
What sets Independent Investment Advisors apart is its all-encompassing approach to wealth management. The firm offers a wide range of services, including financial planning, retirement planning, [tax planning, investment management, risk management, and estate planning](https://independentadvisorsnw.com/advisor-qa-how-to-guide-to-tax-optimized-investing-examples-of-strategies-that-combine-tax-efficiency-with-effective-retirement-planning/). This integrated strategy ensures that all aspects of a client’s financial life are seamlessly coordinated. “We work with a limited number of clients, which allows us to build deeper relationships and provide custom financial plans tailored to each individual’s needs,” Ognjenovic explains.
# Philosophy of Incremental Improvement
A cornerstone of Ognjenovic’s success is his philosophy of “continuous incremental improvement.” This principle focuses on making small, manageable changes that lead to significant progress over time. “I’ve been teaching my kids this concept—whether in work or sports, success requires hard work, dedication, and perseverance. By focusing on small, daily improvements, we can achieve remarkable results over time,” he shares.
# Adapting to Financial Changes
In a world of constant financial flux, staying ahead is crucial. Independent Investment Advisors is committed to helping clients navigate these changes, particularly with upcoming tax code alterations due to the sunset of the Tax Cuts and Jobs Act (TCJA) in 2025. The firm provides expert tax planning to ensure clients are prepared for the reversion of tax rates and standard deductions.
# Practical and Personalized Approach
Independent Investment Advisors prides itself on its practical approach to wealth management. Ognjenovic emphasizes that their strategies are straightforward and free from unnecessary jargon. “Our approach to business and wealth management is very practical and not academic. We don’t generally use big words or elaborate theories,” he says. This clarity and simplicity have resonated with clients, fostering trust and long-term relationships.
# Looking Ahead
Independent Investment Advisors are expanding their multifamily wealth management office, reflecting ongoing growth in this sector. Their short-term and long-term goals focus on providing the financial and wealth advice possible while staying adaptive to the ever-evolving financial landscape. “Financial markets and tax rules are always in flux. Our ongoing mission is to stay on top of those changes and help our clients adapt,” Ognjenovic states.
For more information on Independent Investment Advisors, visit their [website](http://independentadvisorsnw.com/).
*Disclaimer: ”This content is for informational purposes only and is not intended as financial advice, nor does it replace professional financial advice, investment advice, or any other type of advice.* *You should seek the advice of a qualified financial advisor or other professional before making any financial decisions.”*

Investment Advisor
[See Full Bio](https://independentadvisorsnw.com/author/investment-advisor/) [ ](https://independentadvisorsnw.com/author/investment-advisor/)
**Categories:** Featured Article
---
### [Forbes Spotlight: Goran Ognjenovic on Inspiring Customer-Success Strategies](https://independentadvisorsnw.com/goran-ognjenovic-featured-in-a-forbes-article-3-strategies-for-small-businesses-to-remain-customer-centric-may-15th-2024/)
**Published:** May 15, 2024
**Author:** Investment Advisor
**Content:**
by[ Jia Rizvi ](https://www.forbes.com/sites/jiawertz/)Contributor
Whether your business is in finance, manufacturing, lifestyle, travel, or something else, you have one primary focus and responsibility – keeping your clients happy. At least, that’s how it should be. However, as we’ve seen, many business leaders forget their clients are their company’s foundation and instead focus on lining their pockets and keeping their investors happy.
How a company treats its clients is a top concern for customers, with 94% of people saying it’s the top thing they consider when deciding whether to do business with someone, according to recent research by Small Business. That’s why it’s essential to keep clients at the center of your business, no matter how large you grow.
## Understanding Customer And Client Centricity In A Business
Customer-centricity involves more than providing excellent customer service – although that is certainly crucial. It means putting your client’s needs and experiences at the heart of your business strategy, influencing everything from product development and design to sales processes. “A customer-centric approach doesn’t view customers just as revenue sources but as central stakeholders in the business’s ecosystem,” explains Goran Ognjenovic, Founder and principal of Independent Investment Advisors. “The key to our success and the industry’s future is our ability to offer a wide range of services all under one roof. This approach allows us to develop deep, long-term relationships with our clients, understanding their unique needs and goals and providing tailored solutions that address every aspect of their financial lives.”
A customer-centric approach contributes to higher client satisfaction and a deep understanding of client’s needs and wants. By aligning your services with your client’s needs and expectations, you can enhance your relevance in the market and sharpen your competitive edge. This approach helps retain clients and attracts new ones through positive word-of-mouth and client referrals.
In an age where reviews and social media are increasing, positive customer experiences are more important than ever. Adopting a customer-centric approach significantly enhances client satisfaction and retention – critical in an industry where retaining customers can be up to five times cheaper than acquiring new ones. “By focusing on keeping our current clients happy for the long-term, we can build relationships that help us secure a stable revenue stream,” says Ognjenovic.
## How To Become A Customer-Centric Organization
If you have felt your priorities straying from your clients, it’s time to get back on track. Here are a few strategies to adopt.
### 1. Stay On Top Of The Market And Respond To Changes Quickly
Staying customer-centric requires aligning business strategies with customer needs, all while keeping a close eye on shifting market changes and acting fast when they occur.
“Nearly 70% of consumers told us that behaving inconsistently is human and acceptable. However, consumers are also saying that businesses need to keep up. Around two-thirds of customers feel that companies are not responding fast enough to their changing needs,” said David Droga and Baiju Shah for The Harvard Business Review.
It’s critical to stay on top of customer’s needs, as 61% of small businesses say that more than half of their revenue comes from repeat customers, according to BIA Advisory Services.
### 2. Monitor Your Online Reputation
Deloitte found that 81% of people read reviews and check online ratings before doing business with a brand, highlighting the need for companies to keep up with their online reputation. “Empowered by access to information, social networks, and digital devices, consumers are now well equipped to do research and receive satisfaction for most of their needs. As a result, consumers have come to expect more, making it harder for businesses to keep up,” reports Deloitte. It’s important to respond to reviews, even negative ones, and do your best to make things right.
### 3. Embrace Your Small Business’s Natural Agility
Thanks to their built-in agility, small businesses can keep a pulse on what their clients want through a more personal connection with the consumer. “As an independent firm, we have the flexibility to adapt to market changes quickly, ensuring that our clients’ interests are always at the forefront of our decision-making process,” adds Ognjenovic.
Keeping clients at the center of your small business is not optional for small businesses – it’s a necessity. By adopting a genuinely customer-focused approach, small businesses can enhance their competitiveness, foster customer loyalty, and drive sustainable growth. Remember, in a world where your competitors are just a click away, how you treat your customers can make all the difference.

Investment Advisor
[See Full Bio](https://independentadvisorsnw.com/author/investment-advisor/) [ ](https://independentadvisorsnw.com/author/investment-advisor/)
**Categories:** Featured Article
---
### [No Man Ever Steps in the Same River Twice: The Danger of "The Market Always Does" Thinking](https://independentadvisorsnw.com/no-man-ever-steps-in-the-same-river-twice/)
**Published:** September 17, 2019
**Author:** Portfolio Manager
**Content:**
**“No man ever steps in the same river twice, for it’s not the same river and he’s not the same man.” — Heraclitus**
I heard this from an active trader friend of mine the other day. It couldn’t be any more accurate when it comes to working in the capital markets. No two days are alike. Just because something happened before doesn’t mean it will happen again. This, in my opinion, is one of the biggest reasons individual and retail investors struggle. Professional traders and investors have to wake up every morning, look around, and make decisions based on what is taking place around the world in real-time. They must be nimble and ready to change their investment thesis and plans on a moment’s notice.
### The Market is Always Changing
One of the most dangerous assumptions in investing is the idea that “the market always does” something. Investors often rely on historical patterns, expecting markets to behave in predictable ways. Phrases like “the market always recovers,” “tech stocks always lead growth,” or “small caps always outperform in a recovery” can create a false sense of certainty and lead to poor decision-making. While long-term trends exist, the market is dynamic, and its composition and drivers of return shift over time.
### How Market Composition Has Changed Over the Last 15 Years
A look at the S&P 500, Nasdaq 100, and Russell 2000 over the past 15 years illustrates how markets evolve, often in ways investors might not anticipate.
#### **S&P 500: A Shift to Mega-Cap Dominance**
Fifteen years ago, the S&P 500 was more diversified across sectors, with a balance between technology, financials, energy, and consumer companies. Since then, technology and communication services have dramatically increased their share of the index’s market capitalization. Today, a handful of mega-cap technology companies—such as Apple, Microsoft, and Alphabet—dominate, making the index more concentrated than ever. This shift means that the drivers of S&P 500 performance are vastly different from those of the past, making historical comparisons less reliable.
#### **Nasdaq 100: From Tech-Led Growth to AI and Beyond**
The Nasdaq 100 has always been tech-heavy, but even within the technology sector, the key players and themes have changed. A decade ago, semiconductor stocks and hardware manufacturers played a central role. Today, artificial intelligence, cloud computing, and software-driven businesses drive Nasdaq’s performance. Additionally, some of yesterday’s high-flyers, such as traditional social media firms, are no longer the growth engines they once were. This evolution underscores the risk of assuming that past Nasdaq leadership will dictate future performance.
#### **Russell 2000: Small Caps Aren’t What They Used to Be**
Investors often believe that small-cap stocks, represented by the Russell 2000, will always outperform after economic downturns. While this was historically true in certain cycles, the index has struggled to keep pace with larger counterparts in recent years. Rising interest rates, changes in credit availability, and sector composition shifts have made small caps more vulnerable than in the past. Furthermore, many of the fastest-growing companies today, particularly in technology, are staying private longer, delaying their entry into the public small-cap space.
### **What This Means for Investors**
Investors must resist the urge to rely on outdated narratives. Markets evolve, and historical performance patterns may no longer hold. Instead of relying on broad assumptions, investors should focus on:
- Understanding the current market structure and sector trends.
- Evaluating macroeconomic factors that could drive changes.
- Building a diversified portfolio that adapts to changing market conditions rather than assuming past trends will repeat.
### **Final Thoughts**
The market is never static. The belief that “the market always does” something may lead to false confidence and misinformed strategies. Instead, investors should approach markets with flexibility, recognizing that past performance does not guarantee future results. A thoughtful, research-driven approach—rather than reliance on outdated narratives—will always serve investors better in the long run.

Portfolio Manager
[See Full Bio](https://independentadvisorsnw.com/author/portfolio-manager/) [ ](https://independentadvisorsnw.com/author/portfolio-manager/)
**Categories:** All Posts
---
### [What advice would you give to someone seeking to minimize taxes while maximizing retirement and investment savings?](https://independentadvisorsnw.com/what-advice-would-you-give-to-someone-seeking-to-minimize-taxes-while-maximizing-retirement-and-investment-savings/)
**Published:** January 28, 2024
**Author:** Financial Planner
**Excerpt:** Minimizing taxes while maximizing retirement and investment savings requires a thoughtful and strategic approach to financial planning. Here are several pieces of advice to help individuals achieve this goal.
**Content:**
Minimizing taxes while maximizing retirement and investment savings requires a thoughtful and strategic approach to financial planning. Here are several pieces of advice to help individuals achieve this goal:
1\. Diversify Tax-Efficiently:
Diversify your investments across various asset classes, and strategically allocate them to taxable and tax-advantaged accounts. Place tax-inefficient assets in tax-advantaged accounts to minimize the immediate tax impact.
2\. Contribute to Tax-Advantaged Accounts:
Maximize contributions to tax-advantaged retirement accounts, such as 401(k)s, IRAs, and HSAs. These accounts offer tax benefits, including tax deductions on contributions or tax-free withdrawals in retirement.
3\. Consider Roth Contributions:
Consider making contributions to Roth IRAs or Roth 401(k)s, especially if you anticipate being in a higher [tax bracket in retirement](https://independentadvisorsnw.com/?p=2801). While contributions are not tax-deductible, qualified withdrawals are tax-free.
4\. Tax-Loss Harvesting:
Regularly review your investment portfolio and strategically sell investments with losses to offset capital gains. Tax-loss harvesting can help minimize your overall tax liability.
5\. Optimize Withdrawal Strategies:
During retirement, plan your withdrawals strategically to minimize taxes. Consider the tax implications of withdrawing from taxable, tax-deferred, and tax-exempt accounts. This flexibility can help manage your tax bracket in retirement.
6\. Take Advantage of Tax Credits:
Explore and take advantage of available tax credits, such as the Saver’s Credit for retirement contributions. Tax credits directly reduce your tax liability and can enhance your overall savings.
7\. Employer Matches and Contributions:
Contribute enough to employer-sponsored retirement plans to take full advantage of any employer matches. Employer contributions can significantly boost your retirement savings.
8\. Health Savings Accounts (HSAs):
Contribute to HSAs if eligible. HSAs offer triple tax advantages—contributions are tax-deductible, earnings grow tax-free, and qualified withdrawals for medical expenses are tax-free.
9\. Stay Informed About Tax Laws:
Stay informed about changes in tax laws and regulations. Tax laws can impact your financial strategy, so staying up-to-date ensures that you can adapt your plan accordingly.
Remember, individual financial situations vary, and the effectiveness of tax strategies depends on personal circumstances and goals. Seeking advice from financial professionals can provide valuable insights tailored to your specific needs. Additionally, be proactive in staying informed about changes in tax laws and regularly reassess your financial plan to ensure it remains aligned with your objectives.

Financial Planner
[See Full Bio](https://independentadvisorsnw.com/author/financial-planner/) [ ](https://independentadvisorsnw.com/author/financial-planner/)
**Categories:** All Posts, Financial Planning, Investment Advisor
---
### [What are the enduring benefits of incorporating tax-efficient methods in retirement and investment portfolios?](https://independentadvisorsnw.com/what-are-the-enduring-benefits-of-incorporating-tax-efficient-methods-in-retirement-and-investment-portfolios/)
**Published:** January 26, 2024
**Author:** Investment Advisor
**Excerpt:** Incorporating tax-efficient methods in retirement and investment portfolios can offer enduring benefits that positively impact an individual's financial well-being over the long term.
**Content:**
Incorporating tax-efficient methods in retirement and investment portfolios can offer enduring benefits that positively impact an individual’s financial well-being over the long term. Here are some of the key enduring benefits:
1\. Wealth Preservation:
Tax-efficient strategies help minimize unnecessary tax liabilities, preserving more of an individual’s wealth for future use. By optimizing tax outcomes, investors can potentially accumulate more wealth over time.
2\. Maximized Returns:
Minimizing taxes on investment gains allows for the compounding of returns on a larger investment base. Over the long term, this can lead to significantly higher overall returns compared to portfolios with less tax-efficient strategies.
3\. Flexibility in Withdrawal Strategies:
Tax-efficient planning provides flexibility in retirement withdrawals. By strategically choosing the source of withdrawals (taxable, tax-deferred, or tax-free accounts), retirees can manage their income to minimize tax liability in different years.
4\. Reduced Tax Drag:
Tax drag, the impact of taxes on investment returns, can be reduced through tax-efficient methods. By minimizing the impact of taxes on returns, investors keep more of their earnings working for them.
5\. Optimized Asset Location:
Placing tax-inefficient assets in tax-advantaged accounts and tax-efficient assets in taxable accounts helps optimize the after-tax returns of the overall portfolio. This strategic asset location can enhance the portfolio’s overall tax efficiency.
6\. Lower Effective Tax Rates in Retirement:
Planning for lower effective tax rates in retirement can result in significant savings. Tax-efficient methods help retirees manage their income in a way that minimizes tax liability during retirement years.
7\. Estate Planning Advantages:
Tax-efficient strategies can extend to estate planning, providing advantages for transferring wealth to heirs. Strategies such as the stepped-up cost basis for inherited assets can result in lower capital gains taxes for heirs.
8\. Improved Risk Management:
Diversification and tax-efficient asset location contribute to improved risk management. By spreading investments across different asset classes and optimizing their tax treatment, investors can mitigate risks associated with market volatility and taxation.
9\. Enhanced Retirement Income:
Tax-efficient planning allows retirees to generate more after-tax income from their retirement savings. This can lead to a more comfortable and sustainable lifestyle in retirement.
10\. Adaptability to Tax Law Changes:
Tax-efficient strategies are adaptable to changes in tax laws. Regular reviews and adjustments to the financial plan can ensure that strategies remain aligned with the current tax landscape.
11\. Lower Transaction Costs:
By minimizing the need for frequent buying and selling of assets, tax-efficient strategies can help reduce transaction costs associated with trading, further preserving an investor’s wealth.
12\. Potential Behavioral Benefits:
Tax-efficient strategies often involve a long-term perspective and discipline, which can help investors avoid impulsive decisions driven by short-term market fluctuations or tax considerations.
The enduring benefits of tax-efficient methods underscore the importance of thoughtful planning and strategic decision-making throughout an individual’s financial journey. Consulting with financial professionals, including tax advisors and investment experts, can help individuals tailor their strategies to optimize tax outcomes and achieve their long-term financial goals.

Investment Advisor
[See Full Bio](https://independentadvisorsnw.com/author/investment-advisor/) [ ](https://independentadvisorsnw.com/author/investment-advisor/)
**Categories:** All Posts, Financial Planning, Investment Advisor
---
### [Advisor Q&A: How to guide to tax optimized investing. Understand tax-advantaged retirement accounts.](https://independentadvisorsnw.com/advisor-qa-how-to-guide-to-tax-optimized-investing-understand-tax-advantaged-retirement-accounts/)
**Published:** January 17, 2024
**Author:** Investment Advisor
**Excerpt:** Understanding tax-advantaged retirement accounts is crucial for individuals and businesses planning for retirement. These accounts offer various tax benefits and incentives to encourage saving for the future. Here's essential information that individuals and businesses should know about tax-advantaged retirement accounts:
**Content:**
**What essential information should individuals and businesses understand about tax-advantaged retirement accounts?**
Understanding tax-advantaged retirement accounts is crucial for individuals and businesses planning for retirement. These accounts offer various tax benefits and incentives to encourage saving for the future. Here’s essential information that individuals and businesses should know about tax-advantaged retirement accounts:
For Individuals:
Types of Tax-Advantaged Retirement Accounts:
Common individual retirement accounts include Traditional IRAs, Roth IRAs, 401(k) plans, 403(b) plans, and Simplified Employee Pension (SEP) IRAs. Each has unique features, contribution limits, and tax implications.
Contributions and Limits:
Contribution limits vary by account type. For example, in 2023, individuals can contribute up to $6,000 to IRAs (or $7,000 if aged 50 or older) and up to $20,500 to 401(k) plans. Contribution limits are subject to periodic adjustments.
Tax Treatment of Contributions:
Contributions to Traditional IRAs and 401(k) plans are typically tax-deductible, providing an immediate tax benefit. Roth IRA contributions are made with after-tax dollars, but qualified withdrawals are tax-free.
Tax-Deferred Growth:
Earnings on investments within tax-advantaged retirement accounts grow tax-deferred. This means that capital gains, dividends, and interest are not taxed annually, allowing for potential compounding growth.
Required Minimum Distributions (RMDs):
Traditional IRAs and 401(k) plans require individuals to start taking minimum distributions after reaching a certain age (currently 72, but it was 70½ for those born before July 1, 1949). Roth IRAs do not have RMDs during the original account owner’s lifetime.
Early Withdrawal Penalties:
Early withdrawals (before age 59½) from Traditional IRAs and 401(k) plans may be subject to a 10% penalty, in addition to regular income tax. Roth IRA contributions can be withdrawn at any time without penalty, but earnings may be subject to penalties if withdrawn early.
Employer-Sponsored Plans:
Employer-sponsored retirement plans, such as 401(k)s, often offer employer matches, providing an additional incentive for employees to contribute. Individuals should take advantage of employer matches to maximize their retirement savings.
For Businesses:
Types of Employer-Sponsored Plans:
Businesses can offer various retirement plans, including 401(k) plans, SIMPLE IRAs, SEP IRAs, and profit-sharing plans. The choice of plan depends on factors like the size of the business, employee participation, and employer contributions.
Employer Contributions:
Many employer-sponsored plans allow for employer contributions, including matching contributions to employee contributions. These contributions can be tax-deductible for the business and serve as an employee retention and benefits tool.
Automatic Enrollment and Escalation:
Some employer plans offer automatic enrollment, encouraging employee participation. Automatic escalation features can gradually increase employee contributions over time.
Fiduciary Responsibilities:
Employers have fiduciary responsibilities when managing retirement plans. This includes selecting and monitoring investment options, providing disclosures to participants, and acting in the best interests of plan participants.
Tax Credits for Small Businesses:
Small businesses may be eligible for tax credits, such as the Small Employer Pension Plan Startup Cost Credit, which helps offset the costs of establishing a retirement plan.
Employee Education:
Businesses should provide education and communication about retirement plans to employees. This includes information about plan features, investment options, and the importance of retirement savings.
Compliance with Regulations:
Employers must comply with regulatory requirements, such as annual testing for 401(k) plans, nondiscrimination testing, and filing Form 5500 for qualified retirement plans.
It’s essential for both individuals and businesses to stay informed about changes in tax laws and retirement plan regulations. Consulting with financial advisors, tax professionals, or retirement plan administrators can help ensure that individuals and businesses make informed decisions and stay in compliance with applicable rules and regulations.

Investment Advisor
[See Full Bio](https://independentadvisorsnw.com/author/investment-advisor/) [ ](https://independentadvisorsnw.com/author/investment-advisor/)
**Categories:** All Posts, Financial Planning, Investment Advisor
---
### [Advisor Q&A: How to guide to tax optimized investing. Portfolio tax efficiency in retirement and investment strategies.](https://independentadvisorsnw.com/advisor-qa-how-to-guide-to-tax-optimized-investing-portfolio-tax-efficiency-in-retirement-and-investment-strategies/)
**Published:** January 12, 2024
**Author:** Investment Advisor
**Excerpt:** How does diversification in a portfolio support tax efficiency in retirement and investment strategies? Diversification in a portfolio can support tax efficiency in retirement and investment strategies through several key mechanisms. Here's how diversification contributes to tax efficiency.
**Content:**
**How does diversification in a portfolio support tax efficiency in retirement and investment strategies?**
Diversification in a portfolio can support tax efficiency in retirement and investment strategies through several key mechanisms. Here’s how diversification contributes to tax efficiency:
Asset Location Optimization:
Diversification allows for the strategic placement of different types of [investments in various account types based on their tax](https://independentadvisorsnw.com/homepage/education/advisor-qa-how-to-guide-to-tax-optimized-investing/) characteristics. For example, placing tax-inefficient assets that generate ordinary income, such as bonds or high-dividend stocks, in tax-advantaged accounts (e.g., Traditional IRAs or 401(k)s) can help minimize the immediate tax impact of those investments.
Tax-Efficient Asset Allocation:
Diversification enables investors to allocate their assets across different investment categories, such as stocks, bonds, and real estate. By choosing tax-efficient investments for taxable accounts, such as stocks with a lower tax impact due to capital gains treatment, investors can potentially reduce their overall tax liability.
Tax-Loss Harvesting:
Diversified portfolios provide opportunities for tax-loss harvesting. In the event that some investments incur losses, investors can sell those investments to offset capital gains in other parts of the portfolio. This can help minimize taxable gains and improve overall tax efficiency.
Capital Gains Management:
Through diversification, investors can manage capital gains by strategically rebalancing their portfolio. By selling investments that have appreciated in value and reallocating to underperforming assets, investors can control the timing and amount of capital gains, potentially reducing their tax liability.
Risk Mitigation:
Diversification helps spread risk across different asset classes, reducing the impact of poor performance in any single investment. This risk mitigation can be beneficial for tax efficiency by avoiding significant losses that might trigger capital gains taxes or by minimizing the need to sell investments at unfavorable tax times.
Tax-Efficient Withdrawals:
During retirement, a diversified portfolio provides flexibility in choosing which assets to sell for income needs. This flexibility allows retirees to manage their tax liability by strategically withdrawing from taxable, tax-deferred, and tax-exempt accounts based on their specific tax situation at the time.
Minimization of Required Minimum Distributions (RMDs):
For tax-deferred accounts like Traditional IRAs and 401(k)s, required minimum distributions (RMDs) must begin at a certain age. Diversification can help manage RMDs by allowing investors to take distributions from a variety of assets, potentially minimizing the tax impact on those distributions.
Tax-Efficient Investment Strategies:
Diversification supports the use of tax-efficient investment strategies, such as index investing or tax-managed funds. These strategies seek to minimize taxable events within the portfolio, promoting long-term tax efficiency.
It’s important to note that the tax implications of a diversified portfolio can be influenced by individual circumstances, tax laws, and market conditions. Regular portfolio reviews, in consultation with a financial advisor or tax professional, are essential to ensure that the portfolio remains aligned with an investor’s goals and tax-efficient strategies.

Investment Advisor
[See Full Bio](https://independentadvisorsnw.com/author/investment-advisor/) [ ](https://independentadvisorsnw.com/author/investment-advisor/)
**Categories:** All Posts, Financial Planning, Investment Advisor
---
### [Advisor Q&A: How to guide to tax optimized investing. Examples of strategies that combine tax efficiency with effective retirement planning.](https://independentadvisorsnw.com/advisor-qa-how-to-guide-to-tax-optimized-investing-examples-of-strategies-that-combine-tax-efficiency-with-effective-retirement-planning/)
**Published:** January 12, 2024
**Author:** Investment Advisor
**Excerpt:** Could you provide examples of strategies that combine tax efficiency with effective retirement planning? Combining tax efficiency with effective retirement planning involves implementing strategies that optimize the tax impact of investment decisions while aligning with long-term retirement goals.
**Content:**
**Could you provide examples of strategies that combine tax efficiency with effective retirement planning?**
Combining tax efficiency with effective retirement planning involves implementing strategies that optimize the tax impact of investment decisions while aligning with long-term retirement goals. Here are some examples of such strategies:
Roth IRA Conversion:
Strategy: Convert funds from a Traditional IRA to a Roth IRA.
Tax Efficiency: While the conversion is a taxable event, it can be strategically timed during years when you are in a lower tax bracket. Once converted, future withdrawals from the Roth IRA are tax-free, providing tax efficiency in retirement.
Tax-Efficient Asset Location:
Strategy: Place tax-inefficient assets, such as bonds generating interest income, in tax-advantaged accounts (e.g., Traditional IRAs or 401(k)s). Hold tax-efficient assets, like stocks with lower dividend yields and potential for capital gains, in taxable accounts.
Tax Efficiency: Minimize taxes by sheltering interest income within tax-advantaged accounts while taking advantage of favorable tax treatment on capital gains in taxable accounts.
Systematic Tax-Loss Harvesting:
Strategy: Regularly review the portfolio for investments with losses and strategically sell them to offset capital gains.
Tax Efficiency: Capitalize on market fluctuations to offset gains, reducing the overall tax liability. Harvested losses can also be used to offset up to $3,000 of ordinary income each year.
Municipal Bond Investments:
Strategy: Include municipal bonds in the portfolio.
Tax Efficiency: Interest income from municipal bonds is often tax-free at the federal level and may be exempt from state and local taxes. This can provide tax-efficient income, especially for investors in higher tax brackets.
Health Savings Account (HSA) Contributions:
Strategy: Maximize contributions to an HSA, especially if eligible.
Tax Efficiency: HSA contributions are tax-deductible, and qualified withdrawals for medical expenses are tax-free. If the HSA is not used for medical expenses in the current year, it can serve as a supplemental retirement account with tax-free withdrawals after age 65.
Blend of Taxable and Tax-Advantaged Withdrawals:
Strategy: Strategically withdraw funds from taxable, tax-deferred, and tax-exempt accounts during retirement.
Tax Efficiency: Optimize the tax impact of withdrawals by considering the tax treatment of each account type. For example, using taxable accounts for capital gains with favorable tax rates and Roth IRAs for tax-free withdrawals.
Delaying Social Security Benefits:
Strategy: Delay claiming Social Security benefits until reaching full retirement age or even beyond.
Tax Efficiency: Social Security benefits may be subject to income tax based on your combined income. Delaying benefits can reduce the percentage of benefits subject to taxation and potentially increase the benefit amount over time.
Investment in Tax-Efficient Funds:
Strategy: Choose tax-efficient investment vehicles, such as index funds or tax-managed funds.
Tax Efficiency: These funds aim to minimize taxable events, such as capital gains distributions, within the portfolio, contributing to long-term tax efficiency.
These strategies are general examples, and their effectiveness can vary based on individual circumstances. It’s crucial to work with a financial advisor who can tailor these strategies to your specific financial goals, risk tolerance, and tax situation. Regular reviews and adjustments are also important to ensure that the strategies remain aligned with your evolving needs and market conditions.

Investment Advisor
[See Full Bio](https://independentadvisorsnw.com/author/investment-advisor/) [ ](https://independentadvisorsnw.com/author/investment-advisor/)
**Categories:** All Posts, Financial Planning, Investment Advisor
---
### [Advisor Q&A: How to guide to tax optimized investing. Selecting tax-advantaged retirement and investment options.](https://independentadvisorsnw.com/advisor-qa-how-to-guide-to-tax-optimized-investing-selecting-tax-advantaged-retirement-and-investment-options/)
**Published:** January 12, 2024
**Author:** Investment Advisor
**Excerpt:** What should investors consider when selecting tax-advantaged retirement and investment options?
When selecting tax-advantaged retirement and investment options, investors should consider a variety of factors to ensure that their choices align with their financial goals and circumstances.
**Content:**
**What should investors consider when selecting tax-advantaged retirement and investment options?**
When selecting tax-advantaged retirement and investment options, investors should consider a variety of factors to ensure that their choices align with their financial goals and circumstances. Here are key considerations:
Current and Future Tax Situation:
Evaluate your current and expected future tax situation. If you are in a higher tax bracket now but anticipate being in a lower bracket during retirement, tax-deferred options like Traditional IRAs or 401(k)s may be advantageous. On the other hand, if you expect higher taxes in retirement, tax-exempt options like Roth IRAs could be more beneficial.
Investment Time Horizon:
Consider your investment time horizon and retirement timeline. Longer time horizons may provide more opportunities for compound growth, potentially favoring tax-free or tax-deferred options.
Risk Tolerance:
Assess your risk tolerance. Different tax-advantaged options may have varying risk profiles. For example, investing in individual stocks within a taxable account may expose you to capital gains taxes, while tax-advantaged retirement accounts often offer a range of investment choices with different risk levels.
Diversification:
Aim for a diversified investment portfolio. Diversification helps manage risk, and tax-advantaged accounts can hold a variety of asset classes. Consider how each option fits into your overall portfolio strategy.
Contribution Limits:
Be aware of contribution limits for each type of tax-advantaged account. Contributing the maximum allowed can maximize the tax benefits. For example, in 2023, the contribution limit for 401(k) plans is $20,500, and for Traditional and Roth IRAs, it’s $6,000 (or $7,000 for those aged 50 and older).
Employer Contributions:
If your employer offers a retirement plan with matching contributions, take advantage of it. Employer matches can significantly boost your retirement savings and provide an immediate return on your investment.
Withdrawal Rules and Penalties:
Understand the rules and penalties associated with withdrawals from different accounts. For example, early withdrawals from Traditional IRAs and 401(k)s may incur penalties, while Roth IRAs allow penalty-free withdrawals of contributions at any time.
Estate Planning Goals:
Consider your estate planning goals. Certain tax-advantaged accounts may offer advantages in terms of passing on wealth to heirs. Roth IRAs, for instance, do not have required minimum distributions (RMDs) during the original account owner’s lifetime.
Financial Advisor Guidance:
Consult with a financial advisor to tailor your strategy to your specific financial situation. A professional can help you navigate complex tax laws, assess your unique circumstances, and develop a comprehensive plan that aligns with your goals.
Regular Review and Adjustment:
Periodically review your investment and retirement plan, especially when there are changes in your financial situation, tax laws, or investment objectives. Adjust your strategy as needed to stay on track with your goals.
Choosing the right tax-advantaged retirement and investment options requires careful consideration of these factors. It’s essential to stay informed, be proactive in managing your investments, and seek professional advice when needed to make well-informed decisions.

Investment Advisor
[See Full Bio](https://independentadvisorsnw.com/author/investment-advisor/) [ ](https://independentadvisorsnw.com/author/investment-advisor/)
**Categories:** All Posts, Financial Planning, Investment Advisor
---
### [Advisor Q&A: How to guide to tax optimized investing. Tax-deferred and tax-exempt investments.](https://independentadvisorsnw.com/advisor-qa-how-to-guide-to-tax-optimized-investing-tax-deferred-and-tax-exempt-investments/)
**Published:** January 12, 2024
**Author:** Investment Advisor
**Excerpt:** How do tax-deferred and tax-exempt investments differ, especially in the context of retirement planning? Tax-deferred and tax-exempt investments differ in how they are taxed, and these distinctions have significant implications for retirement planning
**Content:**
**How do tax-deferred and tax-exempt investments differ, especially in the context of retirement planning?**
Tax-deferred and tax-exempt investments differ in how they are taxed, and these distinctions have significant implications for retirement planning. Here’s a breakdown of the key differences between tax-deferred and tax-exempt investments:
Tax-Deferred Investments:
Definition: Tax-deferred investments are those where taxes on earnings are delayed until a later date, typically when the investor makes withdrawals.
Examples:
Traditional Individual Retirement Accounts (IRAs)
401(k) plans
Deferred annuities
Contributions: Contributions to these accounts may be tax-deductible in the year they are made, reducing the investor’s taxable income.
Earnings: Earnings within these accounts grow tax-deferred, meaning that capital gains, interest, and dividends are not taxed annually.
Withdrawals: Taxes are incurred when withdrawals are made. Withdrawals are typically made during retirement when the individual may be in a lower tax bracket.
Tax-Exempt Investments:
Definition: Tax-exempt investments are those where the earnings are not subject to income tax, even when withdrawn.
Examples:
Roth Individual Retirement Accounts (IRAs)
Health Savings Accounts (HSAs) for qualified medical expenses
Municipal bonds
Contributions: Contributions to Roth IRAs and HSAs are made with after-tax dollars, meaning there is no immediate tax deduction.
Earnings: Earnings within these accounts grow tax-free. This includes capital gains, interest, and dividends.
Withdrawals: Qualified withdrawals from Roth IRAs and HSAs are entirely tax-free. Municipal bond interest income is typically tax-free at the federal level and may be exempt from state and local taxes.
In the Context of Retirement Planning:
Tax-Deferred Advantages:
Immediate Tax Benefits: Tax-deferred investments often provide immediate tax benefits through deductions on contributions, which can be particularly advantageous during an individual’s working years when they may be in a higher tax bracket.
Potential Lower Tax in Retirement: If an individual expects to be in a lower tax bracket during retirement, tax-deferred investments can result in lower taxes on withdrawals.
Tax-Exempt Advantages:
Tax-Free Withdrawals: Tax-exempt investments, especially Roth IRAs, provide the benefit of tax-free withdrawals in retirement, offering flexibility in managing income and potentially reducing overall tax liability.
No Required Minimum Distributions (RMDs): Roth IRAs do not have RMDs during the lifetime of the original account owner. This allows for more control over when and how much to withdraw in retirement.
Both tax-deferred and tax-exempt strategies can play important roles in a well-rounded retirement plan. The optimal mix depends on individual circumstances, including current and future tax situations, financial goals, and risk tolerance. Consulting with a financial advisor is crucial for tailoring an approach that aligns with an individual’s specific needs and objectives.

Investment Advisor
[See Full Bio](https://independentadvisorsnw.com/author/investment-advisor/) [ ](https://independentadvisorsnw.com/author/investment-advisor/)
**Categories:** All Posts, Financial Planning, Investment Advisor
---
### [Advisor Q&A: How to guide to tax optimized investing. Investment options that offer both retirement benefits and tax advantages.](https://independentadvisorsnw.com/advisor-qa-how-to-guide-to-tax-optimized-investing-investment-options-that-offer-both-retirement-benefits-and-tax-advantages/)
**Published:** January 12, 2024
**Author:** Investment Advisor
**Excerpt:** Can you discuss investment options that offer both retirement benefits and tax advantages? There are several investment options that offer both retirement benefits and tax advantages.
**Content:**
**Can you discuss investment options that offer both retirement benefits and tax advantages?**
Certainly! There are several investment options that offer both retirement benefits and tax advantages. These options are often designed to help individuals grow their wealth while minimizing the tax implications. Here are some common investment vehicles with dual retirement and tax advantages:
401(k) Plans:
Employer-sponsored 401(k) plans allow employees to contribute a portion of their salary on a pre-tax basis. This reduces their taxable income for the year and allows for tax-deferred growth on the contributions. Some employers also match a portion of employee contributions, providing an additional retirement benefit.
Traditional Individual Retirement Accounts (IRAs):
Traditional IRAs allow individuals to make pre-tax contributions, providing an immediate tax deduction. Similar to 401(k) plans, the earnings within the IRA grow tax-deferred until withdrawals are made in retirement. Keep in mind that there are annual contribution limits.
Roth IRAs:
While Roth IRA contributions are not tax-deductible, qualified withdrawals (including earnings) are tax-free. This provides tax advantages in retirement, making Roth IRAs a valuable option, especially for those expecting to be in a higher tax bracket in retirement.
Health Savings Accounts (HSAs):
HSAs are designed to help individuals with high-deductible health plans save for medical expenses. Contributions to HSAs are tax-deductible, and withdrawals for qualified medical expenses are tax-free. After the age of 65, withdrawals for non-medical expenses are subject to ordinary income tax but are not subject to the usual 20% penalty.
529 College Savings Plans:
While primarily designed for education savings, 529 plans can also serve as a tool for generational wealth transfer. Contributions to a 529 plan are not tax-deductible at the federal level, but some states offer tax incentives. Earnings grow tax-free, and withdrawals for qualified education expenses are tax-free.
Real Estate Investment Trusts (REITs):
REITs are investment vehicles that own, operate, or finance income-generating real estate. They offer the potential for both capital appreciation and income. Dividends from REITs may qualify for favorable tax treatment, and if held in tax-advantaged accounts, any capital gains or dividends can accumulate tax-deferred.
Municipal Bonds:
Municipal bonds are debt securities issued by state and local governments. Interest income from municipal bonds is often tax-free at the federal level and may also be exempt from state and local taxes, providing tax advantages for investors in higher tax brackets.
It’s important to note that the tax laws and regulations surrounding these investment options can vary, and individuals should consult with a financial advisor to determine the best strategy based on their specific financial goals and circumstances. Additionally, investment decisions should align with an individual’s risk tolerance and overall financial plan.

Investment Advisor
[See Full Bio](https://independentadvisorsnw.com/author/investment-advisor/) [ ](https://independentadvisorsnw.com/author/investment-advisor/)
**Categories:** All Posts, Financial Planning, Investment Advisor
---
### [Advisor Q&A: How to guide to tax optimized investing. Tax-deductible Strategies.](https://independentadvisorsnw.com/advisor-qa-how-to-guide-to-tax-optimized-investing-tax-deductible-strategies/)
**Published:** January 12, 2024
**Author:** Investment Advisor
**Excerpt:** How do tax-deductible strategies specifically aid in retirement and investment planning? Tax-deductible strategies play a crucial role in retirement and investment planning by providing individuals with opportunities to reduce their taxable income, increase savings, and optimize their financial portfolios.
**Content:**
**How do tax-deductible strategies specifically aid in retirement and investment planning?**
Tax-deductible strategies play a crucial role in retirement and investment planning by providing individuals with opportunities to reduce their taxable income, increase savings, and optimize their financial portfolios. Here are several ways in which tax-deductible strategies can be advantageous:
Deferred Taxation:
Contributions to certain retirement accounts, such as 401(k)s or Traditional IRAs, are often tax-deductible. This means that the money contributed is deducted from your taxable income in the year of contribution, potentially lowering your tax liability.
Increased Savings Potential:
The tax deductions associated with retirement accounts provide an incentive for individuals to contribute more to these accounts, thereby increasing their overall savings for retirement. This is particularly beneficial when individuals are in higher tax brackets during their working years.
Tax-Advantaged Growth:
Investments held within tax-advantaged accounts, like a Roth IRA or a Health Savings Account (HSA), can grow tax-free. This means that any capital gains, dividends, or interest earned on investments within these accounts are not subject to current income taxes, providing a compounding growth benefit over time.
Asset Location Optimization:
Tax planning involves strategically placing investments in different account types based on their tax characteristics. For example, placing tax-inefficient investments in tax-advantaged accounts can minimize the tax impact on those investments, while holding tax-efficient investments in taxable accounts can potentially reduce overall taxes.
Tax-Efficient Withdrawal Strategies:
During retirement, having a mix of taxable and tax-advantaged accounts allows for flexibility in managing withdrawals. This flexibility can be used to minimize the tax impact of distributions, potentially allowing retirees to keep more of their savings.
Tax Credits for Contributions:
Some contributions to retirement accounts may be eligible for tax credits, such as the Saver’s Credit in the United States. This provides an additional incentive for individuals with lower incomes to contribute to retirement accounts.
Estate Planning Benefits:
In some cases, tax-deductible contributions to retirement accounts can have estate planning benefits, allowing for the transfer of wealth to heirs with potential tax advantages.
It’s important for individuals to work with a financial advisor to tailor these strategies to their specific financial situation and goals. Tax laws and regulations can change, so staying informed and adapting strategies accordingly is crucial for effective retirement and investment planning.

Investment Advisor
[See Full Bio](https://independentadvisorsnw.com/author/investment-advisor/) [ ](https://independentadvisorsnw.com/author/investment-advisor/)
**Categories:** All Posts, Financial Planning, Investment Advisor
---
### [Independent Investment Advisors Receives 2023 Best of Portland Award - Financial Planner](https://independentadvisorsnw.com/independent-investment-advisors-receives-2023-best-of-portland-award-financial-planner/)
**Published:** March 30, 2023
**Author:** Financial Planner
**Excerpt:** PORTLAND January 22, 2023 – For two consecutive years, Independent Investment Advisors has been selected for the 2023 Best of Portland Award in the Financial Planner category by the Portland Award Program.
**Content:**
Press Release: Independent Investment Advisors has been selected for the 2023 Best of Portland Award in the Financial Planner category by the Portland Award Program.
FOR IMMEDIATE RELEASE
**Independent Investment Advisors Receives 2023 Best of Portland Award**
Portland Award Program Honors the Achievement
PORTLAND January 22, 2023 – For two consecutive years, Independent Investment Advisors has been selected for the 2023 Best of Portland Award in the Financial Planner category by the Portland Award Program.
Each year, the Portland Award Program identifies companies that we believe have achieved exceptional marketing success in their local community and business category. These are local companies that enhance the positive image of small business through service to their customers and our community. These exceptional companies help make the Portland area a great place to live, work and play.
Various sources of information were gathered and analyzed to choose the winners in each category. The 2023 Portland Award Program focuses on quality, not quantity. Winners are determined based on the information gathered both internally by the Portland Award Program and data provided by third parties.
About Portland Award Program
The Portland Award Program is an annual awards program honoring the achievements and accomplishments of local businesses throughout the Portland area. Recognition is given to those companies that have shown the ability to use their best practices and implemented programs to generate competitive advantages and long-term value.
The Portland Award Program was established to recognize the best of local businesses in our community. Our organization works exclusively with local business owners, trade groups, professional associations and other business advertising and marketing groups. Our mission is to recognize the small business community’s contributions to the U.S. economy.
SOURCE: Portland Award Program
CONTACT:
Portland Award Program
Email: PublicRelations@businesses-honor.com
URL: http://www.businesses-honor.com
Independent Investment Advisors Receives 2023 Best of Portland Award

Financial Planner
[See Full Bio](https://independentadvisorsnw.com/author/financial-planner/) [ ](https://independentadvisorsnw.com/author/financial-planner/)
**Categories:** All Posts, News and Announcements
---
### [Independent Investment Advisors Receives Financial Advisory of the Year – Oregon Award](https://independentadvisorsnw.com/independent-investment-advisors-receives-financial-advisory-of-the-year-oregon-award/)
**Published:** November 30, 2022
**Author:** Investment Advisor
**Excerpt:** PORTLAND October, 2022 — Independent Investment Advisors has been selected for the 2022/23 Financial Advisory of the Year | Oregon by the Corporate Livewire and LTG / USA Prestige Guide
**Content:**
[< back to Market Insights Blog](https://independentadvisorsnw.com/homepage/markets-insights/)
*PORTLAND October, 2022 — Independent Investment Advisors has been selected for the 2022/23 Financial Advisory of the Year | Oregon by the Corporate Livewire and LTG / USA Prestige Guide*
***Press Release***
FOR IMMEDIATE RELEASE
From the publisher:
“Each year, USA Prestige Guide identifies companies they believe have achieved exceptional success in their local community. We invite both readers and contributors to the Corporate Livewire and LTG publications to put forward companies, products, services, and individuals who they feel are deserving of recognition. We ask each nominee to submit supporting information for their chosen category and our panel of judges ultimately pick a winner in each area. Over the last 16 years our awards have run on an international basis. In 2017 we introduced our regional awards to recognize smaller, independent businesses that are extremely successful on a local or national level.“
Based in Portland, Independent Investment Advisors is an independent fiduciary registered investment advisor with expertise in financial planning, investment management and financial advice. Their mission is to provide the highest quality, reliable fiduciary financial advice and help clients define and attain their goals. The team of highly qualified professionals work with a limited number of clients, which translates into deeper and more intimate relationships, customized financial plans, portfolios and risk management programs and better results across the board. Founder and principal advisor, Goran Ognjenovic, has spent more than 20 years working in active roles within financial planning and investments.
“THE TEAM OF HIGHLY QUALIFIED PROFESSIONALS WORK WITH A LIMITED NUMBER OF CLIENTS, WHICH TRANSLATES INTO DEEPER AND MORE INTIMATE RELATIONSHIPS.”
The judges were particularly impressed by the efforts made at Independent Investment Advisors to help any and all types of clients. The advisory specialists have a variety of on-going projects, working alongside individuals, families, estates and small businesses and dedicate their services to establishing the most efficient and cost-effective ways to help each one of them. The investment needs of SMEs are slightly different from the average corporate employee and Goran works with them on retirement planning, money management and tax efficient investments.

Investment Advisor
[See Full Bio](https://independentadvisorsnw.com/author/investment-advisor/) [ ](https://independentadvisorsnw.com/author/investment-advisor/)
**Categories:** All Posts, News and Announcements
---
### [Why we think the Fed is still behind the curve](https://independentadvisorsnw.com/why-we-think-the-fed-is-still-behind-the-curve/)
**Published:** April 15, 2022
**Author:** Investment Advisor
**Excerpt:** We maintain our view that inflation will remain elevated and that monetary policy is behind the curve. Markets are pricing in about seven 25-basis-point rate increases in 2022. The surge in commodity prices — spanning energy, metals, raw materials and agricultural products — will also feed into inflation.
**Content:**
[< back to Market Insights Blog](https://independentadvisorsnw.com/homepage/markets-insights/)
**Here is some great in-depth research done by one of our fund providers!**
Fed Chairman Jerome Powell reinforced in his comments that the central bank’s primary goal is to tamp down inflation — which is running at a 40-year high — and that it will do what it takes to bring it closer to target. The central bank chief also talked positively about growth and the labor market. “All signs are that this is a strong economy,” Powell said. “Indeed, one that will be able to flourish … in the face of less accommodative monetary policy.”
We maintain our view that inflation will remain elevated and that monetary policy is behind the curve. Markets are pricing in about seven 25-basis-point rate increases in 2022. Powell seems confident that the U.S. economy can withstand higher rates, and so barring a major fundamental shock, we expect the Fed will continue on its tightening path for the rest of 2022. He left open the possibility of a 50-basis-point hike but did not specify what might trigger such a move.
Powell emphasized that he wants to see the month-over-month inflation numbers come down. The Fed is increasingly concerned about inflation becoming unmanageable, and its latest projections indicate it may move rates above its estimated long-term neutral rate of 2.4% by next year. The neutral rate is a theoretical federal funds rate at which monetary policy is considered neither accommodative nor restrictive.
Consistent with this view, we favor positioning bond portfolios for tighter financial conditions by maintaining a short duration focused on two-year maturities. We expect the Treasury yield curve to flatten further, led by a rise in shorter maturities while long-term interest rates remain in a range.
We also anticipate quantitative tightening (QT) plans could be unveiled in May and begin in June following another rate increase at the Fed’s May meeting. The central bank will likely shrink its balance sheet by not replacing maturing bonds. While actively selling securities is a possibility, it is not its preferred path.
**Peak fed funds rate has declined with each successive hiking cycle**
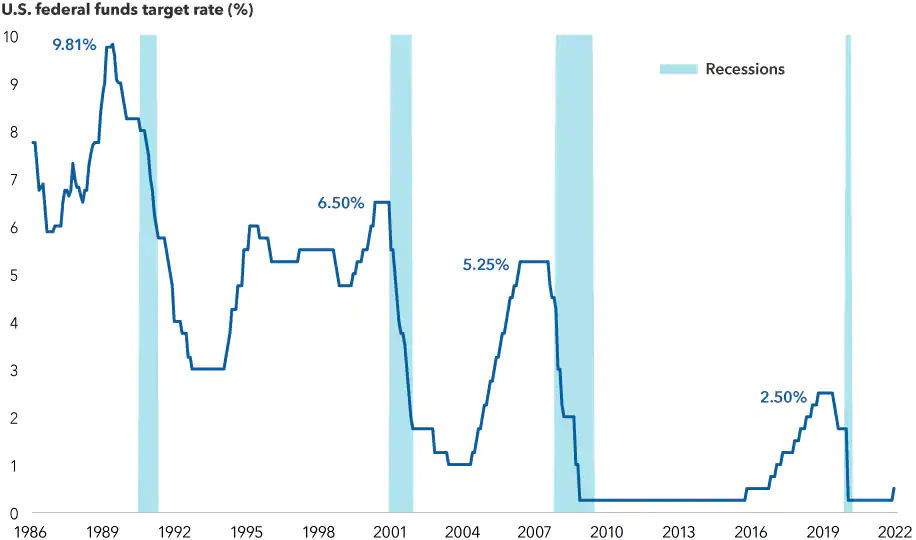Sources Capital Group US Bureau of Labor Statistics As of February 28 2022### Tight labor markets complicate the inflation picture
The Fed remains focused on fighting inflation despite a dampened growth outlook given the war in Ukraine. Inflation rose sharply in February with the headline and core metrics accelerating to 7.9% and 6.4% year-over-year, respectively. We continue to see broadening price pressures across major categories, and we see a 50% chance that CPI will accelerate in the coming months. In shelter, the largest component of the Consumer Price Index, prices have increased 4.8% year-over-year, the fastest pace since the early 1990s. Even if you strip out shelter and other high-inflation categories, CPI remains elevated and on an upward trend.
The surge in commodity prices — spanning energy, metals, raw materials and agricultural products — will also feed into inflation. The Bloomberg Commodity Index doubled in the past two years, an increase not seen since the early 1980s. The greatest impact is likely to be felt by lower income consumers as food and gas make up a large percentage of their spending.
**Inflation is being driven higher by several components**
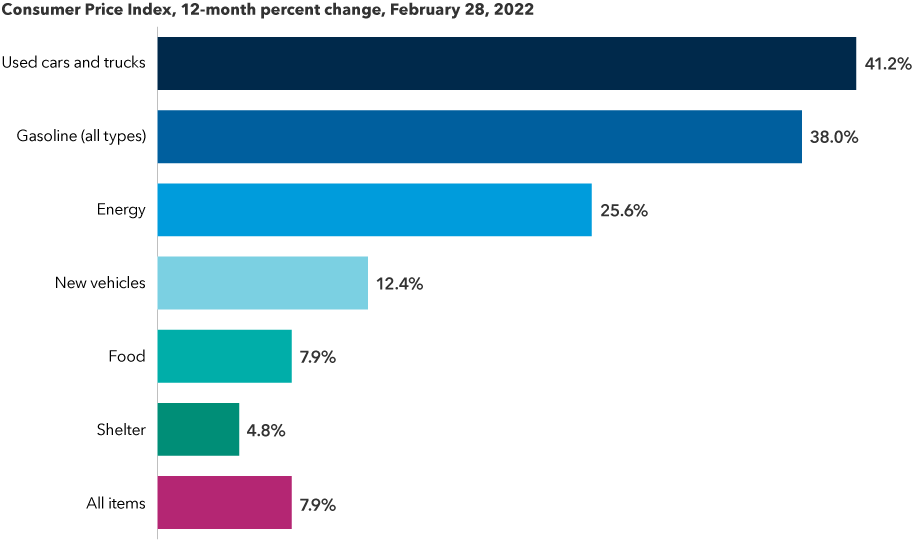Sources Capital Group US Bureau of Labor Statistics As of February 28 2022With supply chain issues likely to remain troublesome and the war creating upside risks to food and energy prices, market participants are pricing rising inflation risk premia (a measure of the premium investors require for the possibility that inflation may rise or fall more than expected over the period in which a bond is held) into bonds. Breakeven inflation on five-year Treasury Inflation-Protected Securities (TIPS) has risen from 3.0% to around 3.5% this year, the highest reading since the launch of the asset class.
Wage growth and a variety of other indicators point to ongoing pressure in the labor market, which Powell said Wednesday had reached an “unhealthy level” of tightness. In February, the U.S. added 678,000 jobs, bringing unemployment down to 3.8%. The labor force participation rate rebounded to 62.3% in February, its highest level since March 2020, indicating there are going to be fewer workers on the sidelines. We are also seeing historically elevated quit rates, signaling that workers have confidence in their ability to find other employment — often with better pay. Average hourly earnings stagnated between January and February but remain up 5.1% over the past 12 months.
We believe the Fed’s most likely plan will be to move steadily toward restrictive policy with consecutive 25-basis-point hikes until policy rates are at or slightly above neutral. However, we are not ruling out the possibility that the central bank will move in a more forceful, Paul Volcker-esque manner. (In 1981, then Fed Chairman Volcker sharply raised rates to contain runaway inflation.)
In terms of societal impact, the Fed faces tough choices. If the Fed remains dovish, allowing inflation to run unchecked, food and energy prices would be among the most likely to accelerate. If it tightens aggressively and stymies growth, unemployment would likely move up and wage increases would be curtailed.
### Global overview
The Fed is not alone in its path. Major central banks in Europe have signaled a more hawkish stance in recent weeks as inflation continues to outpace their targets.
The European Central Bank delivered a hawkish message at its March meeting, laying out plans to end its asset purchase program by the third quarter of this year and, in the process, paving the way for a potential rate hike.
Despite the downside risks to growth stemming from the war in Ukraine, ECB President Christine Lagarde focused her remarks on the upside risks to inflation and stressed “optionality and flexibility” in the governing council’s policy stance. The front-end of the euro curve is pricing in roughly 30 basis points of hikes by year-end.
Meanwhile, we expect the Bank of England to deliver another rate increase this week, hiking to 0.75%. This follows the 25-basis-point hike and initiation of passive QT announced in February. All in all, these actions should lead to tighter financial conditions in most of the major developed economies.
Against this backdrop, we maintain a defensive posture in our fixed income portfolios. In U.S. core bond portfolios, in addition to a short duration and positioning for a flattening of the yield curve, we also favor a slight relative underweight to credit. Meanwhile, TIPS prices largely reflect inflationary expectations, so managers are more opportunistic based on where they see value along the maturity spectrum.
In many equity portfolios, depending on investment objectives and mandate, we are starting to see managers selectively add to investments in energy, materials, mining companies, consumer staples and other consumer-related companies with a degree of pricing power.
---
***Ritchie Tuazon*** *is a fixed income portfolio manager with 21 years of industry experience. He holds an MBA from MIT, a master’s in public administration from Harvard and a bachelor’s from the University of California, Berkeley.*
***Timothy Ng*** *is a fixed income portfolio manager with 16 years of industry experience. He holds a bachelor’s degree with honors in computer science from the University of Waterloo, Ontario.*
***Thomas Hollenberg*** *is a fixed income portfolio manager with 16 years of industry experience. He holds an MBA in finance from MIT Sloan School of Management and a bachelor’s degree in economics from Boston College.*

Investment Advisor
[See Full Bio](https://independentadvisorsnw.com/author/investment-advisor/) [ ](https://independentadvisorsnw.com/author/investment-advisor/)
**Categories:** All Posts, Investment Advisor
---
### [Independent Investment Advisors Receives 2022 Best of Portland Award](https://independentadvisorsnw.com/independent-investment-advisors-receives-2022-best-of-portland-award/)
**Published:** August 1, 2022
**Author:** Financial Planner
**Excerpt:** PORTLAND July 22, 2022 -- Independent Investment Advisors has been selected for the 2022 Best of Portland Award in the Financial Planner category by the Portland Award Program. Each year, the Portland Award Program identifies companies that we believe have achieved exceptional success in their local community and business category.
**Content:**
PORTLAND July 22 2022 Independent Investment Advisors has been selected for the 2022 Best of Portland Award in the Financial Planner category by the Portland Award ProgramPress Release
FOR IMMEDIATE RELEASE
Independent Investment Advisors Receives 2022 Best of Portland Award
Portland Award Program Honors the Achievement
PORTLAND July 22, 2022 — Independent Investment Advisors has been selected for the 2022 Best of Portland Award in the Financial Planner category by the Portland Award Program.
Each year, the Portland Award Program identifies companies that we believe have achieved exceptional marketing success in their local community and business category. These are local companies that enhance the positive image of small business through service to their customers and our community. These exceptional companies help make the Portland area a great place to live, work and play.
Various sources of information were gathered and analyzed to choose the winners in each category. The 2022 Portland Award Program focuses on quality, not quantity. Winners are determined based on the information gathered both internally by the Portland Award Program and data provided by third parties.
About Portland Award Program
The Portland Award Program is an annual awards program honoring the achievements and accomplishments of local businesses throughout the Portland area. Recognition is given to those companies that have shown the ability to use their best practices and implemented programs to generate competitive advantages and long-term value.
The Portland Award Program was established to recognize the best of local businesses in our community. Our organization works exclusively with local business owners, trade groups, professional associations and other business advertising and marketing groups. Our mission is to recognize the small business community’s contributions to the U.S. economy.
SOURCE: Portland Award Program
CONTACT:
Portland Award Program
Email: PublicRelations@awardsrecognition-businesses.com
URL: http://www.awardsrecognition-businesses.com
**[2022 Best of Portland Awards – Financial Planner](http://portland.awardsrecognition-businesses.com/shrjbsp7_INDEPENDENT-INVESTMENT-ADVISORS)**
\###

Financial Planner
[See Full Bio](https://independentadvisorsnw.com/author/financial-planner/) [ ](https://independentadvisorsnw.com/author/financial-planner/)
**Categories:** All Posts, Financial Planning, News and Announcements
---
### [Welcome to 2022!](https://independentadvisorsnw.com/welcome-to-2022/)
**Published:** January 10, 2022
**Author:** Investment Advisor
**Excerpt:** May it bring us peace, prosperity, and a whole lotta love. And some greater certainty about what lies ahead. This email includes precious little certainty, but it does have kittens.
**Content:**
[< back to Market Insights Blog](https://independentadvisorsnw.com/homepage/markets-insights/)
Welcome to 2022!
May it bring us peace, prosperity, and a whole lotta love.
And some greater certainty about what lies ahead.
This email includes precious little certainty, but it does have kittens. (All the way down in the P.S.)
You’re probably seeing an endless parade of emails, listicles, and thought pieces loaded with predictions for 2022.
**Will these predictions be right?**
In some ways.
**Will they be wrong?**
Almost certainly.
**Predictions are usually judged by how right or wrong they turn out to be.**
Is that the right approach?
Is there innate value in the exercise of looking at the current state of things and thinking about where the winds will take us, to mix metaphors?
Beyond the success or failure of our prognostications?
I think so.
I also think revisiting predictions to see where and why we got it wrong is a great exercise in how complex our world really is.
Rather than issue predictions about 2022 that are certain to be wrong, here are some musings about trends I think will play a role this year.
**There’s hope for COVID-19 in 2022.**
As Omicron numbers skyrocket, it’s clear the pandemic is still with us in this third year.
But, I’m hopeful that increasing vaccination rates, medical advances like Pfizer’s at-home anti-viral pill, and decreasing virulence could help reduce the impact of COVID on our lives.1
I also want to acknowledge that our outlook as Americans is not reflected in every country around the world. Getting to the other side of this pandemic will require the whole world’s efforts.
I deeply hope this is our year.
**The economy looks poised for more growth.**
Despite plenty of hurdles, the U.S. economy looks to have entered 2022 in shape for more growth.
Current estimates suggest the economy will continue to grow this year, faster than typical historical trends.2
But all that depends on **a lot** of assumptions about variants, spending, hiring, inflation, and more. We’ll see just how rosy those assumptions are as the year progresses.
**Politics will dominate headlines.**
Mid-term elections mean politics will play a big role (in the media at least).
Election years always mean uncertainty, and that often rattles markets. However, historical analysis shows that markets typically bounce back after election uncertainty is over.3
While the past doesn’t predict the future, it’s a good reminder of why we don’t let elections drive strategy. They’re just one more factor in a very complex system.
**Folks are ready for some kind of normal.**
I think it’s safe to say that we’re all tired of the pandemic and longing for normalcy.
What does normal look like in 2022?
Will it look like what we had before the pandemic? Will it be completely different?
What do you think?
Do you have any predictions for 2022 to share?
Be well,
**Goran Ognjenovic**
Independent Investment Advisors
(971) 350-8068
[www.independentadvisorsnw.com](https://independentadvisorsnw.com)
---
P.S. These are the kittens you’re looking for. [Here’s a live kitten cam from a rescue.](https://www.youtube.com/watch?v=9Iup70E0Ig0&ab_channel=ExploreLiveNatureCams)
P.P.S. Need some inspiration for the new year? [Here’s a curated list of Ted talks to get you going.](https://www.ted.com/playlists/217/talks_to_inspire_new_year_s_re) I think the talks on happiness and stress are particularly fascinating.
1-
2-
3-
Risk Disclosure: Investing involves risk including the potential loss of principal. No investment strategy can guarantee a profit or protect against loss in periods of declining values. Past performance does not guarantee future results.
This material is for information purposes only and is not intended as an offer or solicitation with respect to the purchase or sale of any security. The content is developed from sources believed to be providing accurate information; no warranty, expressed or implied, is made regarding accuracy, adequacy, completeness, legality, reliability, or usefulness of any information. Consult your financial professional before making any investment decision. For illustrative use only.
The following posts and commentary are to be used solely as educational tools and do not contain investment advice. Investment advice must be tailored to a particular investor’s specific needs. None of the information contained should be construed to be investment advice. Individuals wishing to tailor a plan to their own needs should seek the help of a Registered Investment Advisor.
There is a high degree of risk in investing and trading. Independent Investment Advisors assumes no responsibility. Principles of Independent Investment Advisors may, at times, maintain directly or indirectly, positions in securities or derivatives mentioned in these comments.

Investment Advisor
[See Full Bio](https://independentadvisorsnw.com/author/investment-advisor/) [ ](https://independentadvisorsnw.com/author/investment-advisor/)
**Categories:** All Posts
---
### [Inflation is High and Persistent](https://independentadvisorsnw.com/inflation-is-high-and-persistent/)
**Published:** November 19, 2021
**Author:** Financial Planner
**Excerpt:** In the U.S., prices have increased 6.2% over the last 12 months — the biggest spike since November 1990. And you can see in the chart that some categories measured by the Consumer Price Index (CPI) have soared by much more. Since the Fed's goal is to keep long-term inflation around 2% (and that's what we've experienced this century), folks are concerned that "temporary" inflation is lingering longer than we want.
**Content:**
[< back to Market Insights Blog](https://independentadvisorsnw.com/homepage/markets-insights/)
I hope you’re warm, well, and looking forward to some time with family and friends.
I wanted to drop you a quick email about a couple of things: infrastructure, inflation, and taxes.
And I’ve got a blue-sky question for you at the end. I’m really interested in hearing your thoughts.
**President Biden just signed his much-debated bipartisan infrastructure deal.**
What does that mean for the economy?
In the short term, some of the infrastructure funding will go immediately toward clearing port and transportation bottlenecks, so that might help improve supply chain issues.1 Fingers crossed.
Though it could be years before you or I drive across a new bridge or highway funded by the bill, some of the maintenance funds could get used in spring construction blitzes.2
Since the job market is already tight, the economy isn’t likely to see an immediate surge in hiring due to infrastructure spending; however, multiple reports suggest ~800,000 new jobs could be added by 2030, though many of them will be temporary rather than long-term jobs.
Economists don’t think inflation is likely to increase due to the slow pace of spending, though the deal is projected to add $256 billion to the federal budget deficit over the next 10 years.
Bottom line, analysts project long-term benefits to the economy in lower business costs, increased labor force participation, and improved competitiveness.3
**Inflation might not be as temporary as the Federal Reserve would like it to be.**
Prices are up all over, and folks are understandably upset at paying more at the grocery store, gas station, and most everywhere else.
Many analysts hoped that data blips, supply chain clogs, and other pandemic-related disruptions were creating a temporary spike in inflation that would resolve soon.4
However, inflation has remained stubbornly high.
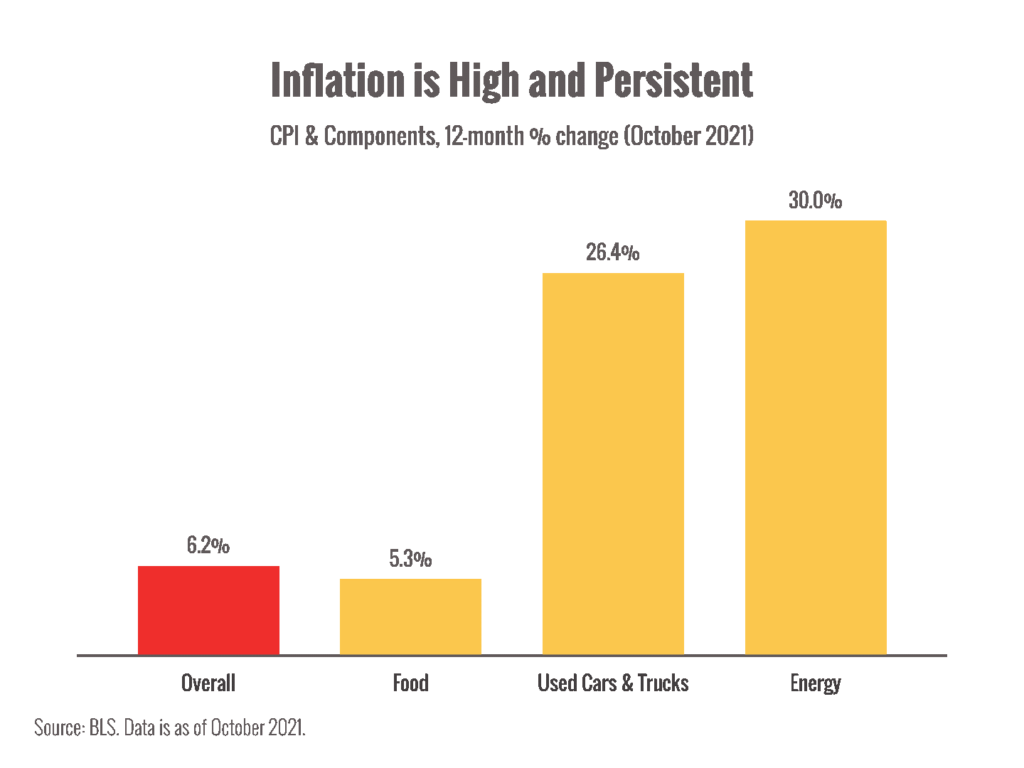CPI Components 12 month change October 2021In the U.S., prices have increased 6.2% over the last 12 months — the biggest spike since November 1990. And you can see in the chart that some categories measured by the Consumer Price Index (CPI) have soared by much more.5
Since the Fed’s goal is to keep long-term inflation around 2% (and that’s what we’ve experienced this century), folks are concerned that “temporary” inflation is lingering longer than we want.
So, are prices going to continue to rise in 2022?
That’s likely, but how much, how fast, and for how long depend on a lot of global factors, including whether the Fed raises interest rates or takes other actions.
I’m keeping an eye on it.
**Will your taxes go up in 2022?**
That’s the question of the month on Capitol Hill as lawmakers debate the Build Back Better deal that could come with tax law changes.
We don’t know when (or if) the bill will be passed, but I’m watching closely and I’ll update you when we know what’s likely to happen.
**Before I go, I’d like to wish you and yours a relaxing Thanksgiving with great food, great fun, and great memories.**
Gratefully yours,
**Goran Ognjenovic**
Independent Investment Advisors
(971) 350-8068
[www.independentadvisorsnw.com](https://independentadvisorsnw.com)
---
P.S. It’s the time of year when the analysts start making predictions for 2022. What are your predictions for next year? What will be the big themes? Hit “reply” and let me know your thoughts!
1
2[ https://www.cnn.com/2021/11/09/politics/biden-infrastructure-bill-spending-economy/index.html](https://www.cnn.com/2021/11/09/politics/biden-infrastructure-bill-spending-economy/index.html)
3
4
5
This information is not intended to be a substitute for specific individualized tax advice. We suggest that you discuss your specific situation with a qualified tax professional.
The following posts and commentary are to be used solely as educational tools and do not contain investment advice. Investment advice must be tailored to a particular investor’s specific needs. None of the information contained should be construed to be investment advice. Individuals wishing to tailor a plan to their own needs should seek the help of a Registered Investment Advisor.
There is a high degree of risk in investing and trading. Independent Investment Advisors assumes no responsibility. Principles of Independent Investment Advisors may, at times, maintain directly or indirectly, positions in securities or derivatives mentioned in these comments.

Financial Planner
[See Full Bio](https://independentadvisorsnw.com/author/financial-planner/) [ ](https://independentadvisorsnw.com/author/financial-planner/)
**Categories:** All Posts, Financial Planning
---
### [Wrestling with the unknown (+ uplifting news)](https://independentadvisorsnw.com/wrestling-with-the-unknown-uplifting-news/)
**Published:** December 3, 2021
**Author:** Investment Advisor
**Excerpt:** Let’s talk about omicron.
(If you’d rather not, scroll right down to the P.S. for something beautiful.)
Since the first known cases of COVID-19 were detected in China, we've seen a number of notable mutations as the virus moved across the world. Some, like beta and gamma, didn’t end up being a huge deal.1
**Content:**
[< back to Market Insights Blog](https://independentadvisorsnw.com/homepage/markets-insights/)
Let’s talk about omicron.
(If you’d rather not, scroll right down to the P.S. for something beautiful.)
Since the first known cases of COVID-19 were detected in China, we’ve seen a number of notable mutations as the virus moved across the world. Some, like beta and gamma, didn’t end up being a huge deal.1
Others, like delta, spread rapidly and caused new waves of infection.
Now we have another variant on our hands: omicron. And it could be a serious one.
Unsurprisingly, markets reacted badly to the news last Friday and gave us our worst market day for the year.2
Why? The short trading day and lack of overall volume over the holiday break gave the selling pressure greater impact on the market than it might have had under normal conditions.
We’ve seen that pattern before and it’s worth keeping in your back pocket: bad news over a holiday often leads to outsized market reactions.
**Is omicron dangerous?**
Well, we don’t know yet. And we won’t know for several weeks until scientists can determine how the variant will respond to current vaccines and treatments.
If it’s more virulent, it could have delta-level impacts on travel, hospitality, and other parts of the economy.
It could also turn out to be a tiny bump in the road.
We just don’t know yet.
The market is laser-focused on omicron news so we can expect rocky times until the uncertainty clears (or something else takes over the chatter).
**So, what can we do?**
Rather than try to predict the unknowable or speculate wildly without enough information, let’s do something else instead.
Let’s take a deep breath, step back, and focus on some ground truths:
Everyone is tired of this pandemic and ready to move on. But the pandemic’s not done yet.
We will continue to see COVID-19 variants. Most will fade into the background. Some will be more serious.
New vaccines and treatments are continually being developed and released.
We have been adapting to the virus for nearly two years and we’ll continue to get better at it.
**Life is a gift and every day is extraordinary in some way. Let’s cherish that.**
Hopefully, we’ll look back in a few months and forget omicron ever hit the headlines.
Until then, we wait, we watch, and we count our blessings.
I’ll be in touch when there’s more to share.
Be well,
**Goran Ognjenovic**
Independent Investment Advisors
(971) 350-8068
[www.independentadvisorsnw.com](https://independentadvisorsnw.com)
---
P.S. Can I share something uplifting with you? A retired dad (who already fostered 30 kids) adopted five young siblings so they could grow up together.3 How beautiful is that?
P.P.S. Want to learn more about happiness and how to get off the hedonic treadmill? [Check out one of the very first TED talks on the science of happiness](https://www.ted.com/talks/dan_gilbert_the_surprising_science_of_happiness#t-1247514). Thoughts? Hit “reply” and let me know.
---
1
2
3 [https://www.cbsnews.com/news/foster-dad-lamont-thomas-adopts-five-siblings](https://www.cbsnews.com/news/foster-dad-lamont-thomas-adopts-five-siblings/)
Risk Disclosure: Investing involves risk including the potential loss of principal. No investment strategy can guarantee a profit or protect against loss in periods of declining values. Past performance does not guarantee future results. This material is for information purposes only and is not intended as an offer or solicitation with respect to the purchase or sale of any security. The content is developed from sources believed to be providing accurate information; no warranty, expressed or implied, is made regarding accuracy, adequacy, completeness, legality, reliability or usefulness of any information. Consult your financial professional before making any investment decision. For illustrative use only.
The following posts and commentary are to be used solely as educational tools and do not contain investment advice. Investment advice must be tailored to a particular investor’s specific needs. None of the information contained should be construed to be investment advice. Individuals wishing to tailor a plan to their own needs should seek the help of a Registered Investment Advisor.
There is a high degree of risk in investing and trading. Independent Investment Advisors assumes no responsibility. Principles of Independent Investment Advisors may, at times, maintain directly or indirectly, positions in securities or derivatives mentioned in these comments.

Investment Advisor
[See Full Bio](https://independentadvisorsnw.com/author/investment-advisor/) [ ](https://independentadvisorsnw.com/author/investment-advisor/)
**Categories:** All Posts, Investment Advisor
---
### [Gratitude practice?](https://independentadvisorsnw.com/gratitude-practice/)
**Published:** November 15, 2021
**Author:** Financial Planner
**Excerpt:** The last few weeks and months have had a lot of stress and uncertainty.
So, instead of writing to you about politics, or the economy, or the supply chain, I figured I'd change the script and write about something completely different. Let's talk about gratitude.
**Content:**
[< back to Market Insights Blog](https://independentadvisorsnw.com/homepage/markets-insights/)
The last few weeks and months have had a lot of stress and uncertainty.
So, instead of writing to you about politics, or the economy, or the supply chain, I figured I’d change the script and write about something completely different.
Let’s talk about gratitude.
Is gratitude a practice for you?
In my role as a financial professional, I’ll tell you that it should be.
Why?
Gratitude reminds you of what really matters Gratitude reminds you of what really matters.
Not the lines at the store.
Not the traffic.
Not what happens on Capitol Hill or Wall Street.
But, what really, truly matters.
I am deeply, abundantly grateful today.
For the food in my fridge.
For the roof over my head.
For my health.
For my circle of family and friends who love me.
For my community that has given me a home.
For my amazing clients and partners who have given me a vocation.
**I’m grateful for you.**
Taking inventory of all my blessings gets me through the minor irritations.
It also helps me reset when something major happens.
Gratitude calms me when things get stressful and overwhelming.
What are you grateful for?
Has it changed over these crazy couple of years?
Do you have any rituals around gratitude?
Please write back and let me know. I’m excited to hear from you.
With gratitude,
**Goran Ognjenovic**
Independent Investment Advisors
(971) 350-8068
[www.independentadvisorsnw.com](https://independentadvisorsnw.com)
---
P.S. Can I ask you to do something with me? Would you send an email or text to three people you are grateful for? I bet you’ll make their day. I wrote to you, so now I’ve just got two more :). Hit “reply” and share any responses you get.
P.P.S. Want some insight into the relationship between gratitude and happiness? **[Here’s a great TED talk on the topic by Benedictine monk David Steindl-Rast](https://www.youtube.com/watch?v=UtBsl3j0YRQ)**. If you watch it, will you send me your thoughts?
The following posts and commentary are to be used solely as educational tools and do not contain investment advice. Investment advice must be tailored to a particular investor’s specific needs. None of the information contained should be construed to be investment advice. Individuals wishing to tailor a plan to their own needs should seek the help of a Registered Investment Advisor.
There is a high degree of risk in investing and trading. Independent Investment Advisors assumes no responsibility. Principles of Independent Investment Advisors may, at times, maintain directly or indirectly, positions in securities or derivatives mentioned in these comments.

Financial Planner
[See Full Bio](https://independentadvisorsnw.com/author/financial-planner/) [ ](https://independentadvisorsnw.com/author/financial-planner/)
**Categories:** All Posts, Financial Planning
---
### [Latest on taxes](https://independentadvisorsnw.com/latest-on-taxes/)
**Published:** October 8, 2021
**Author:** Investment Advisor
**Excerpt:** Capitol Hill is producing more drama than Hollywood. We've got bold statements, ultimatums, cliff-hangers, and confusing sequels. We've even got folks paddling up to Senators' party boats to discuss tax reform.
**Content:**
[< back to Market Insights Blog](https://independentadvisorsnw.com/homepage/markets-insights/)
Capitol Hill is producing more drama than Hollywood.
We’ve got bold statements, ultimatums, cliff-hangers, and confusing sequels.
We’ve even got folks paddling up to Senators’ party boats to discuss tax reform.
**Let’s recap what we know with some educated speculation about what could happen next.**
\[Scroll down to the bottom for the nitty-gritty if you want to skip the details.\]
Congress is currently debating two action items on President Biden’s “Build Back Better” agenda: The American Jobs Plan (which includes corporate tax increases) and the American Families Plan (which includes individual tax increases).1
**Neither plan looks close to passing in its current form, so nothing is set in stone yet.**
But the provisions below offer a blueprint for what could happen.
The House is negotiating a package of tax increases that would pay for expanding Medicare, free community college and prekindergarten, and increase the federal safety net.2
If passed as-is, it would:
- Increase the top marginal income tax rate to 39.6% for individuals earning more than $400,000, joint filers above $450,000, and head of household filers above $425,000.
- Raise the top long-term capital gains rate from 20% to 25% for those same folks.
- Add a 3% tax on incomes of over $5 million.
But wait… there’s more. Here are a few other key provisions that bear watching:
**Retirement accounts may see new restrictions.3**
Roth conversions would be eliminated for individuals earning above $400,000.
Folks in that income bracket would also be prohibited from contributing to retirement accounts with an aggregate value over $10 million the prior tax year.
Another critical change that would affect all taxpayers: The bill prohibits all employee after-tax contributions to qualified plans and prohibits after-tax IRA contributions from being converted to Roth, thus potentially eliminating backdoor Roth conversion strategies.
**Estate planning may get more complicated.3**
Good news first: The “step-up” in tax basis on death is staying and the “deemed realization” rule that would trigger capital gains taxes on death is not included.
However, the estate tax exemption would revert from $11.7 to $5 million.
The deal would also eliminate certain tax benefits of “grantor trusts” as well as limit valuation discounts on non-business assets.
Currently, these provisions would apply only to future trusts and transactions that happen after the effective date of the law.
**How likely are all these measures to pass?**
Here’s where we start speculating.
To pass the American Families Plan using budget reconciliation, President Biden needs the votes from his entire party.
Progressives are committed to passing the full deal but centrists are balking at the price tag.1
To get through the Senate, it seems like both sides will meet somewhere in the middle.
A lower final cost to the bill would require less revenue to cover and might allow some of the tax increases to be eliminated.
Since the IRS has been targeting Roth conversions and large IRAs, it’s possible that those measures may pass.
**When could the new laws go into effect?**
It seems likely that most provisions would be effective on January 1, 2022 and apply going forward (not retroactively). However, separate deadlines could be negotiated for certain provisions.
**Bottom line: Laws change. We adapt.**
Here are the usual caveats:
We don’t know what the final bills will look like and when (or if) they will pass.
Taxes are just one part of your overall picture.
New laws usually contain a mix of positive and negative changes for you, me, and everyone else.
The long-term impact of the positives and the negatives won’t be visible for some time.
**Have questions you haven’t asked me or concerns you haven’t raised? Please reach out.**
If I see moves that I’d like you to make before year-end, I’ll contact you directly.
Sincerely,
**Goran Ognjenovic**
Independent Investment Advisors
(971) 350-8068
[www.independentadvisorsnw.com](https://independentadvisorsnw.com)
---
P.S. I’m also keeping an eye on the debt ceiling debate happening right now. I’ll update you if it’s needed.
1
2 [https://www.schwab.com/resource-center/insights/content/will-taxes-rise-wealthy-what-you-should-know](https://www.schwab.com/learn/topic/taxes)
3 [https://www.foley.com/en/insights/publications/2021/09/democrats-introduce-tax-proposals](https://www.foley.com/insights/publications/2021/09/democrats-introduce-tax-proposals/)
This information is not intended to be a substitute for specific individualized tax advice. We suggest that you discuss your specific tax issues with a qualified tax professional.
The following posts and commentary are to be used solely as educational tools and do not contain investment advice. Investment advice must be tailored to a particular investor’s specific needs. None of the information contained should be construed to be investment advice. Individuals wishing to tailor a plan to their own needs should seek the help of a Registered Investment Advisor.
There is a high degree of risk in investing and trading. Independent Investment Advisors assumes no responsibility. Principles of Independent Investment Advisors may, at times, maintain directly or indirectly, positions in securities or derivatives mentioned in these comments.

Investment Advisor
[See Full Bio](https://independentadvisorsnw.com/author/investment-advisor/) [ ](https://independentadvisorsnw.com/author/investment-advisor/)
**Categories:** All Posts
---
### [Storms ahead? What you need to know](https://independentadvisorsnw.com/storms-ahead-what-you-need-to-know/)
**Published:** September 24, 2021
**Author:** Investment Advisor
**Excerpt:** The stock market got a little crazy this week.
Is a storm coming?
Let's take a look at what's driving markets right now.
(Scroll to the end if you just want my takeaways.)
**Content:**
[< back to Market Insights Blog](https://independentadvisorsnw.com/homepage/markets-insights/)
The stock market got a little crazy this week.
Is a storm coming?
Let’s take a look at what’s driving markets right now.
*(Scroll to the end if you just want my takeaways.)*
A few things are driving the market volatility:
**Fears of a financial crisis in China.**
China’s overheated real estate bubble is starting to pop and Evergrande, a giant Chinese property developer, is heading toward defaulting on more than $300 billion in debt.1
Its failure could trigger a cascade of defaults among banks, materials suppliers, and investors, potentially leading to broader financial issues in China and abroad.
**Worries the Federal Reserve will start tapering soon.**
The Fed meets this month and traders are uneasy about the idea that the central bank could start pulling back the support now that inflation is higher and the jobs market has improved.2 Firms that depend on low interest rates and easy credit could be hurt.
**Concerns about COVID-19 case numbers.**
Variants continue to pop up and the delta variant continues to keep cases and hospitalizations high. Investors are concerned that another winter resurgence (like we saw last year) could slow down business and economic activity.3
**Fears of another debt ceiling showdown.**
Once an ordinary part of federal accounting, adjusting the debt ceiling is now a political negotiation, threatening the Treasury Department’s ability to pay its bills next month.
Though it’s unlikely either party will allow the U.S. to default on its obligations, this political brinksmanship adds anxiety each time it comes up. Another government shutdown could exacerbate political risks to markets.4
**Do you see a trend? Markets are being driven by fear, anxiety, and doubt.**
Which of these squalls will fade away and which could blow into a tempest?
We can’t know.
So, here’s the real question:
**Goran, could we see a 10%+ correction in the weeks or months ahead?**
Possibly.
Corrections and pullbacks happen regularly and it wouldn’t be surprising to see a market drop.
To show you just how ordinary corrections are, here’s a chart that shows intra-year dips in the S&P 500 alongside annual performance.
*(Take a look at the red circles to see the market drops each year.)*
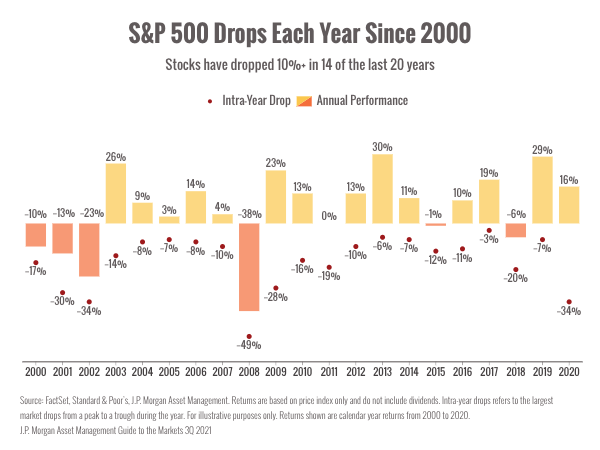The big takeaway? In 14 of the last 20 years, markets have dropped at least 10%.5
Even years with strong performance saw big drops.
We’re dealing with a lot of uncertainty and investors are feeling understandably cautious about what’s ahead.
**But, that doesn’t mean that we should panic and rush for the exits.**
Pullbacks, corrections, and even downturns don’t last forever.
Trust the process. Trust the strategy.
I’m keeping an eye on the Chinese property market situation, as well as workings over in Washington. I can’t predict which way markets will go in the coming weeks, but I’ll be in touch as needed.
Have questions? Feeling uneasy? Please reach out. That’s what I’m here for.
Warmly,
**Goran Ognjenovic**
Independent Investment Advisors
(971) 350-8068
[www.independentadvisorsnw.com](https://independentadvisorsnw.com)
---
P.S. This email was originally going to be about updates to the tax legislation negotiations, but the market turmoil took precedence. I’ll be in touch on taxes when we know more about how the politics could play out.
P.P.S. Some folks handle stressful situations better than others. What helps you keep your cool when things get turbulent? I’d love to hear. Just hit “reply” and let me know.
1
2
3
4
5
This information is not intended to be a substitute for specific individualized tax advice. We suggest that you discuss your specific tax issues with a qualified tax professional.
The following posts and commentary are to be used solely as educational tools and do not contain investment advice. Investment advice must be tailored to a particular investor’s specific needs. None of the information contained should be construed to be investment advice. Individuals wishing to tailor a plan to their own needs should seek the help of a Registered Investment Advisor.
There is a high degree of risk in investing and trading. Independent Investment Advisors assumes no responsibility. Principles of Independent Investment Advisors may, at times, maintain directly or indirectly, positions in securities or derivatives mentioned in these comments.

Investment Advisor
[See Full Bio](https://independentadvisorsnw.com/author/investment-advisor/) [ ](https://independentadvisorsnw.com/author/investment-advisor/)
**Categories:** All Posts
---
### [Taper tantrum part deux?](https://independentadvisorsnw.com/taper-tantrum-part-deux/)
**Published:** September 2, 2021
**Author:** Investment Advisor
**Excerpt:** Could the Fed's actions cause a correction or economic slowdown?
Let's discuss.
First of all, what does ”tapering” mean?
In econ-speak, tapering means winding down the pace of the assets Fed has been buying since last summer.
**Content:**
[< back to Market Insights Blog](https://independentadvisorsnw.com/homepage/markets-insights/)
**Could the Fed’s actions cause a correction or economic slowdown?**
Let’s discuss.
First of all, what does ”tapering” mean?
In econ-speak, tapering means winding down the pace of the assets Fed has been buying since last summer.
**Why is it a big deal?**
Well, the last time the Fed tapered in 2013, during the recovery from the 2008 financial crisis, markets panicked and pitched a “taper tantrum.”2
That’s because traders worried that less Fed support would hurt fundamentals and potentially cause a market downturn.
Now, that old taper tantrum narrative is making folks worry that another market downturn could be ahead of us, especially with concerns about the delta variant.
Before we dive into what could happen, let’s talk about where we are and how we got here.
When the pandemic started, the Fed slashed interest rates and began buying $120 billion a month in bonds and mortgage-backed securities to reduce interest rates, lower borrowing costs, and give businesses and the economy a boost.1
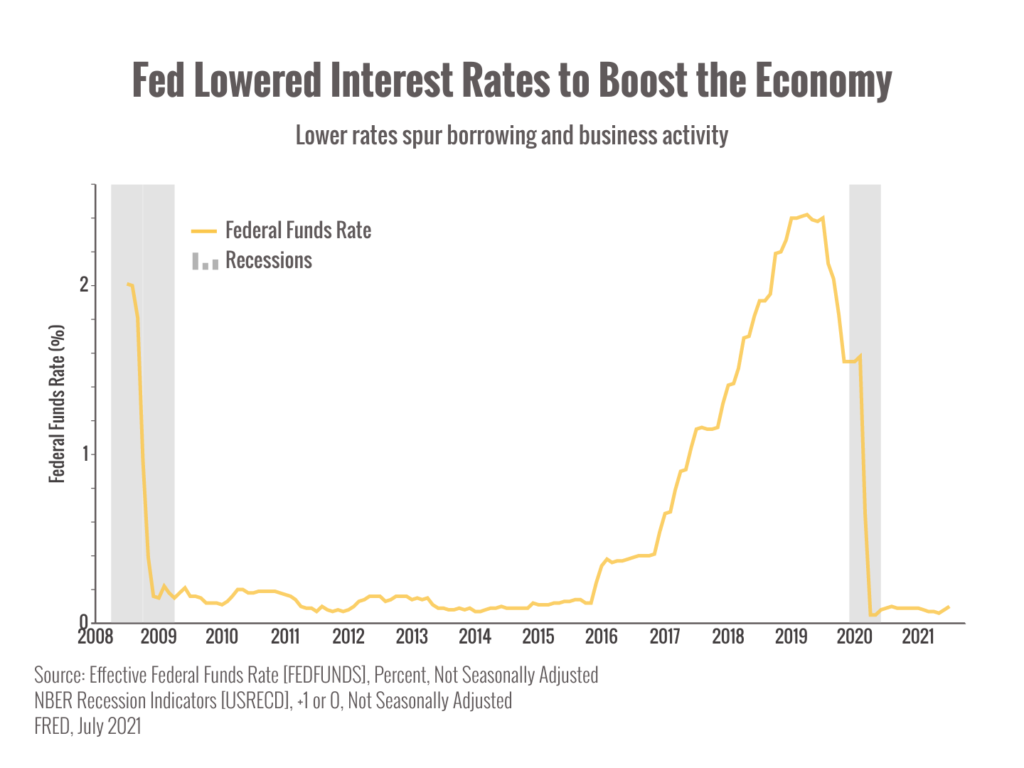However, now that the economy is much stronger, the employment situation has improved, and inflation is a concern, the Fed wants to start paring back those asset purchases to return interest rates to a more “natural” level.
**What could that look like?**
Obviously, we don’t know exactly when or how the Fed will decide to act, but analysts have some pretty good guesses.
The latest prediction by Bank of America suggests tapering could start this November as the Fed gradually pares back asset purchases through next year.1
The takeaway is that the Fed isn’t going to stop buying assets and raise interest rates immediately.
It’s going to gradually remove the support and see how the economy reacts.
**So, will we see another taper correction?**
The main reason folks worry about Fed reducing support is because of the effect higher interest rates could have on stocks, particularly companies that rely on borrowed money.
However, interest rates are just one piece of the puzzle. Economic fundamentals, earnings, and other factors also weigh on stock prices.
With the benefit of hindsight, we can see that the 2013 taper tantrum wasn’t even that bad. The S&P 500 tumbled 5.8% over the course of a month but quickly recovered (the caveat here is always this: the past does not predict the future).2
I think the main reason markets declined last time was that investors hadn’t experienced tapering before; they didn’t have context for what the Fed would do.
Since we’ve seen this happen before fairly recently, I think that uncertainty is lessened.
However, we also have other worries to consider: a deteriorating crisis in Afghanistan, continued pandemic worries, and political wrangling over infrastructure.
Any of these factors could derail the bull market.
But it’s not going to be the end of the world.
**Corrections are always something we should expect. They happen regularly and are a natural part of markets.**
The Fed is one more thing I’m keeping an eye on, and I’ll reach out if there’s more you should know.
Be well,
**Goran Ognjenovic**
Independent Investment Advisors
(971) 350-8068
[www.independentadvisorsnw.com](https://independentadvisorsnw.com)
---
P.S. What’s something new or exciting in your world? Do you mind sharing it with me?
1
2
The following posts and commentary are to be used solely as educational tools and do not contain investment advice. Investment advice must be tailored to a particular investor’s specific needs. None of the information contained should be construed to be investment advice. Individuals wishing to tailor a plan to their own needs should seek the help of a Registered Investment Advisor.
There is a high degree of risk in investing and trading. Independent Investment Advisors assumes no responsibility. Principles of Independent Investment Advisors may, at times, maintain directly or indirectly, positions in securities or derivatives mentioned in these comments.

Investment Advisor
[See Full Bio](https://independentadvisorsnw.com/author/investment-advisor/) [ ](https://independentadvisorsnw.com/author/investment-advisor/)
**Categories:** All Posts, Investment Advisor
---
### [We've come so far!](https://independentadvisorsnw.com/weve-come-so-far/)
**Published:** August 16, 2021
**Author:** Investment Advisor
**Excerpt:** Headlines are looking grim again, so let's pause and take stock.
Why are the headlines terrible?
Because the media loves drama. This is not news to you or me or anyone who pays attention.
**Content:**
[< back to Market Insights Blog](https://independentadvisorsnw.com/homepage/markets-insights/)
Headlines are looking grim again, so let’s pause and take stock.
Why are the headlines terrible?
Because the media loves drama. This is not news to you or me or anyone who pays attention. The 24-hour news cycle is there to whip up emotions and keep us glued to the latest “BREAKING NEWS.”
So, what’s behind the noise and should we worry?
**Before we jump into unpacking the news, let’s take a moment and remind ourselves of how far we’ve come since the pandemic began.**
You can see it right here in this chart:
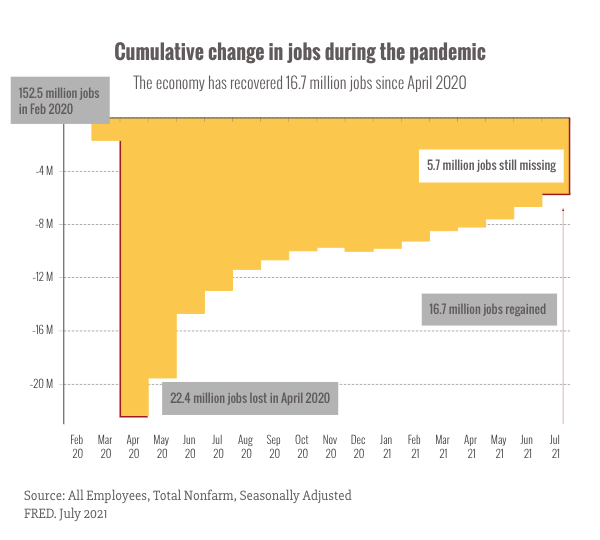We’ve recovered the vast majority of jobs lost since the bottom of the pandemic’s disruption last April. The economy is still missing several million jobs to regain pre-pandemic levels, but we’ve made up a lot of ground, and jobs growth is still strong.1
In fact, there are more job openings right now than job seekers to fill them.2
**But there’s an important caveat to the chart above.**
The monthly jobs report is what economists call a *“lagging”* indicator, meaning that it’s telling us where the economy was, not where it’s going.
To figure out what might lie ahead, economists turn to *“leading”* economic indicators that help forecast future trends.
So, what are the leading indicators telling us about the economy?
A couple of the most popular indicators are manufacturing orders for long-lasting (durable) goods, since companies don’t like to order expensive equipment unless they expect to need soon.
Another one is groundbreaking (starts) on new houses, which indicate how much demand builders expect for housing.
Let’s take a look:
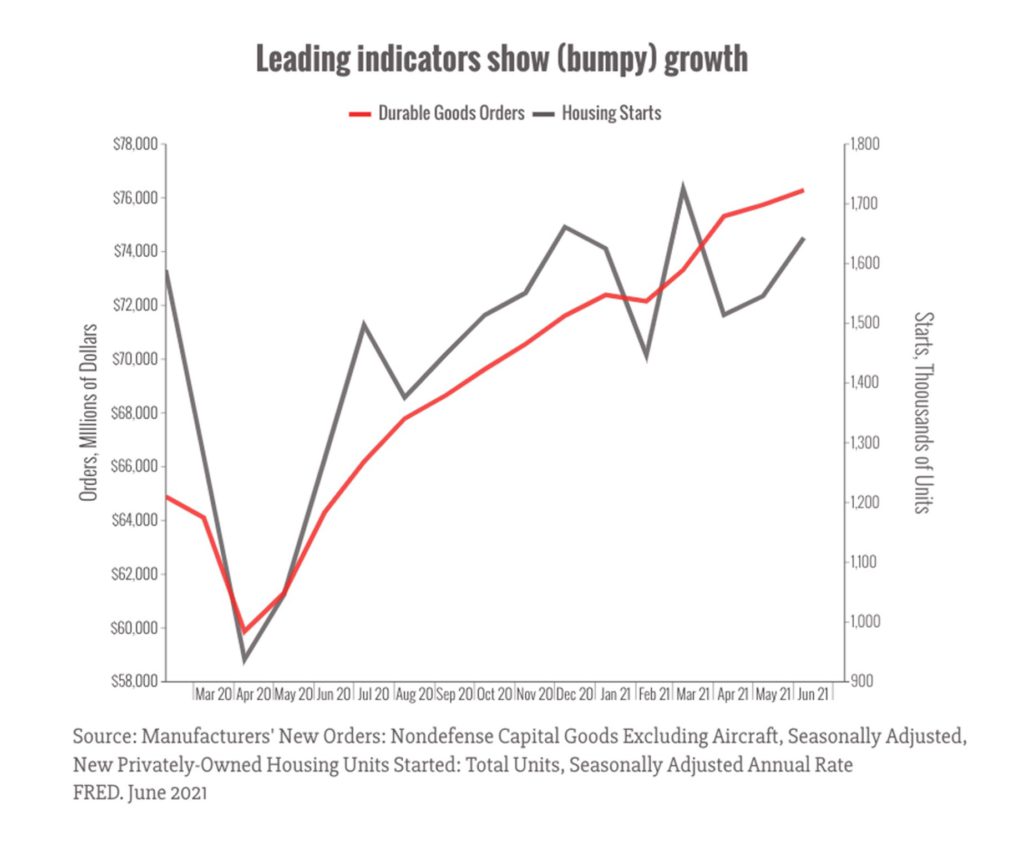Both indicators suggest continued (if bumpy) growth. Now, those are just two sectors, and we want to be thorough, so let’s take a look at a composite.
The Conference Board Leading Economic Index (LEI) gives us a quick overview each month of several indicators.
It increased by 0.7% in June, following a 1.2% increase in May, and a 1.3% increase in April, showing broad, but slowing growth.3
What does that tell us? That the economy still has legs.
**Will the delta variant derail the recovery?**
A serious slowdown due to the delta variant seems unlikely, but we could potentially see a bumpy fall, especially in vulnerable industries and areas with surging case counts.
There’s also some potentially good news about the delta variant that we can take from other countries.
India and Great Britain both experienced delta-driven surges earlier this summer.4
And what happened?
A steep and scary rise in case counts and hospitalizations…followed by a rapid decline.
It seems that these fast-moving delta waves might burn themselves out.
Unfortunately, these surges come with a painful human cost to patients, overburdened medical staff, communities, and families.
But, if this pattern holds true in the U.S., it doesn’t appear that the economic impact will be heavy enough to derail the recovery.
All this to say, it’s clear that the pandemic is still not over.
But we’ve come such a long way since the darkest days of 2020 and the road ahead still seems bright (if a little potholed).
Please remember to take panicky headlines with a shaker or two of salt.
I’m here and I’m keeping watch for you.
Have questions? Please reach out.
Be well,
**Goran Ognjenovic**
Independent Investment Advisors
(971) 350-8068
[www.independentadvisorsnw.com](https://independentadvisorsnw.com)
---
P.S. The bipartisan infrastructure deal is still making its way through Congress, and we don’t yet know what the final details will look like. The Democrat-led infrastructure deal is also in the works, but we’re not likely to see serious movement until the fall. I’ll keep updating you as I know more.
1
2
3 [https://conference-board.org/pdf\_free/press/US%20LEI%20PRESS%20RELEASE%20-%20July%202021.pdf](https://www.conference-board.org/pdf_free/press/US%20LEI%20PRESS%20RELEASE%20-%20July%202021.pdf)
4
The following posts and commentary are to be used solely as educational tools and do not contain investment advice. Investment advice must be tailored to a particular investor’s specific needs. None of the information contained should be construed to be investment advice. Individuals wishing to tailor a plan to their own needs should seek the help of a Registered Investment Advisor.
There is a high degree of risk in investing and trading. Independent Investment Advisors assumes no responsibility. Principles of Independent Investment Advisors may, at times, maintain directly or indirectly, positions in securities or derivatives mentioned in these comments.

Investment Advisor
[See Full Bio](https://independentadvisorsnw.com/author/investment-advisor/) [ ](https://independentadvisorsnw.com/author/investment-advisor/)
**Categories:** All Posts, Investment Advisor
---
### [A tale of two infrastructure deals](https://independentadvisorsnw.com/a-tale-of-two-infrastructure-deals/)
**Published:** July 2, 2021
**Author:** Investment Advisor
**Excerpt:** After weeks of grandstanding, posturing, and wrangling, it looks like a bipartisan infrastructure deal that both parties can live with is in the works.
**Content:**
[< back to Market Insights Blog](https://independentadvisorsnw.com/homepage/markets-insights/)
It appears we have a deal on infrastructure.
Maybe.
After weeks of grandstanding, posturing, and wrangling, it looks like a bipartisan infrastructure deal that both parties can live with is in the works.
Good news: no tax hikes. But you’ll want to read on because we’re not out of the woods yet.
**Before we dive in, I want to wish you a very happy Fourth of July. Wherever you are, and whoever you’re able to spend it with, I sincerely hope it’s fun, relaxing, and meaningful.**
Now, onto the politics.
The bipartisan deal (can’t call it a bill yet) finds $579 billion of common ground from President Biden’s original $2.25 trillion American Jobs Plan.1
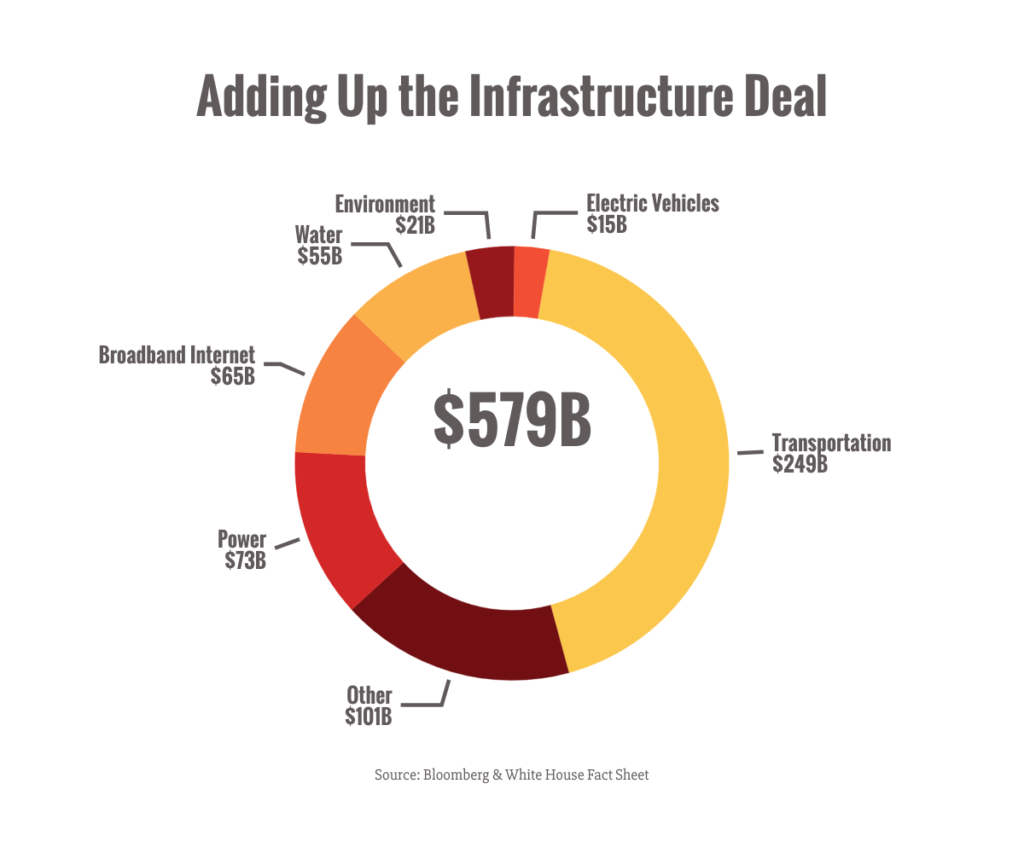It focuses on “hard” infrastructure — such as roads, bridges, rail, and public transit projects, as well as electric vehicle infrastructure and broadband internet — that both sides can agree on.
**So, is it a done deal?**
Not even close.
The current framework represents a compromise that makes no one happy, and there’s still a fair bit to hammer out (including how to pay for the plan).
The deal still needs to gather broad support in both parties, especially among those who think it’s too little or too much and might seek to scuttle the whole thing.
Fortunately, it doesn’t look like higher taxes are part of the deal. Though the math looks a little fuzzy from where I’m standing, it looks like funding sources could include repurposed pandemic funding, better IRS enforcement, and possibly digging through couch cushions for spare change (joking).1
**So, that means my taxes won’t go up, right?**
Not so fast.
There’s another bill on the table. And it’s a $1.8 trillion doozy.2
The second bill, called the American Families Plan, focuses on so-called “human” infrastructure and contains many Democrat-backed priorities like childcare, climate change, health care, and education.3
Basically, the initiatives that couldn’t get Republican support are packaged up in a separate bill.
It looks like the Democrats are planning to pass that bill through a reconciliation process that doesn’t require Republican support to get through Congress.
Inside that bill are the tax increases we’ve been on the watch for. Higher taxes on wealthy individuals and corporations, as well as eliminating the step-up basis on inherited assets, among other tax hits.4
Since the bills are independent, it’s really not certain yet which (if either) will pass. Or when.
Will one pass and not the other? Will both grind to a halt this summer?
Hard to say.
**What does all this mean?**
That depends on where you’re standing. For industries expecting to benefit, it means an influx of tasty government cash.
For those worried about America’s crumbling infrastructure, it represents some critical moves in the right direction.
For those concerned about the spending spree the government’s been on (and how we’re going to pay for it all), it’s another brick in a looming wall of debt that will eventually come due.
Bottom line, it’s not nearly over yet. I strongly suspect the coming weeks will be full of more politicking, more grandstanding, and more arm twisting.
I’ll reach out when I know more.
Now, go enjoy your summer. You deserve it.
Infrastructurally yours,
**Goran Ognjenovic**
Independent Investment Advisors
(971) 350-8068
[www.independentadvisorsnw.com](https://independentadvisorsnw.com)
---
1
2
3
4[https://taxfoundation.org/american-families-plan/](https://taxfoundation.org/research/all/federal/american-families-plan/)
Chart source:
This information is not intended to be a substitute for specific individualized tax advice. We suggest that you discuss your specific situation with a qualified tax professional.
The following posts and commentary are to be used solely as educational tools and do not contain investment advice. Investment advice must be tailored to a particular investor’s specific needs. None of the information contained should be construed to be investment advice. Individuals wishing to tailor a plan to their own needs should seek the help of a Registered Investment Advisor.
There is a high degree of risk in investing and trading. Independent Investment Advisors assumes no responsibility. Principles of Independent Investment Advisors may, at times, maintain directly or indirectly, positions in securities or derivatives mentioned in these comments.

Investment Advisor
[See Full Bio](https://independentadvisorsnw.com/author/investment-advisor/) [ ](https://independentadvisorsnw.com/author/investment-advisor/)
**Categories:** All Posts, Investment Advisor
---
### [Getting it wrong?](https://independentadvisorsnw.com/getting-it-wrong/)
**Published:** June 24, 2021
**Author:** Investment Advisor
**Excerpt:** What happens when the predictions are wrong? Is it time to panic? Is it time to ditch our strategy? It's a fascinating question because it cuts right down to the question of what it means to live in an uncertain world.
**Content:**
[< back to Market Insights Blog](https://independentadvisorsnw.com/homepage/markets-insights/)
What happens when the predictions are wrong?
Is it time to panic?
Is it time to ditch our strategy?
It’s a fascinating question because it cuts right down to the question of what it means to live in an uncertain world.
**Humans are wired to dislike uncertainty.1**
And we’re used to a fair amount of (often unwarranted) certainty in the models and paradigms we use to make sense of the world around us.
We’re so attracted to certainty that when economic forecasts and reports come back with “surprises” (also known as being wrong) we tend to freak out.
Especially when the news trumpets every weird bit of data like it’s a huge deal.
Over the last few weeks and months, we’ve had a lot of “surprise” reports.
Inflation surprises.
Job market surprises.
Housing market surprises.
Economic growth surprises.
**Why are we so surprised?**
In a year like 2021, the margin for error is greater than ever.
Predictions, forecasts, and expectations that are based on averages, trends, and other backward-looking methods are ill-equipped to handle the outliers and oddities of a year that’s unlike anything that has come before.
**When in history has an entire global economy simply come to a halt?**
And then arthritically restarted with many creaks and groans.
To my knowledge, it’s never happened before.
Of course the data is going to have surprises.
We’re probably going to get a lot of things wrong.
I can’t wait for the best-sellers written about all the ways we could have done things better.
**So. What does that mean for you and me?**
Crystal balls are out of commission.
Surprise is the order of the day, the week, and the year.
The models haven’t caught up yet (though that’s not stopping anyone from issuing very confident predictions).
So we’re being careful and looking out for the opportunities (as well as the hidden pitfalls) in these uncharted waters.
We’re cultivating patience, gratitude, and our ability to make good decisions with incomplete information.
To staying frosty,
**Goran Ognjenovic**
Independent Investment Advisors
(971) 350-8068
[www.independentadvisorsnw.com](https://independentadvisorsnw.com)
P.S. So many folks are making big life changes. Are you? Anything you’re excited to share? Hit “reply” and let me know.
1
Risk Disclosure: Investing involves risk including the potential loss of principal. No investment strategy can guarantee a profit or protect against loss in periods of declining values. Past performance does not guarantee future results.
This material is for information purposes only and is not intended as an offer or solicitation with respect to the purchase or sale of any security. The content is developed from sources believed to be providing accurate information; no warranty, expressed or implied, is made regarding accuracy, adequacy, completeness, legality, reliability or usefulness of any information. Consult your financial professional before making any investment decision. For illustrative use only.
The following posts and commentary are to be used solely as educational tools and do not contain investment advice. Investment advice must be tailored to a particular investor’s specific needs. None of the information contained should be construed to be investment advice. Individuals wishing to tailor a plan to their own needs should seek the help of a Registered Investment Advisor.
There is a high degree of risk in investing and trading. Independent Investment Advisors assumes no responsibility. Principles of Independent Investment Advisors may, at times, maintain directly or indirectly, positions in securities or derivatives mentioned in these comments.

Investment Advisor
[See Full Bio](https://independentadvisorsnw.com/author/investment-advisor/) [ ](https://independentadvisorsnw.com/author/investment-advisor/)
**Categories:** All Posts, Financial Planning, Investment Advisor
---
### [Is the sky falling (again)?](https://independentadvisorsnw.com/is-the-sky-falling-again/)
**Published:** July 23, 2021
**Author:** Investment Advisor
**Excerpt:** There's a lot going on in the world right now.
I thought this note was going to be about the $3.5 trillion budget deal or what to do with any child tax credits that may be heading your way.
But then global markets jolted on fears of new viral variants.
Is the sky actually falling?
**Content:**
[< back to Market Insights Blog](https://independentadvisorsnw.com/homepage/markets-insights/)
There’s a lot going on in the world right now.
I thought this note was going to be about the $3.5 trillion budget deal or what to do with any child tax credits that may be heading your way.
But then global markets jolted on fears of new viral variants.
Is the sky actually falling?
Could a big correction happen?
After hitting record highs in previous days, markets tumbled Monday, sending the Dow 700+ points lower.1
Why?
Mostly fears of a COVID-19 resurgence caused by the delta variant that could derail the economic recovery.
Case numbers are rising globally, even in countries with high vaccination rates, and the surge could lead to a return to travel restrictions and business closures.2
Could these market jitters cause a 10%+ correction?
Absolutely.
**Should we panic and freak out?**
Definitely not.
Here are a couple of reasons why:
Summer months can bring higher volatility, perhaps because of lower trading volume, making bad news shake the market harder.3
We’ve had a pretty long winning streak, and corrections are part and parcel of a healthy market, especially when we’re near all-time highs.
New variants and higher case counts are a threat. However, vaccination rates are continuing to rise, and experts don’t think that we’ll see the devastating health outcomes we saw last year.4
**Could the delta variant cause the economy to slow down?**
It’s hard to say at this point. The rosy projections about the economy have been based on a swift return to normal from the shortest recession in history.5
If surging case counts cause a resumption of business and travel limits, we could definitely see a hit, especially in recovery-dependent industries like airlines, cruises, and hotels.
Supply chain issues are still causing materials shortages, creating delivery delays of goods, and potentially triggering slowdowns in industries such as building and construction.6
However, consumer spending is still very strong and the economy is in way better shape than it was last year.7
Bottom line: we could see some economic complications due to the delta variant and we’re likely to see more market volatility ahead, especially if economic data disappoints.
I’m keeping an eagle eye on the trends and will be in touch with you personally if your strategy needs to change.
Have questions? Please reach out. I’m always here to help.
Calmly,
**Goran Ognjenovic**
Independent Investment Advisors
(971) 350-8068
[www.independentadvisorsnw.com](https://independentadvisorsnw.com)
---
P.S. A massive $3.5 trillion budget deal is working its way through Congress.8 It’s got a lot of moving parts that may affect taxes, Medicare, and much more. I’ll reach out when we know more about how it’s likely to shake out.
1
2
3
4[https://www.nature.com/articles/d41586-021-01696-3](https://www.nature.com/articles/d41586-021-01696-3?error=cookies_not_supported&code=0386c826-03a7-41d5-ab61-efe19e24eba2)
5
6
7
8
This information is not intended to be a substitute for specific individualized tax advice. We suggest that you discuss your specific tax issues with a qualified tax professional.
The following posts and commentary are to be used solely as educational tools and do not contain investment advice. Investment advice must be tailored to a particular investor’s specific needs. None of the information contained should be construed to be investment advice. Individuals wishing to tailor a plan to their own needs should seek the help of a Registered Investment Advisor.
There is a high degree of risk in investing and trading. Independent Investment Advisors assumes no responsibility. Principles of Independent Investment Advisors may, at times, maintain directly or indirectly, positions in securities or derivatives mentioned in these comments.

Investment Advisor
[See Full Bio](https://independentadvisorsnw.com/author/investment-advisor/) [ ](https://independentadvisorsnw.com/author/investment-advisor/)
**Categories:** All Posts, Investment Advisor
---
### [Tax worries? Info inside...](https://independentadvisorsnw.com/tax-worries-info-inside/)
**Published:** June 15, 2021
**Author:** Investment Advisor
**Excerpt:** Are you tired of hearing about taxes? Me too! But here we are. Let’s dive in. So, we’ve got dueling infrastructure bills, plus a big proposed budget with lots of spending (and higher taxes inside). That’s a lot of expensive legislation on the table.
**Content:**
[< back to Market Insights Blog](https://independentadvisorsnw.com/homepage/markets-insights/)
## Tax worries? Info inside…
Are you tired of hearing about taxes?
Me too! But here we are. Let’s dive in.
So, we’ve got dueling infrastructure bills, plus a big proposed budget with lots of spending (and higher taxes inside).
That’s a lot of expensive legislation on the table.
**What’s going to happen next?**
The Democrats and Republicans seem pretty far apart on their respective infrastructure deals, which opens up the possibility that Democrats could go it alone and try to pass a package entirely without Republican support.1
That would be very difficult to accomplish.
It’s also possible that both parties could align around a smaller bill and then the Democrats attempt to pass any extras through budget reconciliation.
Bottom line, we don’t have enough clarity to know what a final infrastructure deal will look like. Given the political hurdles, the debate might drag on through summer.2
**How likely are taxes to go up?**
Well, my crystal ball’s about as clear as mud right now, but let’s break down what we see on the table.
President Biden’s $6 trillion proposed budget offers a lot of spending and higher taxes to pay for it.3 None of these tax hikes are a surprise as they are in line with what Biden has promised before.
Wealthy taxpayers are looking at a higher top income tax rate, higher capital gains taxes, and the loss of the step-up basis on inherited assets.
Corporations are also in the line of fire, facing an increase in corporate tax rates, which could affect profitability.
That’s currently what’s on the table.
However, Biden’s desire to raise taxes faces major headwinds (even inside his own party). His proposed budget is very much a wish list and will face challenges getting approved by legislators.4
It’s very possible that some (or all) of these proposed tax hikes will get axed during negotiations.
**How likely is it that any tax hikes will be retroactive?**
One of the big shockers coming out of recent tax news is that the higher capital gains taxes could be made retroactive to April 2021.5
There is historical precedent for this as it has happened a number of times before.6 However, retroactive tax changes are often for tax *decreases*.
I think it’s very unlikely for an *increase* to be retroactive. There is too much opposition from both sides of the aisle.
Bottom line, I do think that higher taxes are coming. But I’m not sure that they will be as big or far-reaching as the Biden administration wants.
**With so much uncertainty around taxes, now is not a time to panic, but to think carefully and make adjustments where needed.**
I’ll reach out if there’s anything specific we need to discuss.
Yours in tax uncertainty,
**Goran Ognjenovic**
Independent Investment Advisors
(971) 350-8068
[www.independentadvisorsnw.com](https://independentadvisorsnw.com)
---
P.S. There’s a lot going on in the economy and Washington. I’ll keep you updated along the way, but if you have any questions or concerns, please reach out. That’s why I’m here.
1
2 [https://www.rollcall.com/2021/05/28/budget-release-starts-a-process-that-will-run-through-summer/](https://rollcall.com/2021/05/28/budget-release-starts-a-process-that-will-run-through-summer/)
3
4
5
6
This information is not intended to be a substitute for specific individualized tax advice. We suggest that you discuss your specific tax issues with a qualified tax professional.
The following posts and commentary are to be used solely as educational tools and do not contain investment advice. Investment advice must be tailored to a particular investor’s specific needs. None of the information contained should be construed to be investment advice. Individuals wishing to tailor a plan to their own needs should seek the help of a Registered Investment Advisor.
There is a high degree of risk in investing and trading. Independent Investment Advisors assumes no responsibility. Principles of Independent Investment Advisors may, at times, maintain directly or indirectly, positions in securities or derivatives mentioned in these comments.

Investment Advisor
[See Full Bio](https://independentadvisorsnw.com/author/investment-advisor/) [ ](https://independentadvisorsnw.com/author/investment-advisor/)
**Categories:** All Posts, Financial Planning, Investment Advisor
---
### [$50 burgers (should we worry about inflation?)](https://independentadvisorsnw.com/50-burgers-should-we-worry-about-inflation/)
**Published:** May 31, 2021
**Author:** Investment Advisor
**Excerpt:** How much inflation can the country afford before we’re in trouble?
Let’s discuss. First, let’s get on the same page about some basics.
**Content:**
[< back to Market Insights Blog](https://independentadvisorsnw.com/homepage/markets-insights/)
## $50 burgers (should we worry about inflation?)
How much inflation can the country afford before we’re in trouble?
Let’s discuss.
First, let’s get on the same page about some basics.
If you’ve noticed the price of a thing increasing over time (say, your favorite candy bar or the cost of college tuition), that’s inflation in action.
Economists use the broad increase (or decrease) in prices of goods and services across the country as a measure of economic health.
When inflation is stable and predictable, it’s a sign of a basically healthy, growing economy.
**But, high inflation can quickly eat away at the purchasing power of your dollars, indicating that the economy might be overheated.**
Deflation, or a decline in prices, can be a warning sign of a shrinking economy.
Recent data highlighted a surprise spike in inflation, indicating that prices increased faster than economists expected last month.1
**Could this be a worrisome sign that the economy is overheated? Could $50 burgers be in our future?**
Maybe.
On the other hand, could it be a temporary blip caused by the economy emerging from the pandemic-driven slowdown, complicated by supply chain issues?
Very possible.
**Are the headlines catastrophizing?**
They usually are.
Let’s look at the data.
The Consumer Price Index (CPI), one of the major indexes economists use to track inflation, showed a surprising spike in April, igniting fears of runaway inflation.
Core CPI (which excludes the highly volatile categories of energy and food) showed a 0.9% increase in April month-over-month and 3.0% year-over-year. That’s much higher than the expected 0.3% and 2.3%, respectively.1
However, digging a bit deeper, we see that just two categories of goods (used cars and transportation services) accounted for the vast majority of the surge.2
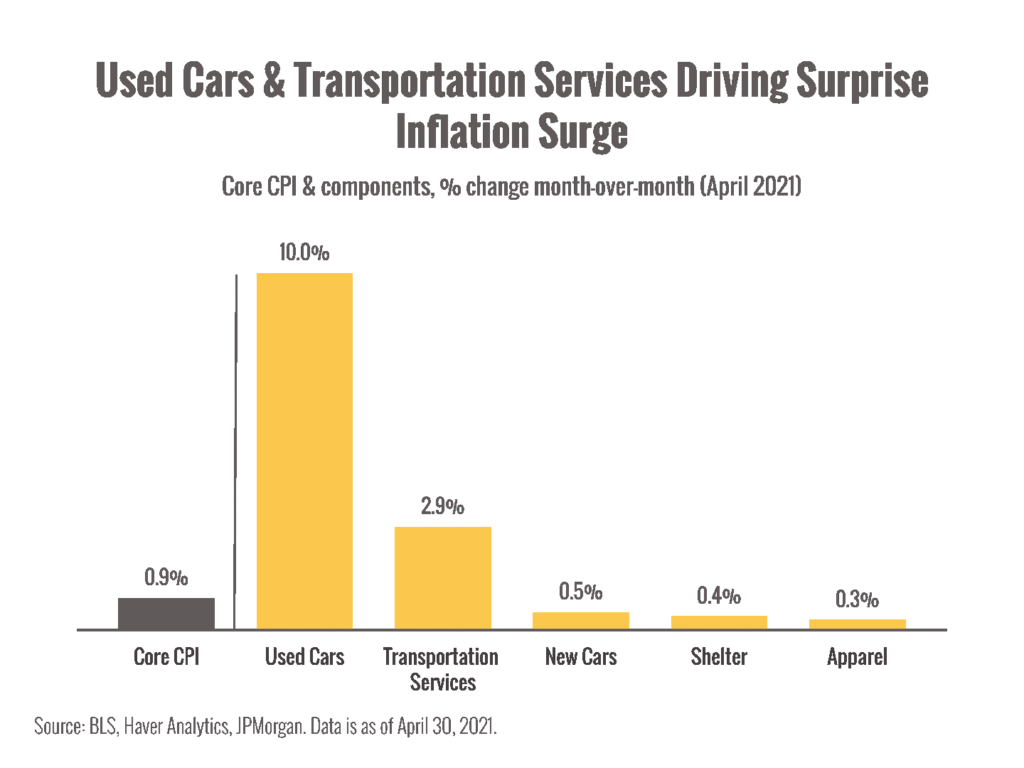That suggests things like flights and train travel suddenly became more expensive after a year of rock-bottom prices.
Is that runaway inflation or the normalization of prices as the world reopens?
We can’t tell from a single data point, but it’s not unusual to see prices increase in sectors that experienced a severe slowdown last year.
And the jump in used car prices? Well, many folks are turning to the second-hand market right now, in part because new cars are caught up in global supply chain bottlenecks for things like semiconductors and raw materials.3
Inflation is something to keep an eye on, especially in a year when so many of the usual variables have been thrown into flux. An ongoing surge in prices could hurt our wallets as our dollars buy less over time.
However, a single monthly spike following a very weird period for the economy is not cause for alarm yet; we should prepare ourselves for more odd numbers coming out of different parts of the economy in the weeks and months to come.
Shortages of everything from ketchup to gasoline could lead to price increases and fluctuations as supply chains attempt to disentangle from pandemic disruptions.4
**Should we expect markets to react to inflation (and other) headlines?**
A negative market reaction is not surprising after weeks of strong performance. We should expect volatility ahead as we (and the economy) adjust to a post-pandemic world.
Bottom line: Expect the unexpected in 2021.
Yours in an odd year,
**Goran Ognjenovic**
Independent Investment Advisors
(971) 350-8068
[www.independentadvisorsnw.com](https://independentadvisorsnw.com)
---
P.S. Questions about how inflation might affect your income? Hit “reply” and ask away. I’m here.
1
2
3
4
Chart source:
The following posts and commentary are to be used solely as educational tools and do not contain investment advice. Investment advice must be tailored to a particular investor’s specific needs. None of the information contained should be construed to be investment advice. Individuals wishing to tailor a plan to their own needs should seek the help of a Registered Investment Advisor.
There is a high degree of risk in investing and trading. Independent Investment Advisors assumes no responsibility. Principles of Independent Investment Advisors may, at times, maintain directly or indirectly, positions in securities or derivatives mentioned in these comments.

Investment Advisor
[See Full Bio](https://independentadvisorsnw.com/author/investment-advisor/) [ ](https://independentadvisorsnw.com/author/investment-advisor/)
**Categories:** All Posts, Financial Planning, Investment Advisor
---
### [How Are You Lying to Yourself About Money?](https://independentadvisorsnw.com/how-are-you-lying-to-yourself-about-money/)
**Published:** May 11, 2021
**Author:** Financial Planner
**Excerpt:** Do you think you are telling yourself the truth about money? We may think we know the facts about our finances. But our beliefs can often overshadow the facts.
**Content:**
[< back to Market Insights Blog](https://independentadvisorsnw.com/homepage/markets-insights/)
## Do you think you are telling yourself the truth about money?
*Read the full web text[ here](https://independentadvisorsnw.com/).*
We may think we know the facts about our finances. But our beliefs can often overshadow the facts.
Our wishes, hopes, and fears can tip the scales away from the truth. This makes it easier for us to believe what we want to about money — and it can happen without us even realizing it.1
The money lies we tell ourselves can change the way we think and act when it comes to finances.2
And since most of us rarely talk about money with our friends and family, the money lies we tell ourselves stick around. That can lock us into destructive beliefs and reinforce poor financial habits.
But no matter what money lies we tell ourselves, it is never too late to set the record straight.
Let us look at some of the most common money lies we all buy into at some point — and the truth behind them.
## What Money Lies are You Buying into?
1. I’LL BE HAPPIER WHEN I HAVE $\_\_\_\_\_.
“With $\_\_\_ (whatever amount you think is ideal), many of my problems would go away, and I’d be happier.”
Does this sound familiar?
Goals and target numbers for earnings, savings, and budgets are great. But if you make the mistake of thinking some magic number will flip a happiness switch for you, think again.
When we tell ourselves this money lie, we put too much emotion into a single number. And we may be setting ourselves up for disappointment — both if we never get $\_\_, and if we do get $\_\_ and realize it does not make us as happy as we thought it should.
The good news? Studies show that making progress toward our goals can be incredibly satisfying, regardless of whether we hit the target.3
2\. I DESERVE IT, REGARDLESS OF WHETHER I CAN AFFORD IT.
“I work hard, and I don’t treat myself often.”
“I could kick the bucket tomorrow (YOLO).”
“I’m getting a great deal!”
These are just some of the rationalizations we use to convince ourselves that it is OK to buy something.
Whatever legs this money lie stands on, it is usually used to soothe the sting of expensive purchases — those that are not really essential — and perhaps items we know, deep down, we don’t really need.
3\. I HAVE STRONG FINANCIAL WILLPOWER.
When faced with temptation, most of us lie to ourselves that we are great at resisting it. But when was the last time you chose not to buy something you really wanted? When was the last time you made an impulse buy?
The average American spends at least a couple of hundred dollars a month on impulse purchases.4
And we’re more likely to buy on impulse, and spend more, when we’re stressed or we’re looking for a new experience.5 That’s probably why impulse spending shot up about 18% in 2020.4
Plus, the 374 million of us who are shopping with credit cards are probably spending more on the regular than we realize.6 The average credit card shopper spends about 10% more with their cards than they would with cash.7 And that is not even counting the cost of interest if the balance isn’t paid in full.
4\. I’LL SAVE MORE LATER.
Most folks focus on buying what we need and want now, and we tell ourselves we will start saving for the future later. If we save anything at all, it’s likely to be whatever we have left over.8
In fact, fewer than 1 in 6 of us are saving more than 15% of our income, and 1 in 5 are not saving any money.8
No matter the reason, when we tell ourselves this money lie and put off saving, we are prioritizing the present over the future.
That can catch up with us on a “rainy day” or whenever we do start thinking seriously about retiring. By that time, there can be a lot of heavy lifting to play “catch up” with our savings — or it may even be too late.
5\. I HAVE PLENTY OF TIME TO PLAN FOR MY FINANCIAL FUTURE (& I DON’T NEED TO THINK ABOUT IT YET).
The future can seem far away when we are looking 10, 20, or even more years out. When we feel like we have a lot of room between now and then, it is easy to make excuses to not plan or save for it.
This money lie is an excuse for procrastination.9
It is the rationale we use when we have a hard time managing our negative feelings or uncertainties about our financial futures. And it makes us turn a blind eye to the years of interest that we lose out on when we do not plan.
Benjamin Franklin may have spoken best about the truth behind this money lie when he wisely said, “by failing to prepare, you are preparing to fail.”
6\. THERE IS GOOD & BAD DEBT.
We tend to assign moral value to debt, thinking of mortgages and student loans as “good” debt, and considering credit card debt as “bad.”
This money lie gets us to think the wrong way about debt. All debt comes with some cost and it is critical to understand how every loan affects our current and future selves.
Instead of focusing on whether debt is “good” or “bad,” concentrate on the total cost of the interest over time (it is often higher than you think) and on deciding whether the loan is really helping you achieve your goals.
About half of us seem to already be on track with that thinking, saying that we expect to be out of debt within 1 to 5 years.10
7\. WANTING MORE IS BAD.
While I think we can all agree that obsessive greed is wrong, it is not a bad thing to want more for you and your loved ones.
When we tell ourselves, we should not want more than we have, we agree to settle for less. And we may be tricking ourselves into thinking it is OK that we are not doing something (or enough) to improve our financial situation.
This money lie holds us back and can make it hard to improve our financial behaviors.
When we frame wanting more as a positive motivator, it can be easier to take the chances or do the work needed to get to that next financial level we may want.
## Financial Lesson:
How to Stop Losing Out to Costly Money Lies
How many of these money lies sound like something you have told yourself?
At some point, I think we have all tricked ourselves with at least one of them.
Maybe we were rationalizing a decision, or we were trying to make ourselves feel better about what we wanted to do with our money. And we probably did not make the best financial choices as a result.
Here is the truth.
Honesty goes a long way with finances.
What we tell ourselves, and what we believe, about money influences our financial behaviors. If we are not telling ourselves the truth, our money lies won’t just drain our wallets. They can affect our financial awareness and inflate our confidence. And they get in the way of maintaining or growing wealth.11
When we recognize the money lies that we believe, we can reset our thinking, change our mindset, and start taking action. And that sets us up to make better choices and make more progress toward our big financial goals.
### SOURCES & DISCLOSURES
1 –
2 –
3 –
4 –
5 –
6 – [https://www.creditcards.com/credit-card-news/ownership-statistics/](https://www.creditcards.com/statistics/ownership-statistics/)
7 –
8 –
9 –
10 –
11 – [https://www.pnas.org/content/108/Supplement\_3/15655](https://www.pnas.org/content/108/Supplement_3/15655)
Risk Disclosure: Investing involves risk including the potential loss of principal. No investment strategy can guarantee a profit or protect against loss in periods of declining values. Past performance does not guarantee future results.
This material is for information purposes only and is not intended as an offer or solicitation with respect to the purchase or sale of any security. The content is developed from sources believed to be providing accurate information; no warranty, expressed or implied, is made regarding accuracy, adequacy, completeness, legality, reliability or usefulness of any information. Consult your financial professional before making any investment decision. For illustrative use only.
The following posts and commentary are to be used solely as educational tools and do not contain investment advice. Investment advice must be tailored to a particular investor’s specific needs. None of the information contained should be construed to be investment advice. Individuals wishing to tailor a plan to their own needs should seek the help of a Registered Investment Advisor.
There is a high degree of risk in investing and trading. Independent Investment Advisors assumes no responsibility. Principles of Independent Investment Advisors may, at times, maintain directly or indirectly, positions in securities or derivatives mentioned in these comments.

Financial Planner
[See Full Bio](https://independentadvisorsnw.com/author/financial-planner/) [ ](https://independentadvisorsnw.com/author/financial-planner/)
**Categories:** All Posts, Financial Planning
---
### [HOW TO SPRING CLEAN FOR A BETTER FINANCIAL LIFE](https://independentadvisorsnw.com/how-to-spring-clean-for-a-better-financial-life/)
**Published:** March 12, 2021
**Author:** Financial Planner
**Content:**
Simple Powerful Ways to De clutter Your Financial LifeClutter is a common annoyance, especially in a busy household. But did you know it sneaks up in your financial life as well? And that it can also cost you money?
“Financial clutter” is distracting, and it makes it hard to see the progress you’re making toward your financial goals. It can even hide problems until they become big and urgent. Clutter doesn’t appear out of nowhere. It grows over time, adding another layer of stress to our already busy lives. The solution is simple: Get rid of the clutter. While it may not sound glamorous, it doesn’t have to be tedious or painstaking.
But it does need to be done from time to time because clutter won’t go away by itself. And the results are well worth the effort. Getting started is easier than you might think. If you focus on a few key financial areas as part of your spring cleaning, a little bit of tidying up can go a long way toward eliminating clutter. It can also help you refocus and put you in a better frame of mind when it’s time to make important financial choices. Here’s where to begin…
## [7 Simple & Powerful Ways to De-clutter Your Financial Life](https://independentadvisorsnw.com/)
### 1.) Organize Your Documents & Accounts
Have piles of statements or documents piling up? Go through them and decide: Can I set up paperless statements or billing to reduce the clutter? Do I actually need to keep this? If so, back it up digitally and file it away. Shred everything else.
Next, review your accounts. Do you have bank, credit, or other accounts you haven’t used in months? If you’re paying fees for those, consider closing them (if doing so wouldn’t ding your credit score).
### 2.) Review Your Beneficiaries
We recommend reviewing your beneficiaries and estate documents regularly so that you can make sure the people, trusts, and institutions you have listed still represent your wishes. If you don’t already, we strongly recommend naming a second or contingent beneficiary or representative in case the primary is unable to step in or inherit assets.
### 3.) Update Your Subscriptions
Digital clutter can be just as stressful as physical clutter. And our inboxes are usually ground zero for the digital clutter we have to face daily. If your inbox is overflowing, identify any listserv, subscription, or promotional messages you haven’t opened in a couple of months and unsubscribe from them. (Tip: search for “unsubscribe” to identify promotional messages.) As you do this, organize and/or archive any emails you need to save. Also, take a look at your other subscriptions. Review the ones you have for software, magazines, memberships, or other items. Cancel the ones you don’t need or use.
### 4.) Go Over Your Insurance Policies
When’s the last time you reviewed your policies? Life, health, and disability policies often get regular attention, but your auto, homeowner’s, and other policies need review as well. For example, are you driving as much this year? If not, you might qualify for a better rate on your auto policy. Make some big purchases or upgrades? You’ll want to update your personal property inventory and maybe review your homeowner’s coverage.
### 5.) Reconsider Your Tax Withholding’s
Don’t let the wrong withholding give Uncle Sam a free loan or set you up for a surprise tax bill! Take a fresh look at your withholdings, and think about changes in your family, income, and/or assets over the past year. Also, consider any changes you may be planning in these areas this year. All of these can be good reasons to update your tax withholdings.
### 6.) Automate Your Savings
Haven’t reviewed your savings in a while? Now’s the time. When you have subscriptions that are auto-drafted, it’s easy to forget about them and spend more than you intended. On the flip side, automatic deposits into your savings make it easy to save more with less effort. Explore the options available from your financial institution. Transfers can be set aside from direct deposits or as recurring events at any frequency. You can even set up round-up deposits, so you are contributing to your savings with every purchase you make. As you consider the options, think about what you need to put away for future plans, upcoming tax bills, and the unexpected rainy days.
### 7.) Check in on Your Financial Goals
Financial spring cleaning isn’t just about removing clutter and setting up systems. It’s also about restoring clarity and reconnecting with the purpose of your financial life. Take some time to revisit and reflect on your financial goals and how they connect to your values. Are you still working toward the same dreams? Do you need to update them or add new ones? Be sure to celebrate your progress!
### 7.) Check in on Your Financial Goals
Financial spring cleaning isn’t just about removing clutter and setting up systems. It’s also about restoring clarity and reconnecting with the purpose of your financial life. Take some time to revisit and reflect on your financial goals and how they connect to your values. Are you still working toward the same dreams? Do you need to update them or add new ones? Be sure to celebrate your progress!
### Financial Lesson:
When You Get Rid of the Clutter, You Make Space to Enrich Your Financial Life Few of us have our financial lives in perfect order. Even if we get close or we do achieve it, perfect order is never a finish line. It’s a moving target — because life isn’t static. That’s why we have to maintain our financial lives to sustain and enrich them. If we don’t, financial clutter can build up as quickly as the papers on our desks. It can cost us money, expose us to risk, and stall the progress we want to make toward our financial goals. Some simple spring cleaning can put an end to that. It provides an opportunity to examine key parts of our financial lives so we can tidy them up before they get messy. It also helps us avoid overwhelm by giving us a framework to check-in, reorganize, and make important adjustments to support our evolving needs and long-term objectives. This sets us up to be proactive and establish good financial habits. It also gives us new clarity and real control over the trajectory of our financial futures. And the power of financial spring cleaning isn’t limited to your personal finances. It can extend to businesses, philanthropy, relationships, and beyond.

Financial Planner
[See Full Bio](https://independentadvisorsnw.com/author/financial-planner/) [ ](https://independentadvisorsnw.com/author/financial-planner/)
**Categories:** All Posts, Financial Planning
---
### [5 Powerful Ways to Set Authentic Financial Goals In Uncertain Times](https://independentadvisorsnw.com/5-powerful-ways-to-set-authentic-financial-goals-in-uncertain-times/)
**Published:** January 26, 2021
**Author:** Financial Planner
**Content:**
**What is your biggest obstacle to achieving your goals in 2021?**
It’s not a lack of time or bad timing. It’s not age, ability, or finances. And it’s not even the coronavirus.
Believe it or not, research says it’s you.1
In fact, most of us trip ourselves up when it comes to achieving our goals. That includes New Year’s resolutions.2
Even when we have the best intentions, we can get in the way of our own progress.
And that’s far more likely to happen during times of uncertainty.3
That’s when we tend to stagnate. We avoid long-term plans and push pause on our big goals. And we become paralyzed by uncertainty. Sometimes, that means we simply give up on setting goals entirely.4
And, yet, New Year’s goals help us.
They give us a sense of control and keep us grounded in unpredictable times. And they can help us cope with uncertainty and motivate us to keep trying to improve parts of our lives.5
So, how do you overcome uncertainty paralysis? How do you set goals when everything feels so up in the air?
**With a handful of simple, powerful principles that can help you set the right goals and expectations.**
If you can use these principles as you set and pursue your goals, you’ll be able to choose better goals that are within your power to achieve. You can also discover new paths to progress — even during the most chaotic times.
[Click here to read more >](https://independentadvisorsnw.com/)

Financial Planner
[See Full Bio](https://independentadvisorsnw.com/author/financial-planner/) [ ](https://independentadvisorsnw.com/author/financial-planner/)
**Categories:** All Posts, Financial Planning
---
### [What Should You Do With Your Old 401(k) or Employer Plan?](https://independentadvisorsnw.com/what-should-you-do-with-your-old-401k-or-employer-plan/)
**Published:** January 28, 2021
**Author:** Financial Planner
**Content:**
*FREE Guide Reveals 5 Options for Old 401(k), 403(b), and some 457 Plans*
**What Should You Do With Your Old 401(k) or Employer Plan?**
**This FREE Guide will help you get crystal clear on which of these 5 options is right for you and the steps you should take next. Inside, you’ll discover:**
- The **5 options** for handling your old employer plan (and what to do next)
- The critical steps to **avoid a surprise tax bill** or accidentally making your account **permanently taxable**
- The **pros and cons** of each strategy to help you **make the right choice for you**
“You have to make a **critical decision**… because if you make a mistake… you could inadvertently end up with a **surprise tax bill** and **lose the power of tax-deferred growth**… After you’re done reading this guide, you’ll decide which of these 5 strategies makes the most sense for your old retirement plan and how you can take the first steps that are **right for you**.”
You have to make a critical decision because if you make a mistake you could inadvertently end up with a surprise tax bill and lose the power of tax deferred growth After youre done reading this guide youll decide which of these 5 strategies makes the most sense for your old retirement plan and how you can take the first steps that are right for you
[](https://independentadvisorsnw.com/) 
Financial Planner
[See Full Bio](https://independentadvisorsnw.com/author/financial-planner/) [ ](https://independentadvisorsnw.com/author/financial-planner/)
**Categories:** All Posts, Financial Planning
---
### [How to Be a Smarter Investor in Uncertain Times](https://independentadvisorsnw.com/how-to-be-a-smarter-investor-in-uncertain-times/)
**Published:** January 4, 2021
**Author:** Investment Advisor
**Content:**
In a perfect world, logic would always guide our financial decisions. Emotions wouldn’t come into play. But we don’t live in a perfect world, far from it. That means our emotions impact our financial choices more than we realize.1
**Shockingly as much as 95% of our purchase choices are made subconsciously, driven by our emotions—as little as 5% are based on logic** (and that’s when we’re in the right headspace and feeling comfortable and secure).2
When we’re faced with uncertainty, fear and instinct can take over and push logic right out of the window.3 Your brain will make you want to react quickly to protect yourself and avoid the pain you anticipate from potential losses.4 Ironically, these instincts often make things worse. Emotional reactions can lead to poor choices and the losses you were trying to avoid in the first place.5
In a perfect world, logic would always guide our financial decisions. Emotions wouldn’t come into play. But we don’t live in a perfect world, far from it.
The best way to avoid letting your hardwired biases take over? Use these strategies. They can help you fare better in any crisis. They may even make you a savvier investor.
## 6 Secrets to Make You a Smarter Investor
### 1. Avoid the Overconfidence Trap
Overconfidence is a killer. In fact, research shows that the more experience you have as an investor, the more overconfident you tend to be.6
**Stay realistic and grounded by a strategy. Get advice before making big decisions.**
### 2. Force Emotions Into the Backseat
Losing money hurts. The truth is that the pain of losses can actually be more intense than any satisfaction from gains. Economists call that “loss aversion.” 7 The pressure of anxiety or uncertainty can lead to irrational choices that actually work against our big-picture financial goals.
**Don’t give into fear or panic** when they show up. Focus on logic and rely on your professional for guidance.
### 3. Frame Performance in a More Meaningful Way
Framing is everything when it comes to evaluating performance. That’s because the way information and events are presented to us can sway our perception and influence our decisions.8
**Look beyond short-term outcomes** when framing performance. Think about your longer-term goals and the progress you are making towards them, even when short-term corrections slow your progress.
### 4. Neutralize Your Recency Bias
Recent events usually influence you more than those in the distant past. Why? The human brain remembers recent events more clearly and gives them outsized weight when making decisions. Your brain can mislead you by expecting more of what you’ve seen already. And that can lead to overconfidence and emotional decisions.9
**Resist this tendency** by remembering the market is constantly changing. Over the long term, bear markets recover. And no bull market lasts forever.
### 5. Consider Multiple Perspectives
With decision making, it’s natural to focus on one aspect or one piece of information as a starting point. Often, that can greatly influence your final choice. This is known as “anchoring bias,” which can give you tunnel vision. It can lead you to fixate on a single data point, like an investment’s price, while ignoring other key information.
**To fight it, seek out more information.** Think critically about multiple perspectives, and don’t forget to consider future potential.
### 6. Slow Down & Take Time To Think More Deeply
Humans like to make snap decisions. And, when you’re stressed out, you’re far more likely to make impulsive decisions. The problem is that “gut” decisions are made based on instinct, habit, and emotions, instead of logic and facts. When you’re in gut-decision mode, it can be much harder to make goal-oriented choices.10
**Take your time when making financial decisions and let your brain shift into analytical mode.** With a little time, emotions cool down, and you’ll typically consider more alternatives.11
**Take your time when making financial decisions and let your brain shift into analytical mode.** With a little time, emotions cool down, and you’ll typically consider more alternatives.11
## Financial Lesson: *Keep Your Cool & Focus on the Long Game When Crisis Strikes*
Markets and economies are never predictable or under our control. We can’t foresee or control downturns or upswings. We can only control our mindset, our emotions, and our financial choices.
That’s easy to lose sight of during periods of economic uncertainty and financial stress.
But, if you can focus on the long game and improve your mental game, you’ll come out stronger and more prepared.
That can make you less vulnerable to hardwired human biases and help you make better financial decisions, no matter what the markets are doing.
As a financial adviser, one of my most important jobs is to help you become a smarter, more capable investor. That involves using psychology and behavioral finance to help you learn more about how your brain works and improve your financial behaviors.
I’m also here to be an objective accountability partner. I talk my clients through emotional decisions, and I can be an important voice of reason and calm when markets are turbulent and it feels like the sky is falling.
If you’re curious about behavioral finance—or if you need a sounding board for a financial decision—I’m here for you. Don’t hesitate to call me at (971) 350-8068.
I’d be happy to answer your questions and share some more advice.
### Sources & Disclosures
1 [https://scholar.harvard.edu/files/jenniferlerner/files/annual\_review\_manuscript\_june\_16\_final.final\_.pdf](https://scholar.harvard.edu/files/jenniferlerner/files/annual_review_manuscript_june_16_final.final_.pdf)
2
3
4
5
6
7
8 [https://corporatefinanceinstitute.com/resources/knowledge/trading-investing/framing-bias/](https://corporatefinanceinstitute.com/resources/career-map/sell-side/capital-markets/framing-bias/)
9
10
11
The following posts and commentary are to be used solely as educational tools and do not contain investment advice. Investment advice must be tailored to a particular investor’s specific needs. None of the information contained should be construed to be investment advice. Individuals wishing to tailor a plan to their own needs should seek the help of a Registered Investment Advisor.
There is a high degree of risk in investing and trading. Independent Investment Advisors assumes no responsibility. Principles of Independent Investment Advisors may, at times, maintain directly or indirectly, positions in securities or derivatives mentioned in these comments.
Risk Disclosure: Investing involves risk including the potential loss of principal. No investment strategy can guarantee a profit or protect against loss in periods of declining values. Past performance does not guarantee future results.
This material is for information purposes only and is not intended as an offer or solicitation with respect to the purchase or sale of any security. The content is developed from sources believed to be providing accurate information; no warranty, expressed or implied, is made regarding accuracy, adequacy, completeness, legality, reliability, or usefulness of any information. Consult your financial professional before making any investment decision. For illustrative use only.
Opinions expressed are subject to change without notice and are not intended as investment advice or to predict future performance. These are the views of Finance Insights and not necessarily those of the named representative or firm, and should not be construed as investment advice.

Investment Advisor
[See Full Bio](https://independentadvisorsnw.com/author/investment-advisor/) [ ](https://independentadvisorsnw.com/author/investment-advisor/)
**Categories:** All Posts, Investment Advisor
---
### [Q3 2020 – Quarterly Portfolio Review](https://independentadvisorsnw.com/q3-2020-quarterly-portfolio-review/)
**Published:** October 7, 2020
**Author:** Portfolio Manager
**Content:**
In this quarterly post, we review the composition and the performance of several investment portfolios managed by our Investment Advisor. Portfolios we review are actual live portfolios for several different clients and range from a conservative client who is already in retirement and looking for income to a very aggressive portfolio set up for young children with a 30-year investment horizon. The purpose of this post is to educate our investors and clients and help set expectations on how different portfolios perform over time. It also showcases how we think about and manage capital assets. We also show “Advisor View” which is an overview of the composition and performance of all portfolios under our management.
In this quarterly post we review the composition and the performance of several actual live investment portfolios managed by our Investment Advisor
## Advisors View
Advisors view includes all client accounts and all client allocated portfolios under our management. It’s a snapshot of the advisor dashboard we look at every day.
**Investment Performance**
Q1 2020Q2 2020Q3 2020Q4 2020YTD 2020-12.42%10.51%1.91%0.42%
**Asset Class Allocation**
*Long**Short*Equities49.32%4.22%Fixed Income26.17%0.00%Real Estate7.97%0.17%Other Assets0.12%5.78%Fund Cash16.21%85.76%
**Geographic Allocation**
*Long**Short*North America88.28%94.17%Asia5.38%0.00%Europe4.25%0.02%South America0.82%0.00%Africa0.51%0.00%Oceania0.39%0.00%Other0.37%5.81%
**Sector Allocation**
*Long**Short*Basic Materials1.20%0.00%Cons Cyclical4.91%0.00%Cons Non-Cyclical2.37%0.00%Energy3.68%0.00%Financials8.52%3.70%Healthcare6.71%0.24%Industrial6.33%0.23%Real Estate7.98%0.17%Technology11.81%0.01%Telecom Services2.70%0.00%Utilities1.44%0.00%Cash16.21%85.76%Fund Cash0.21%4.08%Unclassified25.92%5.81%
## Retiree Portfolio
Portfolio and client situation summary:
- The client is already in retirement (as of 1/1/2020)
- The client needs 20 years (estimated) of income and capital preservation
- The client will not contribute to the portfolio
- Investment portfolio is in conservative allocation
**Investment Performance**
Q1 2020Q2 2020Q3 2020Q4 2020YTD 2020-4.29%3.63%1.51%1.41%
**Asset Class Allocation**
*Long**Short*Equities19.91%50.49%Fixed Income79.48%0.00%Real Estate0.41%0.00%Other Assets0.08%1.71%Fund Cash0.06%2.70%
**Geographic Allocation**
*Long**Short*North America94.75%98.24%Asia2.24%0.04%Europe2.24%0.02%South America0.60%0.00%Africa0.39%0.00%Oceania0.13%0.00%Other0.09%1.71%
**Sector Allocation**
*Long**Short*Basic Materials0.56%0.00%Cons Cyclical2.04%0.00%Cons Non-Cyclical3.82%0.00%Energy1.45%0.00%Financials2.67%0.00%Healthcare2.72%0.00%Industrial1.26%0.00%Real Estate0.42%0.00%Technology2.88%0.00%Telecom Services1.21%0.00%Utilities2.98%0.00%Cash0.06%45.09%Fund Cash0.06%2.70%Unclassified77.87%1.71%
## Retirement IRA Portfolio
Portfolio and client situation summary:
- The client is currently working and is looking toward a 20/25-year time horizon before retirement (as of 1/1/2019)
- The client will make an annual contribution based on annual maximums
- Investment portfolio is in mid-to-aggressive allocation
**Investment Performance**
Q1 2020Q2 2020Q3 2020Q4 2020YTD2020-22.44%17.41%5.32%-2.25%**Asset Class Allocation**
*Long**Short*Equities73.66%0.58%Fixed Income16.67%0.00%Real Estate8.34%0.00%Other Assets0.12%14.25%Fund Cash0.50%85.16%
**Geographic Allocation**
*Long**Short*North America79.26%84.98%Asia9.64%0.03%Europe7.19%0.16%South America1.39%0.00%Africa1.08%0.00%Oceania0.61%0.00%Other0.82%14.48%
**Sector Allocation**
*Long**Short*Basic Materials2.60%0.00%Cons Cyclical9.16%0.00%Cons Non-Cyclical3.64%0.00%Energy5.61%0.00%Financials14.17%0.00%Healthcare8.04%0.00%Industrial6.98%0.00%Real Estate8.44%0.00%Technology17.38%0.00%Telecom Services4.89%0.00%Utilities2.42%0.00%Cash0.63%0.00%Fund Cash0.46%85.16%Unclassified15.55%14.84%
## Trust Brokerage Account for Children
Portfolio and client situation summary:
- The revocable trust is created with a 30-year time horizon (as of 1/1/2019)
- The trustee will make modest but continuous monthly contribution
- Investment portfolios is in aggressive allocation
- Investment portfolio uses margin
- \*\* Portfolio was 50% margined in late February 2020
Q1 2020Q2 2020Q3 2020Q4 2020YTD 2020-38.30%44.55%11.76%3.52%**Asset Class Allocation**
*Long**Short*Equities94.02%0.01%Fixed Income0.05%0.00%Real Estate5.26%0.00%Other Assets0.14%0.28%Fund Cash0.13%99.65%
**Geographic Allocation**
*Long**Short*North America84.52%99.70%Asia9.77%0.00%Europe3.99%0.00%South America0.89%0.00%Africa0.42%0.00%Oceania0.22%0.00%Other0.18%0.29%
**Sector Allocation**
*Long**Short*Basic Materials2.64%0.00%Cons Cyclical12.25%0.00%Cons Non-Cyclical4.37%0.00%Energy4.75%0.00%Financials10.24%0.00%Healthcare10.44%0.00%Industrial7.75%0.00%Real Estate5.25%0.00%Technology26.99%0.00%Telecom Services7.20%0.00%Utilities2.10%0.00%Cash0.13%99.65%Fund Cash0.39%0.06%Unclassified5.49%0.29%

Portfolio Manager
[See Full Bio](https://independentadvisorsnw.com/author/portfolio-manager/) [ ](https://independentadvisorsnw.com/author/portfolio-manager/)
**Categories:** Portfolio & Market Reviews
---
### [Borrowing From Your Retirement Plan: New CARES Act Rules](https://independentadvisorsnw.com/borrowing-from-your-retirement-plan-new-cares-act-rules/)
**Published:** September 28, 2020
**Author:** Financial Planner
**Excerpt:** In late March, Congress passed the Coronavirus Aid, Relief and Economic Security Act (CARES Act). This bill offered provisions related to distributions from retirement accounts such as an IRA or 401(k).
**Content:**
It’s been nearly half a year since Americans first became widely aware of the Coronavirus contagion within the United States. For a short month, it looked as if we had the virus in hand; since then, it has spread wildly out of control in many areas.
In late March, Congress passed the Coronavirus Aid, Relief and Economic Security Act (CARES Act). This bill offered provisions related to distributions from retirement accounts such as an IRA or 401(k). One of the key goals was to enable workers to make penalty-free withdrawals from a retirement plan to sustain them while out of work due to the Coronavirus.
Borrowing From Your Retirement Plan New CARES Act Rules
To be eligible to make penalty-free withdrawals, plan participants must meet one of the following criteria:
- The account owner, spouse, or a dependent is diagnosed with COVID-19
- The account owner experiences one of the following financial consequences due to the virus:
- Furloughed
- Laid-off
- Work hours reduced or place of business closed (including for self-employed)
- No access to childcare
- Quarantined
The Act stipulates that workers can self-certify that they meet at least one of the criteria. Be aware, however, that if it is later discovered that the account owner did not meet the criteria for a coronavirus-related distribution, he might be required to pay the early withdrawal penalty.
Also, while this penalty is waived for qualified workers, they must still pay income taxes on the amount withdrawn. However, there are a few ways to mitigate the income tax burden on those withdrawals. The first is to through regular distribution. These are the parameters:
- You have up until December 30, 2020, to make a distribution
- The total aggregate limit is $100,000 from all plans and IRAs
- The distribution waives the 20 percent income tax withholding requirement
- Income taxes will be due when filing a 2020 tax return
- Retirement account owners who no longer work for an employer are free to take a distribution
- Current employees may take a distribution only if the employer plan allows for a hardship or in-service distribution (note that the CARES Act permits employers to amend plan documents to allow coronavirus-related distributions)
While a retirement plan distribution does trigger income taxes for the tax year withdrawn, you can spread the tax burden out over three years. For example, let’s say you withdraw $18,000 this year. You may report the full amount as income on your 2020 tax return; or you can claim $6,000 a year on your 2020, 2021 and 2022 returns. This strategy reduces the chances of bumping your income into a higher tax bracket.
The second way to is to pay the distributed amount back into your retirement plan. Initially, you will have to pay income taxes on the amount withdrawn. However, if you pay it back within three years, you can file to get the taxes you paid refunded. One caveat with this plan is that eligible retirement plans will treat repayment of this type of distribution as a rollover event for tax purposes. Be aware that if the retirement plan does not accept rollover contributions, it is not required to change its terms for this purpose.
Your third option is to withdraw money as a loan if your employer permits loans from the retirement plan. This is another scenario in which you must repay that money within a specified time period. You do not have to pay income taxes on loan, but you do have to pay interest on the amount borrowed. The good news is that the interest you pay also goes into your account.
Under normal circumstances, retirement account loans are limited to $50,000 or 50 percent of the account balance, whichever is less. But for a coronavirus loan, you may borrow up to 100 percent of your vested balance or $100,000, whichever is less. You will need to repay that loan within the plan’s stated repayment period, although the CARES Act gives 2020 borrowers an additional year to repay this type of loan from an eligible retirement plan. Be aware, though, that you’ll owe both income taxes on the outstanding balance and the penalty for withdrawals made before age 59½ if you do not repay that loan in time.
Note that these CARES Act provisions are available only for the first 180 days after the Act was passed, which was on March 27, 2020. As Congress debates new legislation to aid struggling Americans suffering from the pandemic, this provision could be extended.

Financial Planner
[See Full Bio](https://independentadvisorsnw.com/author/financial-planner/) [ ](https://independentadvisorsnw.com/author/financial-planner/)
**Categories:** All Posts, Financial Planning
---
### [Q4 2020 – Quarterly Portfolio Review](https://independentadvisorsnw.com/q4-2020-quarterly-portfolio-review/)
**Published:** January 21, 2021
**Author:** Portfolio Manager
**Content:**
This quarterly post reviews the composition and performance of several investment portfolios managed by our Investment Advisor. Portfolios we review are actual live portfolios for several clients and range from a conservative client who is already in retirement and looking for income to a very aggressive portfolio set up for young children with a 30-year investment horizon. The purpose of this post is to educate our investors and clients and help set expectations on how different portfolios perform over time. It also showcases how we think about and manage capital assets. We also show “Advisor View,” which is an overview of all portfolios’ composition and performance under our management.
In this quarterly post we review the composition and the performance of several actual live investment portfolios managed by our Investment Advisor
## Advisors View
Advisors view includes all client accounts, and all client allocated portfolios under our management. It’s a snapshot of the advisor dashboard we look at every day.
**Investment Performance**
Q1 2020Q2 2020Q3 2020Q4 2020FY 2020-12.42%10.51%1.91%11.92%10.42%
**Asset Class Allocation**
*Long**Short*Equities54.21%0.74%Fixed Income8.39%0.00%Real Estate8.61%0.00%Other Assets0.07%9.29%Fund Cash28.59%5.66%Portfolio asset allocation is a snapshot in time taken at the posting date of this update.
**Geographic Allocation**
*Long**Short*North America88.01%90.68%Asia5.57%0.00%Europe4.39%0.02%South America0.79%0.00%Africa0.49%0.00%Oceania0.41%0.00%Other0.34%9.32%Portfolio asset allocation is a snapshot in time taken at the posting date of this update.
**Sector Allocation**
*Long**Short*Basic Materials1.46%0.00%Cons Cyclical6.22%0.00%Cons Non-Cyclical2.74%0.00%Energy4.25%0.00%Financials17.33%3.70%Healthcare7.62%0.24%Industrial5.02%0.23%Real Estate7.98%0.17%Technology13.58%0.01%Telecom Services3.12%0.00%Utilities1.50%0.00%Cash28.59%84.31%Fund Cash0.10%5.66%Unclassified8.47%9.32%Portfolio asset allocation is a snapshot in time taken at the posting date of this update.
## Retiree Portfolio
Portfolio and client situation summary:
- The client is already in retirement (as of 1/1/2020)
- The client needs 20 years (estimated) of income and capital preservation
- The client will not contribute to the portfolio
- The investment portfolio is in conservative allocation
**Investment Performance**
Q1 2020Q2 2020Q3 2020Q4 2020FY 2020-4.29%3.63%1.51%4.02%4.72%
**Asset Class Allocation**
*Long**Short*Equities23.33%0.00%Fixed Income11.46%0.00%Real Estate0.43%0.00%Other Assets0.09%47.22%Fund Cash0.06%52.78%Portfolio asset allocation is a snapshot in time taken at the posting date of this update.
**Geographic Allocation**
*Long**Short*North America94.22%52.78%Asia1.83%0.00%Europe2.61%0.00%South America0.60%0.00%Africa0.39%0.00%Oceania0.16%0.00%Other0.20%47.22%Portfolio asset allocation is a snapshot in time taken at the posting date of this update.
**Sector Allocation**
*Long**Short*Basic Materials0.89%0.00%Cons Cyclical2.34%0.00%Cons Non-Cyclical4.20%0.00%Energy1.78%0.00%Financials3.52%0.00%Healthcare3.73%0.00%Industrial1.61%0.00%Real Estate0.42%0.00%Technology3.19%0.00%Telecom Services1.30%0.00%Utilities3.16%0.00%Cash64.46%0.00%Fund Cash0.06%52.78%Unclassified9.76%47.22%Portfolio asset allocation is a snapshot in time taken at the posting date of this update.
## Retirement IRA Portfolio
Portfolio and client situation summary:
- The client is currently working and is looking toward a 20/25-year time horizon before retirement (as of 1/1/2019)
- The client will make an annual contribution based on annual maximums
- The investment portfolio is in mid-to-aggressive allocation
**Investment Performance**
Q1 2020Q2 2020Q3 2020Q4 2020FY 2020-22.44%17.41%5.32%14.39%9.71%**Asset Class Allocation**
*Long**Short*Equities75.04%0.37%Fixed Income14.05%0.00%Real Estate7.90%0.00%Other Assets0.06%22.50%Fund Cash2.68%77.13%Portfolio asset allocation is a snapshot in time taken at the posting date of this update.
**Geographic Allocation**
*Long**Short*North America79.89%77.12%Asia9.65%0.00%Europe6.85%0.01%South America1.31%0.00%Africa0.97%0.00%Oceania0.57%0.00%Other0.82%22.87%Portfolio asset allocation is a snapshot in time taken at the posting date of this update.
**Sector Allocation**
*Long**Short*Basic Materials2.60%0.00%Cons Cyclical9.16%0.00%Cons Non-Cyclical3.64%0.00%Energy5.61%0.00%Financials14.17%0.00%Healthcare8.04%0.00%Industrial6.98%0.00%Real Estate8.44%0.00%Technology17.38%0.00%Telecom Services4.89%0.00%Utilities2.42%0.00%Cash0.63%0.00%Fund Cash0.46%85.16%Unclassified15.55%14.84%Portfolio asset allocation is a snapshot in time taken at the posting date of this update.
## Trust Brokerage Account for Children
Portfolio and client situation summary:
- The revocable trust is created with a 30-year time horizon (as of 1/1/2019)
- The trustee will make a modest but continuous monthly contribution
- Investment portfolios is in aggressive allocation
- Investment portfolio uses margin
- \*\* Portfolio was 50% margined in late February 2020
Q1 2020Q2 2020Q3 2020Q4 2020FY 2020-38.30%44.55%11.76%28.78%28.35%**Asset Class Allocation**
*Long**Short*Equities94.02%0.01%Fixed Income0.05%0.00%Real Estate5.26%0.00%Other Assets0.14%0.28%Fund Cash0.13%99.65%Portfolio asset allocation is a snapshot in time taken at the posting date of this update.
**Geographic Allocation**
*Long**Short*North America84.52%99.70%Asia9.77%0.00%Europe3.99%0.00%South America0.89%0.00%Africa0.42%0.00%Oceania0.22%0.00%Other0.18%0.29%Portfolio asset allocation is a snapshot in time taken at the posting date of this update.
**Sector Allocation**
*Long**Short*Basic Materials2.64%0.00%Cons Cyclical12.25%0.00%Cons Non-Cyclical4.37%0.00%Energy4.75%0.00%Financials10.24%0.00%Healthcare10.44%0.00%Industrial7.75%0.00%Real Estate5.25%0.00%Technology26.99%0.00%Telecom Services7.20%0.00%Utilities2.10%0.00%Cash0.13%99.65%Fund Cash0.39%0.06%Unclassified5.49%0.29%Portfolio asset allocation is a snapshot in time taken at the posting date of this update.

Portfolio Manager
[See Full Bio](https://independentadvisorsnw.com/author/portfolio-manager/) [ ](https://independentadvisorsnw.com/author/portfolio-manager/)
**Categories:** Portfolio & Market Reviews
---
### [Independent Investment Advisors featured by Bethany & Cedar Mill Living Magazine](https://independentadvisorsnw.com/independent-investment-advisors-bethany-cedar-mill-living-feature/)
**Published:** May 26, 2020
**Author:** Investment Advisor
**Content:**
We are thrilled to announce the Bethany & Cedar Mill Living magazine feature. Our founder and principal investment advisor is getting featured as the local financial expert in the Bethany & Cedar Mill Living magazine. A social magazine for residents of Bethany & Cedar Mill neighborhoods located in Portland, OR. We have been Cedar Mill residents for thirteen years, so we are truly inspired to be further engaged in our local community. We will also be sponsoring a monthly Financial Fitness article and ask the expert Q&A.
[Bethany & Cedar Mill Living magazine](https://www.facebook.com/BethanyandCedarMillLiving/)
Independent Investment Advisors Bethany Cedar Mill Living Feature Ad 
Investment Advisor
[See Full Bio](https://independentadvisorsnw.com/author/investment-advisor/) [ ](https://independentadvisorsnw.com/author/investment-advisor/)
**Categories:** News and Announcements
---
### [The Financial Quarterly Q1 2021](https://independentadvisorsnw.com/the-financial-quarterly/)
**Published:** April 26, 2021
**Author:** Investment Advisor
**Excerpt:** The first quarter of 2021 had a little bit of everything: politics, bubbles, meme stocks, rallies, and sudden drops. Let's take a look at how markets performed and what we might look forward to in the months to come.
**Content:**
[< back to Market Insights Blog](https://independentadvisorsnw.com/homepage/markets-insights/)
The Financial Quarterly
# The Financial Quarterly
1st Quarter 2021

Goran Ognjenovic
https://independentadvisorsnw.com
**Independent Investment Advisors**
(971) 350-8068
The first quarter of 2021 had a little bit of everything: politics, bubbles, meme stocks, rallies, and sudden drops. Let's take a look at how markets performed and what we might look forward to in the months to come.
Looking Back
### How Did Markets Perform Last Quarter?
### S&P 500
The broader U.S. market grew in Q1 on stimulus, optimism, and the economic recovery.1
### NASDAQ
The tech-focused NASDAQ rallied on a new technology boom, but pulled back at quarter's end on interest rate fears.2
### DOW 30
Blue chip stocks soared in Q1 on expectations of economic growth and stimulus.3
Looking Ahead
### What Can We Expect in the Months Ahead?
### U.S. Economic Outlook
 Negative Positive
### Equity Outlook
 Negative Positive
### Consumer Sentiment
 Negative Positive
### Labor Market
 Negative Positive
### Business Outlook
 Negative Positive
### Fiscal Policy
 Negative Positive

> "Despite continued challenges, markets had a strong performance in Q1. While uncertainty remains, we expect continued economic growth this quarter."

## Not receiving our newsletter? Get insightful info on finances and more in your inbox every month with the Insider's List
Contact me by FAX only?
Bottom Line
## Key Takeaways for Savvy Investors
Despite a lot of uncertainty around business reopenings, vaccination rates, and economic growth, equities delivered a solid performance last quarter. Looking back, while it's easy to focus on the quarter's overall performance, let's not forget that there were many dips and rallies along the way.
Bottom line, we can expect more volatility and uncertainty this year. After nearing record highs, it would not be surprising to see a market drop in the second quarter.
What lies ahead? A popular survey of economists suggests that the economy could grow ~7% this quarter as the economy continues to pick up steam.4 However, there are many variables and uncertainties baked into those projections: vaccination timelines, consumer spending, new government regulations, and business expectations.
Overall, I'm cautiously optimistic about where the economy and markets will go this quarter. However, I'm also keeping a close eye on market conditions, as continued uncertainty could drive sudden changes.
Questions? Please reach out. I'd be happy to chat.
Goran Ognjenovic
Independent Investment Advisors
(971) 350-8068
info@independentadvisorsnw.com

**Sources:**
1
2 [https://www.reuters.com/article/us-usa-stocks/tech-lifts-sp-500-nasdaq-indexes-post-gains-for-quarter-idINKBN2BN1MD](https://www.reuters.com/article/us-usa-stocks/tech-lifts-sp-500-nasdaq-indexes-post-gains-for-quarter-idINKBN2BN1MD/)
3
4 [https://www.wsj.com/graphics/econsurvey](https://www.wsj.com/graphics/econsurvey/) (March 2021) [Archive link](https://snappykraken-assets.s3.amazonaws.com/campaigns/_SK14_Financial_Dashboard/14.1_Q1_2021/sources/Q1+2021+WSJ+Econ+Survey.pdf)
S&P 500: (Closing price performance between December 31, 2020 and March 31, 2021)
NASDAQ: (Closing price performance between December 31, 2020 and March 31, 2021)
Dow Jones Industrial Average: (Closing price performance between December 31, 2020 and March 31, 2021)
U.S. Economic Outlook, Equity Outlook, Consumer Sentiment, Labor Market, Business Outlook, and Fiscal Policy gauges: (April 2021)
The following posts and commentary are to be used solely as educational tools and do not contain investment advice. Investment advice must be tailored to a particular investor’s specific needs. None of the information contained should be construed to be investment advice. Individuals wishing to tailor a plan to their own needs should seek the help of a Registered Investment Advisor.
There is a high degree of risk in investing and trading. Independent Investment Advisors assumes no responsibility. Principles of Independent Investment Advisors may, at times, maintain directly or indirectly, positions in securities or derivatives mentioned in these comments.
The S&P 500 is a stock index considered to be representative of the U.S. stock market in general. The NASDAQ Composite Index is an unmanaged composite index of over 2,500 common equities listed on the NASDAQ stock exchange. The Dow Jones Industrial Average is a price-weighted index that tracks 30 large, publicly traded American companies.
All index returns exclude reinvested dividends and interest. Indices are unmanaged and cannot be invested into directly.
Risk Disclosure: Investing involves risk including the potential loss of principal. No investment strategy can guarantee a profit or protect against loss in periods of declining values. Past performance does not guarantee future results.
This material is for information purposes only and is not intended as an offer or solicitation with respect to the purchase or sale of any security. The content is developed from sources believed to be providing accurate information; no warranty, expressed or implied, is made regarding accuracy, adequacy, completeness, legality, reliability or usefulness of any information. Consult your financial professional before making any investment decision. For illustrative use only.
##### You're Signed Up!
 **Goran Ognjenovic
Independent Investment Advisors** Stay tuned — an email from me is on its way to your inbox right now.
Close
[ **(971) 350-8068** ]()
[ **Email Me** ](mailto:info@independentadvisorsnw.com)
[ **Visit Website** ](https://independentadvisorsnw.com "https://iiaproduction.wpengine.com")

Investment Advisor
[See Full Bio](https://independentadvisorsnw.com/author/investment-advisor/) [ ](https://independentadvisorsnw.com/author/investment-advisor/)
**Categories:** All Posts, Portfolio & Market Reviews
---
### [7 Little Upgrades that Can Make Life Better in Big Ways](https://independentadvisorsnw.com/7-little-upgrades-that-can-make-life-better-in-big-ways/)
**Published:** August 19, 2021
**Author:** Financial Planner
**Excerpt:** What would make your life better?
A new house or car? A bigger paycheck or bank account?
It’s easy to want more when you think of being happier and living better. And there’s little doubt that money can buy some (more) happiness.
**Content:**
[< back to Market Insights Blog](https://independentadvisorsnw.com/homepage/markets-insights/)
What would make your life better?
A new house or car? A bigger paycheck or bank account?
It’s easy to want more when you think of being happier and living better.1
And there’s little doubt that money can buy some (more) happiness.2
But the happiness we get from money is fundamentally limited.3
It leaves us wanting more, and it’s not enough on its own to enjoy a truly satisfying life.
The reality is a lot of the things that can make us happy and enrich our lives have nothing to do with money.4
And some of the things that may bring us the most joy could already be within our reach.4
What are they and how can they improve our lives?
Find out the answer with these simple life upgrades. They can transform the way you experience and enjoy life.
[Read Our August Newsletter Here!](https://independentadvisorsnw.com/)

Financial Planner
[See Full Bio](https://independentadvisorsnw.com/author/financial-planner/) [ ](https://independentadvisorsnw.com/author/financial-planner/)
**Categories:** All Posts, Financial Planning
---
### [THE 6 “HIDDEN” TAX SAVING OPPORTUNITIES OPENED UP BY NEW TAX RULES](https://independentadvisorsnw.com/the-6-hidden-tax-saving-opportunities-opened-up-by-new-tax-rules/)
**Published:** November 17, 2020
**Author:** Financial Planner
**Content:**
The Tax Cut and Jobs Act (TCJA) passed at the end of 2017 and the SECURE (Setting Every Community Up for Retirement Enhancement) Act passed at the end of 2019 radically changed your tax picture.
Most Americans are going to pay less in taxes under the tax brackets, and a few are going to use this great opportunity to permanently lower the taxes they pay. The COVID-19 pandemic and relief acts also spurred new tax wrinkles you should know about.
I want to emphasize that this is a limited opportunity. The 2017 rules are scheduled to expire in 2025 (if they don’t disappear sooner under a new administration), and most taxpayers will see a tax hike.
However, this sneaky IRS move means you’ll probably pay more in taxes even before they expire. To reduce the impact of the new tax laws on government revenue, the IRS changed how it increases things like thresholds, deductions, and credits for inflation.3It sounds like a minor procedural move, but it’s actually a big deal. In plain English, this change means that many taxpayers will “creep” into higher tax brackets as their incomes grow because the tax brackets themselves won’t increase as much as they used to for inflation.
Bottom line: many taxpayers will pay more in taxes over the next few years due to this hidden tax increase. It might be only a few hundred dollars every year, but over time, even small tax increases add up! Unless you take steps now to reduce your taxable income. The current tax rates might be the lowest you’ll see for the rest of your life, and I want you to make the most of them.
All 6 opportunities in this guide are actions you can take right now to potentially lower your taxes this year and in the years to come. I strongly recommend that you take this list, along with your tax return, to your CPA and financial adviser to see which tax reduction opportunities have opened up for you.
[](https://independentadvisorsnw.com/) 
Financial Planner
[See Full Bio](https://independentadvisorsnw.com/author/financial-planner/) [ ](https://independentadvisorsnw.com/author/financial-planner/)
**Categories:** All Posts, Financial Planning
---
### [Is Your Investment Portfolio Facing Volatile Markets?](https://independentadvisorsnw.com/is-your-investment-portfolio-facing-volatile-markets/)
**Published:** November 11, 2020
**Author:** Portfolio Manager
**Content:**
## A Simple Flowchart to Determine What (if Anything) You Should Do.
After the end of the 2008 financial crisis, investors rode a wave of optimism for close to a decade, pushing markets past historical highs and giving investment portfolios a healthy boost after the losses sustained during the bear market downturn. However, there are signs that the relentless market optimism is petering out, and I want you to be prepared for volatility. Though we can’t predict the future, expecting the next few years to be volatile is a smart bet. Whether you are in retirement or close to it, or many years away, this simple flowchart will guide you through the questions you need to ask to help determine whether you’re on the right track for volatility or dangerously off course with your investments.
[](https://independentadvisorsnw.com/)

Portfolio Manager
[See Full Bio](https://independentadvisorsnw.com/author/portfolio-manager/) [ ](https://independentadvisorsnw.com/author/portfolio-manager/)
**Categories:** All Posts
---
### [The Financial Quarterly Q4 2021](https://independentadvisorsnw.com/the-financial-quarterly-q4-2021/)
**Published:** January 13, 2022
**Author:** Investment Advisor
**Excerpt:** Markets delivered exceptional performance in a year that had a little bit of everything: politics, bubbles, meme stocks, inflation, runaway rallies, and sudden drops. Let's take a look at how markets performed last year and what we might look forward to in the first months of 2022.
**Content:**
[< back to Market Insights Blog](https://independentadvisorsnw.com/homepage/markets-insights/)
The Financial Quarterly
# The Financial Quarterly
4th Quarter 2021

Goran Ognjenovic
https://independentadvisorsnw.com
**Independent Investment Advisors**
(971) 350-8068
Markets delivered exceptional performance in a year that had a little bit of everything: politics, bubbles, meme stocks, inflation, runaway rallies, and sudden drops. Let's take a look at how markets performed last year and what we might look forward to in the first months of 2022.
Looking Back
### How Did Markets Perform Last Year?
### S&P 500
The broader U.S. market soared in 2021, despite worries about inflation and variants.1
### NASDAQ
The tech-focused NASDAQ delivered a strong year on a new technology boom.1
### DOW 30
Blue chip stocks grew strongly in 2021 on solid corporate earnings.1
Looking Ahead
### What Can We Expect 3-9 Months Ahead?3
### U.S. Economic Outlook
 Negative Positive
The U.S. economy is positioned for continued growth in 2022, but the pace of the recovery may slow as the easy gains are likely behind us.2
### Equity Outlook
 Negative Positive
Stocks look to still have room to grow this quarter, but obstacles could lead to plenty of volatility and potentially even a correction.3
### Consumer Spending
 Negative Positive
Consumer spending looks positive as Americans look to keep shopping in 2022.4
### Labor Market
 Negative Positive
The labor market is expected to remain strong, though labor shortages in certain sectors could lead to uneven growth.5
### Business Outlook Survey
 Negative Positive
The business environment looks solid as workers return and consumers spend, though inflation and supply chain issues may weigh.6
### Fiscal Policy
 Negative Positive
Fiscal policy is expected to tighten in 2022 as pandemic supports are removed, though infrastructure spending may support medium-term growth.7

> "While pandemic disruptions remain, 2022 offers hopes of greater normalcy."

## Not receiving our newsletter? Get insightful info on finances and more in your inbox every month with the Insider's List.
Contact me by FAX only?
Bottom Line
## Key Takeaways for Savvy Investors
Despite another year of uncertainty around COVID-19 variants, vaccines, and the economy, markets delivered an extraordinary performance in 2021. Looking back, while it's easy to cheer a strong year, let's not forget that there were many dips, pullbacks, and anxious moments along the way.
That's just part of the journey.
What can we look forward to in 2022?
Signs point to continued growth amid hope that variants will become less dangerous as treatments advance and humans (and our institutions) adapt.
However, much of the "easy" recovery from the pandemic bottom is behind us and inflation, supply chain snarls, and labor market shortages remain thorny issues.
Given the market highs we’ve seen recently, volatility and pullbacks are very likely.
Overall, I'm cautiously optimistic about this quarter’s trajectory. However, I'm also keeping a close eye on market conditions, as continued uncertainty could drive sudden changes.
Questions? Please reach out. I'd be happy to chat.
Goran Ognjenovic
Independent Investment Advisors
(971) 350-8068
info@independentadvisorsnw.com

**Sources:**
1
2
3
4
5 [https://www.cnn.com/2021/12/03/perspectives/jobs-labor-market-trends-2022/index.html](https://www.cnn.com/2021/12/03/perspectives/jobs-labor-market-trends-2022/index.html)
6 [https://www.cnbc.com/2021/12/16/why-former-us-treasurer-is-optimistic-about-economy-in-2022.html](https://www.cnbc.com/2021/12/16/why-former-us-treasurer-is-optimistic-about-economy-in-2022.html)
7
U.S. Economic Outlook, Equity Outlook, Consumer Spending, Labor Market, Business Outlook, and Fiscal Policy gauges: (December 2021)
The S&P 500 is a stock index considered to be representative of the U.S. stock market in general. The NASDAQ Composite Index is an unmanaged composite index of over 2,500 common equities listed on the NASDAQ stock exchange. The Dow Jones Industrial Average is a price-weighted index that tracks 30 large, publicly traded American companies.
All index returns exclude reinvested dividends and interest. Indices are unmanaged and cannot be invested into directly.
Risk Disclosure: Investing involves risk including the potential loss of principal. No investment strategy can guarantee a profit or protect against loss in periods of declining values. Past performance does not guarantee future results.
This material is for information purposes only and is not intended as an offer or solicitation with respect to the purchase or sale of any security. This content may contain projections, forecasts, and other forward-looking statements that do not reflect actual results and are based on hypotheses, assumptions, and historical financial information. The content is developed from sources believed to be providing accurate information; no warranty, expressed or implied, is made regarding accuracy, adequacy, completeness, legality, reliability, or usefulness of any information. Consult your financial professional before making any investment decision. For illustrative use only.
The following posts and commentary are to be used solely as educational tools and do not contain investment advice. Investment advice must be tailored to a particular investor’s specific needs. None of the information contained should be construed to be investment advice. Individuals wishing to tailor a plan to their own needs should seek the help of a Registered Investment Advisor.
There is a high degree of risk in investing and trading. Independent Investment Advisors assumes no responsibility. Principles of Independent Investment Advisors may, at times, maintain directly or indirectly, positions in securities or derivatives mentioned in these comments.
##### You're Signed Up!
 **Goran Ognjenovic
Independent Investment Advisors** Stay tuned — an email from me is on its way to your inbox right now.
Close
[ **(971) 350-8068** ]()
[ **Email Me** ](mailto:info@independentadvisorsnw.com)
[ **Visit Website** ](https://independentadvisorsnw.com "https://iiaproduction.wpengine.com")

Investment Advisor
[See Full Bio](https://independentadvisorsnw.com/author/investment-advisor/) [ ](https://independentadvisorsnw.com/author/investment-advisor/)
**Categories:** Portfolio & Market Reviews
---
### [The Financial Quarterly Q3 2021](https://independentadvisorsnw.com/the-financial-quarterly-q3-2021/)
**Published:** October 8, 2021
**Author:** Investment Advisor
**Excerpt:** Despite breaking multiple records, a rocky third quarter ended with a thud as concerns about inflation, political brawls, and viral variants weighed.
**Content:**
[< back to Market Insights Blog](https://independentadvisorsnw.com/homepage/markets-insights/)
The Financial Quarterly
# The Financial Quarterly
3rd Quarter 2021

Goran Ognjenovic
https://independentadvisorsnw.com
**Independent Investment Advisors**
(971) 350-8068
Despite breaking multiple records, a rocky third quarter ended with a thud as concerns about inflation, political brawls, and viral variants weighed.1
Let's take a look at how markets performed and what we might look forward to in the months to come.
Looking Back
### How Did Markets Perform Last Quarter?
### S&P 500
The broader U.S. market ended Q3 flat.2
### NASDAQ
The tech-focused NASDAQ was rocked by volatility, but closed Q3 only slightly down.2
### DOW 30
Blue chip stocks also fell victim to fears of higher interest rates ahead, ending Q3 negative.2
Looking Ahead
### What Can We Expect 3-9 Months Ahead?3
### U.S. Economic Outlook
 Negative Positive
The U.S. economy continues to recover though the delta variant may weigh on near-term growth.4
### Equity Outlook
 Negative Positive
Though equities could still have room to grow in the months ahead, a correction would not be surprising.5
### Consumer Sentiment
 Negative Positive
Consumer sentiment remains positive, but concerns about a slowing recovery could weigh.6
### Labor Market
 Negative Positive
The labor market continues to grow, though challenges matching open jobs with available workers remain.4
### Business Outlook Survey
 Negative Positive
The overall business outlook looks positive heading into the close of the year, though supply chain woes may continue.4
### Fiscal Policy
 Negative Positive
Though prospective government policies look to support near-term economic growth, some have concerns about long-term debt.4

> "As we head toward the finish line, we see some clouds on the horizon; however, we still hope for a solid end to the year."

## Not receiving our newsletter? Get insightful info on finances and more in your inbox every month with the Insider's List.
Contact me by FAX only?
Bottom Line
## Key Takeaways for Savvy Investors
2021 opened with great optimism and hope that vaccines would put the pandemic in the rearview mirror.
The year so far had a lot of highlights: the U.S. economy roared back from its 2020 recession, personal incomes hit a high mark, home values increased, and U.S. companies enjoyed record profitability.7,8,9,10
All that optimism has led to record-breaking stock performance (50+ all-time-highs in 2021), causing the S&P 500 to double in less than a year.11,12
But, the clouds on the horizon could lead to more choppy seas. Maybe even a storm.
There are a few things I’m watching as we head toward the close of 2021:
- New COVID-19 variants
- Higher inflation
- Fed tapering
- Political and geopolitical concerns
- Economic growth
- The rising debt burden
Since markets are cyclical, the good times are bound to end, and now is a good time to be cautious.
The flipside is that rocky times don’t last forever either.
Bottom line, I'm keeping a close eye on conditions and staying flexible.
Questions about what’s going on? Please reach out. I'd be happy to chat.
Goran Ognjenovic
Independent Investment Advisors
(971) 350-8068
info@independentadvisorsnw.com

**Sources:**
1
2
3 U.S. Economic Outlook, Equity Outlook, Consumer Sentiment, Labor Market, Business Outlook, and Fiscal Policy gauges: (September 2021)
4
5
6
7
8
9
10
11
12 [https://www.yahoo.com/now/p-500-jumps-more-double-101210806.html](https://www.yahoo.com/now/p-500-jumps-more-double-101210806.html#:~:text=Per%20CNBC%20analysis%2C%20the%20S%26P,bottom%2C%20since%20World%20War%20II.)
S&P 500: (Closing price performance between June 30, 2021 and September 30, 2021)
NASDAQ: (Closing price performance between June 30, 2021 and September 30, 2021)
Dow Jones Industrial Average: (Closing price performance between June 30, 2021 and September 30, 2021)
The S&P 500 is a stock index considered to be representative of the U.S. stock market in general. The NASDAQ Composite Index is an unmanaged composite index of over 2,500 common equities listed on the NASDAQ stock exchange. The Dow Jones Industrial Average is a price-weighted index that tracks 30 large, publicly traded American companies.
All index returns exclude reinvested dividends and interest. Indices are unmanaged and cannot be invested into directly.
Risk Disclosure: Investing involves risk including the potential loss of principal. No investment strategy can guarantee a profit or protect against loss in periods of declining values. Past performance does not guarantee future results.
This material is for information purposes only and is not intended as an offer or solicitation with respect to the purchase or sale of any security. This content may contain projections, forecasts, and other forward-looking statements that do not reflect actual results and are based on hypotheses, assumptions, and historical financial information. The content is developed from sources believed to be providing accurate information; no warranty, expressed or implied, is made regarding accuracy, adequacy, completeness, legality, reliability or usefulness of any information. Consult your financial professional before making any investment decision. For illustrative use only.
The following posts and commentary are to be used solely as educational tools and do not contain investment advice. Investment advice must be tailored to a particular investor’s specific needs. None of the information contained should be construed to be investment advice. Individuals wishing to tailor a plan to their own needs should seek the help of a Registered Investment Advisor.
There is a high degree of risk in investing and trading. Independent Investment Advisors assumes no responsibility. Principles of Independent Investment Advisors may, at times, maintain directly or indirectly, positions in securities or derivatives mentioned in these comments.
##### You're Signed Up!
 **Goran Ognjenovic
Independent Investment Advisors** Stay tuned — an email from me is on its way to your inbox right now.
Close
[ **(971) 350-8068** ]()
[ **Email Me** ](mailto:info@independentadvisorsnw.com)
[ **Visit Website** ](https://independentadvisorsnw.com "https://iiaproduction.wpengine.com")

Investment Advisor
[See Full Bio](https://independentadvisorsnw.com/author/investment-advisor/) [ ](https://independentadvisorsnw.com/author/investment-advisor/)
**Categories:** Portfolio & Market Reviews
---
### [The Financial Quarterly Q2 2021](https://independentadvisorsnw.com/the-financial-quarterly-q2-2021/)
**Published:** July 15, 2021
**Author:** Investment Advisor
**Excerpt:** The second quarter of 2021 had a little bit of everything: vaccines, inflation concerns, jobs recovery, and more. Let's take a look at how markets performed and what we might look forward to in the months to come.
**Content:**
[< back to Market Insights Blog](https://independentadvisorsnw.com/homepage/markets-insights/)
The Financial Quarterly
# The Financial Quarterly
2nd Quarter 2021

Goran Ognjenovic
https://independentadvisorsnw.com
**Independent Investment Advisors**
(971) 350-8068
The second quarter of 2021 had a little bit of everything: vaccines, inflation concerns, jobs recovery, and more. Let's take a look at how markets performed and what we might look forward to in the months to come.
Looking Back
### How Did Markets Perform Last Quarter?
### S&P 500
Despite considerable volatility, the broader U.S. market grew strongly in Q2.1
### NASDAQ
The tech-focused NASDAQ soared on the back of a sustained tech rally after pulling back in mid-quarter.1
### DOW 30
Blue chip stocks delivered solid growth despite ongoing inflation and interest rate fears.1
Looking Ahead
### What Can We Expect Three to Nine Months Ahead?
### U.S. Economic Outlook
 Negative Positive
The U.S. economy looks to be on a clear path for growth as the recovery continues.2
### Equity Outlook
 Negative Positive
Market fundamentals could support continued growth though volatility is very likely.3
### Consumer Sentiment
 Negative Positive
Consumer sentiment is very strong as Americans look forward to a post-pandemic world with ample cash in their pockets.4,5
### Labor Market
 Negative Positive
The labor market shows strength, though some sectors and regions may struggle to match workers with roles.6
### Business Outlook Survey
 Negative Positive
The business outlook looks solid as demand picks up, though inflation and supply chain issues may be obstacles.5
### Fiscal Policy
 Negative Positive
Government policies could support further growth, though waning stimulus spending and debt concerns may cause bumps.5

> "Despite fears of runaway inflation and pandemic-related challenges, markets delivered a strong performance in Q2. While obstacles to growth remain, we expect the economic recovery to continue this quarter."

## Not receiving our newsletter? Get insightful info on finances and more in your inbox every month with the Insider's List.
Contact me by FAX only?
Bottom Line
## Key Takeaways for Savvy Investors
Despite a lot of uncertainty around business reopenings, vaccination rates, and economic growth, equities delivered a solid performance in the second quarter, closing out the strongest first half since 2019.7
While the quarter closed strong, a number of dips, rallies, and ongoing volatility made it a bumpy road. We can expect more of this as the world continues to recover from the pandemic.
With all the uncertainty, it would not be surprising to see a market correction or pullback in the months ahead.
Overall, the economy seems positioned for strong growth in the second half of the year, though inflation worries, politics, and post-pandemic concerns may weigh.
Bottom line, I'm keeping a close eye on market conditions, as continued uncertainty could drive sudden changes.
Questions? Please reach out. I'd be happy to chat.
Goran Ognjenovic
Independent Investment Advisors
(971) 350-8068
info@independentadvisorsnw.com

**Sources:**
1
2
3
4
5
6
7
S&P 500: (Closing price performance between March 31, 2021 and June 30, 2021)
NASDAQ: (Closing price performance between March 31, 2021 and June 30, 2021)
Dow Jones Industrial Average: (Closing price performance between March 31, 2021 and June 30, 2021)
U.S. Economic Outlook, Equity Outlook, Consumer Sentiment, Labor Market, Business Outlook, and Fiscal Policy gauges: (July 2021)
The S&P 500 is a stock index considered to be representative of the U.S. stock market in general. The NASDAQ Composite Index is an unmanaged composite index of over 2,500 common equities listed on the NASDAQ stock exchange. The Dow Jones Industrial Average is a price-weighted index that tracks 30 large, publicly traded American companies.
All index returns exclude reinvested dividends and interest. Indices are unmanaged and cannot be invested into directly.
Risk Disclosure: Investing involves risk including the potential loss of principal. No investment strategy can guarantee a profit or protect against loss in periods of declining values. Past performance does not guarantee future results.
This material is for information purposes only and is not intended as an offer or solicitation with respect to the purchase or sale of any security. This content may contain projections, forecasts, and other forward-looking statements that do not reflect actual results and are based on hypotheses, assumptions, and historical financial information. The content is developed from sources believed to be providing accurate information; no warranty, expressed or implied, is made regarding accuracy, adequacy, completeness, legality, reliability or usefulness of any information. Consult your financial professional before making any investment decision. For illustrative use only.
The following posts and commentary are to be used solely as educational tools and do not contain investment advice. Investment advice must be tailored to a particular investor’s specific needs. None of the information contained should be construed to be investment advice. Individuals wishing to tailor a plan to their own needs should seek the help of a Registered Investment Advisor.
There is a high degree of risk in investing and trading. Independent Investment Advisors assumes no responsibility. Principles of Independent Investment Advisors may, at times, maintain directly or indirectly, positions in securities or derivatives mentioned in these comments.
##### You're Signed Up!
 **Goran Ognjenovic
Independent Investment Advisors** Stay tuned — an email from me is on its way to your inbox right now.
Close
[ **(971) 350-8068** ]()
[ **Email Me** ](mailto:info@independentadvisorsnw.com)
[ **Visit Website** ](https://independentadvisorsnw.com "https://iiaproduction.wpengine.com")

Investment Advisor
[See Full Bio](https://independentadvisorsnw.com/author/investment-advisor/) [ ](https://independentadvisorsnw.com/author/investment-advisor/)
**Categories:** All Posts, Portfolio & Market Reviews
---
### [Q2 2020 – Quarterly Portfolio Review](https://independentadvisorsnw.com/q2-2020-quarterly-portfolio-review/)
**Published:** July 22, 2020
**Author:** Portfolio Manager
**Content:**
# **Overview**
In this quarterly post, we review the composition and the performance of several investment portfolios managed by our Investment Advisor. Portfolios we review are actual live portfolios for several different clients and range from a conservative client who is already in retirement and looking for income to a very aggressive portfolio set up for young children with a 30-year investment horizon. The purpose of this post is to educate our investors and clients and help set expectations on how different portfolios perform over time. It also showcases how we think about and manage capital assets. We also show “Advisor View” which is an overview of the composition and performance of all portfolios under our management.
## Advisors View
Advisors view includes all accounts and all allocated portfolios under our management. Its snapshot of the advisor dashboard we look at every day.
**Investment Performance**
Q1 2020Q2 2020Q3 2020Q4 2020-12.42%10.51%
**Asset Class Allocation**
*Long**Short*Equities49.32%4.22%Fixed Income26.17%0.00%Real Estate7.97%0.17%Other Assets0.12%5.78%Fund Cash16.21%85.76%
**Geographic Allocation**
*Long**Short*North America88.28%94.17%Asia5.38%0.00%Europe4.25%0.02%South America0.82%0.00%Africa0.51%0.00%Oceania0.39%0.00%Other0.37%5.81%
**Sector Allocation**
*Long**Short*Basic Materials1.20%0.00%Cons Cyclical4.91%0.00%Cons Non-Cyclical2.37%0.00%Energy3.68%0.00%Financials8.52%3.70%Healthcare6.71%0.24%Industrial6.33%0.23%Real Estate7.98%0.17%Technology11.81%0.01%Telecom Services2.70%0.00%Utilities1.44%0.00%Cash16.21%85.76%Fund Cash0.21%4.08%Unclassified25.92%5.81%
## Retiree Portfolio
- The client is already in retirement (as of 1/1/2020)
- The client needs 20 years (estimated) of income and capital preservation
- The client will not contribute to the portfolio
- Investment portfolio is in conservative allocation
**Investment Performance**
Q1 2020Q2 2020Q3 2020Q4 2020-4.29%3.63%
**Asset Class Allocation**
*Long**Short*Equities19.91%50.49%Fixed Income79.48%0.00%Real Estate0.41%0.00%Other Assets0.08%1.71%Fund Cash0.06%2.70%
**Geographic Allocation**
*Long**Short*North America94.75%98.24%Asia2.24%0.04%Europe2.24%0.02%South America0.60%0.00%Africa0.39%0.00%Oceania0.13%0.00%Other0.09%1.71%
**Sector Allocation**
*Long**Short*Basic Materials0.56%0.00%Cons Cyclical2.04%0.00%Cons Non-Cyclical3.82%0.00%Energy1.45%0.00%Financials2.67%0.00%Healthcare2.72%0.00%Industrial1.26%0.00%Real Estate0.42%0.00%Technology2.88%0.00%Telecom Services1.21%0.00%Utilities2.98%0.00%Cash0.06%45.09%Fund Cash0.06%2.70%Unclassified77.87%1.71%
## Retirement IRA Portfolio
- The client is currently working and is looking toward a 20/25-year time horizon before retirement (as of 1/1/2019)
- The client will make an annual contribution based on annual maximums
- Investment portfolio is in mid-to-aggressive allocation
**Investment Performance**
Q1 2020Q2 2020Q3 2020Q4 2020-22.44%17.41%**Asset Class Allocation**
*Long**Short*Equities73.66%0.58%Fixed Income16.67%0.00%Real Estate8.34%0.00%Other Assets0.12%14.25%Fund Cash0.50%85.16%
**Geographic Allocation**
*Long**Short*North America79.26%84.98%Asia9.64%0.03%Europe7.19%0.16%South America1.39%0.00%Africa1.08%0.00%Oceania0.61%0.00%Other0.82%14.48%
**Sector Allocation**
*Long**Short*Basic Materials2.60%0.00%Cons Cyclical9.16%0.00%Cons Non-Cyclical3.64%0.00%Energy5.61%0.00%Financials14.17%0.00%Healthcare8.04%0.00%Industrial6.98%0.00%Real Estate8.44%0.00%Technology17.38%0.00%Telecom Services4.89%0.00%Utilities2.42%0.00%Cash0.63%0.00%Fund Cash0.46%85.16%Unclassified15.55%14.84%
## Trust Brokerage Account for Children
- The revocable trust is created with a 30-year time horizon (as of 1/1/2019)
- The trustee will make modest but continuous monthly contribution
- Investment portfolios is in aggressive allocation
- Investment portfolio uses margin
- \*\* Portfolio was 50% margined in late February 2020
Q1 2020Q2 2020Q3 2020Q42020-38.30%44.55%**Asset Class Allocation**
*Long**Short*Equities94.02%0.01%Fixed Income0.05%0.00%Real Estate5.26%0.00%Other Assets0.14%0.28%Fund Cash0.13%99.65%
**Geographic Allocation**
*Long**Short*North America84.52%99.70%Asia9.77%0.00%Europe3.99%0.00%South America0.89%0.00%Africa0.42%0.00%Oceania0.22%0.00%Other0.18%0.29%
**Sector Allocation**
*Long**Short*Basic Materials2.64%0.00%Cons Cyclical12.25%0.00%Cons Non-Cyclical4.37%0.00%Energy4.75%0.00%Financials10.24%0.00%Healthcare10.44%0.00%Industrial7.75%0.00%Real Estate5.25%0.00%Technology26.99%0.00%Telecom Services7.20%0.00%Utilities2.10%0.00%Cash0.13%99.65%Fund Cash0.39%0.06%Unclassified5.49%0.29%

Portfolio Manager
[See Full Bio](https://independentadvisorsnw.com/author/portfolio-manager/) [ ](https://independentadvisorsnw.com/author/portfolio-manager/)
**Categories:** Portfolio & Market Reviews
---
### [Trading Equity Markets Around 2020 Election](https://independentadvisorsnw.com/trading-equity-markets-around-2020-election/)
**Published:** September 28, 2020
**Author:** Active Trader
**Excerpt:** Even though Joe Biden unveiled tax and business policies that are much more moderate than initially expected, we are looking at substantially increased volatility in the equity markets as we approach the November election
**Content:**
Even though presidential candidate Joe Biden unveiled tax and business policies that are much more moderate than initially expected, we are looking at substantially increased volatility in the equity markets as we approach the November election. Implied volatilities in options are, in some cases, very high. Our custodian partners are increasing margin requirements to help stem some of the volatility.
Margin requirements will increase by as much as 35% above standard margin requirements leading up to the November U.S. election. To illustrate, consider a Reg. T margin account with stock XYZ having an Initial Margin requirement of 50% and a Maintenance Margin requirement of 25%. With the increase fully implemented, the new requirements would be 67.5% Initial and 33.75% Maintenance. Accounts subject to risk-based margin will have their scanning ranges increased similarly.
This will be implemented each day gradually, increasing Initial margin requirements from normal levels starting September 28th to a rate that will be 35% higher by October 23rd. Maintenance margin requirements will grow similarly between October 5th and October 30th. The new requirements will be implemented each day after the market closes in New York and will be effective on the next trading day.

Active Trader
[See Full Bio](https://independentadvisorsnw.com/author/active-trader/) [ ](https://independentadvisorsnw.com/author/active-trader/)
**Categories:** Active Trading, All Posts
---
### [When Advisors Can't Access Your ETF?](https://independentadvisorsnw.com/when-advisors-cant-access-your-etf/)
**Published:** September 30, 2020
**Author:** Investment Advisor
**Excerpt:** This is a great article highlighting the significant value and the advantage Independent Registered Investment Advisors (RIA) have over traditional wirehouse advisors. Jillian DelSignore from ETF.com covers the distribution issues and challenges of Exchange Traded Funds (ETF).
**Content:**
This is a great article highlighting the significant value and the advantage Independent Registered Investment Advisors (RIA) have over traditional wirehouse advisors. Jillian DelSignore from ETF.com covers the distribution issues and challenges of Exchange Traded Funds (ETF).
“For the advisor, however, it’s: Can they access the ETFs they want for their clients? That may sound like a given, but it’s far from it.”
“For example, as an RIA, an advisor can access any ETF they want. Depending on where they custody their assets, some of those ETFs are commission-free, even though that became irrelevant last year when the major custodians entirely did away with commissions on ETFs. As an RIA, the ETF world is your oyster.
Now, if you instead are an advisor at, say, Morgan Stanley or Wells Fargo, the ETF world is not your oyster. Your world consists of a subset of ETFs on the market based on what your platform has approved for your access. Keep in mind that this is not unique to those two firms.”
You can find the complete article at

Investment Advisor
[See Full Bio](https://independentadvisorsnw.com/author/investment-advisor/) [ ](https://independentadvisorsnw.com/author/investment-advisor/)
**Categories:** All Posts, Investment Advisor
---
### [We are thrilled to announce our third managed portfolio program: Structured or Defined Outcome Portfolio](https://independentadvisorsnw.com/we-are-thrilled-to-announce-our-third-managed-portfolio-program-structured-or-defined-outcome-portfolio/)
**Published:** September 15, 2020
**Author:** Portfolio Manager
**Content:**
This portfolio program is well suited for a general investment or savings portfolio—an investor looking to grow their investment at a moderate rate without a long-term investment horizon. Perhaps even for a real estate investor looking to diversify. The portfolio approach primarily consists of US registered index ETF’s and derivatives, more specifically, options. The portfolio approach also takes advantage of leverage (margin). The advisor is actively engaged in managing positions based on the current market and economic trends.

Portfolio Manager
[See Full Bio](https://independentadvisorsnw.com/author/portfolio-manager/) [ ](https://independentadvisorsnw.com/author/portfolio-manager/)
**Categories:** News and Announcements
---
### [We expanded our custodian and technology provider agreements to include Wedbush Securities Institutional Advanced Clearing Services.](https://independentadvisorsnw.com/we-expanded-our-custodian-and-technology-provider-agreements-to-include-wedbush-securities-institutional-advanced-clearing-services/)
**Published:** January 15, 2020
**Author:** Investment Advisor
**Content:**
We are happy to announce that we have expanded our custodial network to include Wedbush Securities Institutional. As a clearing leader for over 40 years, Wedbush Securities Advanced Clearing Services specializes in providing custom tailored clearing and custody and full-service solutions.

Investment Advisor
[See Full Bio](https://independentadvisorsnw.com/author/investment-advisor/) [ ](https://independentadvisorsnw.com/author/investment-advisor/)
**Categories:** News and Announcements
---
### [We expanded our custodian and technology provider agreements to include Charles Schwab Institutional.](https://independentadvisorsnw.com/we-expanded-our-custodian-and-technology-provider-agreements-to-include-charles-schwab-institutional/)
**Published:** August 7, 2020
**Author:** Investment Advisor
**Content:**
We are happy to announce that we have expanded our custodial network to include Charles Schwab. Schwab is an industry leader—proudly supporting more independent advisors than any other custodian. Our new relationship allows our allocated portfolio clients to diversify and expand their portfolios, especially in fixed income space.

Investment Advisor
[See Full Bio](https://independentadvisorsnw.com/author/investment-advisor/) [ ](https://independentadvisorsnw.com/author/investment-advisor/)
**Categories:** News and Announcements
---
### [Our Trading-Tools API Engine Is Live](https://independentadvisorsnw.com/our-tradingtools-api-engine-is-live/)
**Published:** February 13, 2020
**Author:** Active Trader
**Content:**
We are thrilled to announce that after roughly 18 months of development, our Trading-Tools Real Tick API engine is live and performing as expected. We now can build granular and highly customized market scans, automated trading systems and rules, and place, manage, and allocate orders into various portfolios.

Active Trader
[See Full Bio](https://independentadvisorsnw.com/author/active-trader/) [ ](https://independentadvisorsnw.com/author/active-trader/)
**Categories:** News and Announcements
---
### [May 2020 Market(s) Insights: Economic Indicators](https://independentadvisorsnw.com/may-2020-markets-insights-economic-indicators/)
**Published:** June 8, 2020
**Author:** Investment Advisor
**Content:**
In this May 2020 monthly edition of Market(s) Insights analysis videos, our Chief Investment Advisor reviews the relevant economic indicators and stock market impacts of the reported financial data. It’s a first in a series of three videos covering economic indicators, performance of sample portfolios, and stock market activity.
May 2020 Market(s) Insights: Economic Indicators 
Investment Advisor
[See Full Bio](https://independentadvisorsnw.com/author/investment-advisor/) [ ](https://independentadvisorsnw.com/author/investment-advisor/)
**Categories:** Portfolio & Market Reviews
---
### [May 2020 Market(s) Insights: Sample Portfolios](https://independentadvisorsnw.com/may-2020-markets-insights-sample-portfolios/)
**Published:** June 8, 2020
**Author:** Portfolio Manager
**Content:**
In this May 2020 monthly edition of Market(s) Insights analysis videos, our Portfolio Manager reviews the sample portfolios we are tracking. Portfolio performance and asset allocations are reviewed. It’s a second in three videos covering economic indicators, performance of sample portfolios, and stock market activity.
May 2020 Market(s) Insights: Sample Portfolios 
Portfolio Manager
[See Full Bio](https://independentadvisorsnw.com/author/portfolio-manager/) [ ](https://independentadvisorsnw.com/author/portfolio-manager/)
**Categories:** Portfolio & Market Reviews
---
### [House Democrats propose eliminating $10,000 limit on state and local tax deductions](https://independentadvisorsnw.com/house-democrats-propose-eliminating-10000-limit-on-state-and-local-tax-deductions/)
**Published:** December 10, 2019
**Author:** Financial Planner
**Excerpt:** Oregon investors should keep an eye on this development. With Oregon Income Tax hovering around 10% for many investors property taxes and other municipal taxes don't make the cut.
**Content:**
Oregon investors should keep an eye on this development. With Oregon Income Tax hovering around 10% for many investors, property taxes, and other municipal taxes, don’t make the cut.

Financial Planner
[See Full Bio](https://independentadvisorsnw.com/author/financial-planner/) [ ](https://independentadvisorsnw.com/author/financial-planner/)
**Categories:** All Posts
---
### [What are the election impacts on the equity markets?](https://independentadvisorsnw.com/what-are-the-election-impacts-on-the-equity-markets/)
**Published:** February 14, 2020
**Author:** Investment Advisor
**Content:**
In my January 2020 equity markets overview video, I discussed how I am looking to manage client’s equity portfolios in 2020 as we approach the election later in the year. Here is a brief video from NYSE covering the historical impacts of elections.
[https://www.linkedin.com/posts/bettywliu\_do-election-years-affect-the-market-i-tell-activity-6628326847966924800-RAhW](https://www.linkedin.com/posts/bettywliu_do-election-years-affect-the-market-i-tell-activity-6628326847966924800-RAhW)

Investment Advisor
[See Full Bio](https://independentadvisorsnw.com/author/investment-advisor/) [ ](https://independentadvisorsnw.com/author/investment-advisor/)
**Categories:** All Posts
---
### [IRA to Roth IRA Conversion](https://independentadvisorsnw.com/ira-to-roth-ira-conversion/)
**Published:** April 3, 2020
**Author:** Financial Planner
**Content:**
With markets correcting now is the perfect time to take a look at, and to act on your IRA to Roth IRA conversion. The conversion TAX bill would be substantially less, and then the portfolio growth is TAX-free. Give me a call if you have questions or want me to run some numbers for you!

Financial Planner
[See Full Bio](https://independentadvisorsnw.com/author/financial-planner/) [ ](https://independentadvisorsnw.com/author/financial-planner/)
**Categories:** All Posts
---
### [Indicators and trends suggest that the U.S. equity market is starting to normalize.](https://independentadvisorsnw.com/indicators-and-trends-suggest-that-the-u-s-equity-market-is-starting-to-normalize/)
**Published:** April 28, 2020
**Author:** Active Trader
**Content:**
Indicators and trends suggest that the U.S. equity market is starting to normalize. See the Nasdaq Chief Economist’s video. I also concur as data and indicators I look at are “calming down.” All that said, VIX is still quite elevated. As an active trader, it’s a bittersweet moment as higher volatility can be more profitable.
[https://www.linkedin.com/posts/nasdaq\_tradetalks-activity-6660922515604541440-D4\_w](https://www.linkedin.com/posts/nasdaq_tradetalks-activity-6660922515604541440-D4_w)

Active Trader
[See Full Bio](https://independentadvisorsnw.com/author/active-trader/) [ ](https://independentadvisorsnw.com/author/active-trader/)
**Categories:** Active Trading, All Posts
---
### [Market(s) Insights March 2020](https://independentadvisorsnw.com/markets-insights-march-2020/)
**Published:** April 7, 2020
**Author:** Investment Advisor
**Content:**
It is Market(s) Insights March 2020 edition. There is quite a bit of new content in the March video. I have added Economic Indicators and sample portfolios that I will be tracking moving forward.

Investment Advisor
[See Full Bio](https://independentadvisorsnw.com/author/investment-advisor/) [ ](https://independentadvisorsnw.com/author/investment-advisor/)
**Categories:** Portfolio & Market Reviews
---
### [February 2020 Markets Overview](https://independentadvisorsnw.com/february-2020-markets-overview/)
**Published:** March 9, 2020
**Author:** Investment Advisor
**Content:**
In my February 2020 equity markets overview video, I discuss how I am looking to manage client’s equity portfolios in 2020. I also review the current market sell-off and the importance of portfolio construction.

Investment Advisor
[See Full Bio](https://independentadvisorsnw.com/author/investment-advisor/) [ ](https://independentadvisorsnw.com/author/investment-advisor/)
**Categories:** Portfolio & Market Reviews
---
### [January 2020 Market Overview](https://independentadvisorsnw.com/january-2020-market-overview/)
**Published:** January 24, 2020
**Author:** Investment Advisor
**Content:**
******In January 2020 Markets Overview video, I outline where we are in the capital investment cycle and how I am looking to handle our equity weighted portfolios.******

Investment Advisor
[See Full Bio](https://independentadvisorsnw.com/author/investment-advisor/) [ ](https://independentadvisorsnw.com/author/investment-advisor/)
**Categories:** Portfolio & Market Reviews
---
### [How Roth IRA conversions can escalate capital gains taxes](https://independentadvisorsnw.com/how-roth-ira-conversions-can-escalate-capital-gains-taxes/)
**Published:** December 12, 2019
**Author:** Financial Planner
**Content:**
A great article from Financial-Planning.com. A must-read for anyone considering the IRA to Roth conversion.

Financial Planner
[See Full Bio](https://independentadvisorsnw.com/author/financial-planner/) [ ](https://independentadvisorsnw.com/author/financial-planner/)
**Categories:** All Posts
---
### [House passes bill to lift $10,000 cap on state and local tax deductions](https://independentadvisorsnw.com/house-passes-bill-to-lift-10000-cap-on-state-and-local-tax-deductions/)
**Published:** December 20, 2019
**Author:** Financial Planner
**Content:**
This post is an update to my 12/10 post. Oregon investors need to continue to keep an eye on this development.
- The “Restoring Tax Fairness for States and Localities Act” would eliminate the $10,000 limit on state and local tax deductions for 2020 and 2021.
- On Thursday, the House narrowly voted to pass the bill, 218-206, largely along party lines. The measure is unlikely to make it through the Senate.
- This bill calls for increasing the SALT-cap to $20,000 for married couples filing jointly in 2019, as well as raising the highest marginal tax income tax rate to 39.6%.

Financial Planner
[See Full Bio](https://independentadvisorsnw.com/author/financial-planner/) [ ](https://independentadvisorsnw.com/author/financial-planner/)
**Categories:** All Posts
---
### [SEC steps in to prevent investors from buying the wrong Zoom](https://independentadvisorsnw.com/sec-steps-in-to-prevent-investors-from-buying-the-wrong-zoom/)
**Published:** April 1, 2020
**Author:** Active Trader
**Content:**
I honestly don’t even know what to say about this one. The old Wall Street adage rings true. People, people, you have to understand what you are trading.

Active Trader
[See Full Bio](https://independentadvisorsnw.com/author/active-trader/) [ ](https://independentadvisorsnw.com/author/active-trader/)
**Categories:** All Posts
---
## Pages
### [Fee-Only Independent Financial Advisors | Fiduciary Wealth Management](https://independentadvisorsnw.com/)
**Published:** September 18, 2019
**Author:** Investment Advisor
**Content:**
## We help clients achieve their goals with customized, comprehensive strategies for financial, investment, equity compensation, risk, and tax planning.
---
# We help busy [technology professionals](https://independentadvisorsnw.com/wealth-management-for-tech-professionals-in-portland-hillsboro-beaverton-and-seattle/), [small business owners](https://independentadvisorsnw.com/solutions/financial-investment-solutions-for-small-business-owners/), corporate executives and families in NW build and preserve their financial affluence.
---
## Independent, Fiduciary, Fee-Only Advisor
[Wealth Management](https://independentadvisorsnw.com/services/), [Retirement Planning](https://independentadvisorsnw.com/solutions/#Retirement-Planning), [Financial Planning](https://independentadvisorsnw.com/services/#Financial-Planning), [Inheritance Planning](https://independentadvisorsnw.com/solutions/#Inheritance-Planning), [Investment Management](https://independentadvisorsnw.com/solutions/#Investment-Portfolio-Management), [Tax Planning](https://independentadvisorsnw.com/solutions/#Tax-Optimization-Strategies), Education Planning, Small Business Solutions
[](https://independentadvisorsnw.com/marketing-and-promotional-disclaimer/)
****[SCHEDULE AN INTRODUCTORY MEETING](https://outlook.office365.com/book/IndependentInvestmentAdvisors@mlignw.com/)**** | **CALL 971.350.8068**
[](https://independentadvisorsnw.com/marketing-and-promotional-disclaimer/)
***As seen on***:
[](https://independentadvisorsnw.com/marketing-and-promotional-disclaimer/)
[](https://independentadvisorsnw.com/marketing-and-promotional-disclaimer/)
[](https://independentadvisorsnw.com/marketing-and-promotional-disclaimer/)
[](https://independentadvisorsnw.com/marketing-and-promotional-disclaimer/)
[](https://independentadvisorsnw.com/marketing-and-promotional-disclaimer/)
Disclosure: Awards and recognitions shown are based on independent or third-party evaluations; award does not evaluate or imply the quality of financial advice or investment services provided; and awards are not indicative of future performance. No compensation was provided for award consideration. The “As Seen On” media mentions (e.g., Forbes, MSN, USA Today, Nasdaq) represent paid promotional placements facilitated through a public relations agency and do not reflect editorial endorsements or independent reviews. Click on any of the images for additional details and full disclosures.
[](https://independentadvisorsnw.com/marketing-and-promotional-disclaimer/)Independent Investment Advisors Receives 2022 Best of Portland Award
[](https://independentadvisorsnw.com/marketing-and-promotional-disclaimer/)Independent Investment Advisors Receives 2023 Best of Portland Award
[](https://independentadvisorsnw.com/marketing-and-promotional-disclaimer/)Awarded a Five Star Wealth Manager Award
[](https://independentadvisorsnw.com/marketing-and-promotional-disclaimer/)Financial Advisory of the Year | Oregon by the Corporate Livewire and LTG USA Prestige Guide
[](https://independentadvisorsnw.com/marketing-and-promotional-disclaimer/)Awarded a Five Star Wealth Manager Award
Goran Ognjenovic Founder and Principal Advisor
---
## we **will** help you find a PATH TO YOUR FINANCIAL SUCCESS!
---
**We work with a limited number of clients, which means low advisor to client ratio, deeper relationships, custom financial plans, actual tax planning, custom portfolios, custom risk management, and better results. If your goals are achievable, we will help you find a way.**
---
[There are many financial advisors to choose from. Are we the right wealth advisor for you?](https://independentadvisorsnw.com/homepage/are-we-the-right-wealth-advisor-for-you/)
Goran,
I have enjoyed our time with you: You communicate very well; your response times have been good, and the information you provide has always been helpful. I trust you, and feel that you have our best interests at heart. I am glad to be with you during these uncertain times…..Doug
[](https://maps.google.com/?cid=18330541861740242939)
Doug Calder
1/20/2022
As a small business owner I must have someone who understands financial planning and investing who I can trust with my money and my time. I seriously cannot imagine going to someone other than Goran. I’ve had many negative experiences with CPA”s, attorneys, and other professionals who promise but do not deliver. Goran delivers and he does it in a way that feels holistic.
[](https://maps.google.com/?cid=18330541861740242939)
Slavica Kojadinovic
11/16/2021
Goran is a top notch Financial Advisor & Investor. He takes your full financial picture into view and helps you to prioritize financial planning over your lifetime. He is knowledgeable about most aspects of financial consideration and helps you to think through your decisions in a holistic manner. He is extremely trustworthy and professional and enjoyable to work with. I highly recommend Goran and the Independent Investment Advisors for your investment planning.
[](https://maps.google.com/?cid=18330541861740242939)
David Ryan
10/13/2021
Goran has been a great advisor to work with – for both planning and financial management services. The tools and software that we used are top-notch. Goran is incredibly responsive throughout all phases of working together. I would definitely recommend working with him.
[](https://www.google.com/maps/contrib/109856701524751372066/place/ChIJtW8Tko0JlVQR-2d0MbQqY_4)
Kraig Strong
6/30/2023
When looking for a fiduciary to help me with my finances I interviewed several candidates. Goran went above and beyond the others and my expectations. In several meetings he has created a comprehensive financial plan for my family, answered my questions and provides ongoing support. I highly recommend Independent Investment Advisors to help you achieve your financial goals.
[](https://www.google.com/maps/contrib/103492841262886338337/place/ChIJtW8Tko0JlVQR-2d0MbQqY_4)
Sean G
9/30/2023
Excellent customer service, follow up and knowledge. Having Goran manage our hard earned savings and IRA’s has eased our minds in a changing world. We highly recommend him to service your financial needs.
[](https://www.google.com/maps/contrib/113951739511551160604/place/ChIJtW8Tko0JlVQR-2d0MbQqY_4)
Cecilia Richardson
9/30/2023
Goran is a top notch Financial Advisor & Investor. He takes your full financial picture into view and helps you to prioritize financial planning over your lifetime. He is knowledgeable about most aspects of financial consideration and helps you to think through your decisions in a holistic manner. He is extremely trustworthy and professional and enjoyable to work with. I highly recommend Goran and the Independent Investment Advisors for your investment planning.
[](https://www.google.com/maps/contrib/115705237558304114535/place/ChIJtW8Tko0JlVQR-2d0MbQqY_4)
David Ryan
11/30/2021
It is a pleasure to give five stars. I highly recommend Goran. He is very professional and very down to earth. He is someone who listens, and is also reassuring. In the field of finance, it is rare to find someone so effective, and also calm and easy to deal with. I am thankful for his help.
[](https://www.google.com/maps/contrib/111111706184832871188/place/ChIJtW8Tko0JlVQR-2d0MbQqY_4)
Ross Weakley
1/05/2024
Goran is very good at what he does. His focus on our holistic finances and personal service is something you’ll never get from the ‘big guys’…Yet you’ll get the same benefits or more!
[](https://www.google.com/maps/contrib/101962548063760911543/place/ChIJtW8Tko0JlVQR-2d0MbQqY_4)
Kenny Sallee
1/05/2024
Goran is a fantastic advisors. He has been managing our HOA reserve funds and we have been able to keep our HOA dues fixed. He is very knowledgable about financial markets and ways to allocate capital in best risk/reward way.
[](https://www.google.com/maps/contrib/113242740393549888134/place/ChIJtW8Tko0JlVQR-2d0MbQqY_4)
Blackhawk Estates
1/20/2024
It is a pleasure to give five stars. I highly recommend Goran. He is very professional and very down to earth. He is someone who listens, and is also reassuring. In the field of finance, it is rare to find someone so effective, and also calm and easy to deal with. I am thankful for his help.
[](https://www.google.com/maps/contrib/111111706184832871188/place/ChIJtW8Tko0JlVQR-2d0MbQqY_4)
Ross W
1/05/2024
Thank you so much for being kind, and answering my questions! I appreciated your patience.
[](https://www.google.com/maps/contrib/103323544176315359323/place/ChIJtW8Tko0JlVQR-2d0MbQqY_4)
Blanca Reyes
5/10/2024
In rare form for me, I actually did a ton of research before hiring a financial advisor. It was important to me to find an independent fiduciary; a firm that can invest in any financial product, not just ones under an umbrella of products provided by a parent entity. I also wanted a fixed or capped fee; not a percentage of assets under management with no cap. Some of these firms charge insane, and often hidden fees, while being limited in what they can invest in. I’m so happy with Independent Investment Advisors! As a bonus, I really enjoy Goran’s personality and sense of humor. He’s incredibly thorough and I was surprised to find out how many ways this service is benefitting us; so much more than just investing. But make no mistake about it: Goran is a shrewd and sharp investor. Wise way beyond his years; level-headed, catering to whatever our needs are and we are grateful.
[](https://www.google.com/maps/contrib/106467900464553789239/place/ChIJtW8Tko0JlVQR-2d0MbQqY_4)
Dave Smith
5/13/2024
My financial situation does not require a financial planner right now. If I need one in the future, I will find one at this company. I appreciate that I was given time to express my concerns and then receive some advice and recommendations.
[](https://www.google.com/maps/contrib/106342480507154486285/place/ChIJtW8Tko0JlVQR-2d0MbQqY_4)
Tamara Horton
12/21/2024
Goran is patient and really gets to understand his clients wants/needs (no one shoe fits all). It really shows that it is more than a job to him. He takes personal pride and great responsibility in managing his portfolios. He takes great care to identify risks and point out the gaps, which is the hallmark of a great advisor. He tells you want you need to hear not what you want to hear. Very organized, good use of technology to interact and securely share information. He also goes step by step. Managing someone’s money/assets is absolute trust and transparency. Goran is both. I highly recommend.
[](https://www.google.com/maps/contrib/117873317029603282211/place/ChIJtW8Tko0JlVQR-2d0MbQqY_4)
Janell Richardson
1/19/2025
An incredible investor who really knows how to spot great opportunities. They have a deep understanding of the market and are genuinely committed to helping things grow. Excellent to work with and a solid recommendation for anyone looking for a dependable and sharp investment partner.
[](https://www.google.com/maps/contrib/104224912946888951959/place/ChIJtW8Tko0JlVQR-2d0MbQqY_4)
Julian Hidalgo
1/22/2025
Before choosing a new financial advisor I did a lot of research and even interviewed a few before selecting one. I ultimately selected Goran because I really liked his thorough and comprehensive approach to creating a financial plan. What sets Goran apart is that this is not just having a couple meetings and him monitoring through algorithms- he took the time to fully assess our financial and life circumstances and give us all the menu of options along the way. This approach not only allowed us to be active participants in our financial situation, but we learned SO much along the way that we’ll not just carry forward for ourselves but our children too! Goran is also extremely patient and really took the time to ensure we were understanding all the important concepts along the way. He’s a wealth of knowledge and comes with a lot of strategic expertise and tools that are helping us make the most of the money we have. I highly recommend Goran!!
[](https://www.google.com/maps/reviews/data=!4m8!14m7!1m6!2m5!1sCi9DQUlRQUNvZENodHljRjlvT2xKVVkzQXlTWEp5TjNRMFYxUlhUMTg0Wkc1d1IwRRAB!2m1!1s0x0:0xfe632ab4317467fb!3m1!1s2@1:CAIQACodChtycF9oOlJUY3AySXJyN3Q0V1RXT184ZG5wR0E%7C0cwwZGPV92x%7C?hl=en-US)
Danielle Droppers
10/18/2025
I was hesitant for a long time to begin working with a financial advisor, but after a couple initial meetings with Goran, it became clear that he was exactly what I was hoping to find. He really takes the time to clearly explain everything, is very thorough/comprehensive, and is excellent with follow up. Several meetings went beyond the scheduled time, but there was never any rushing, and Goran made sure to cover everything needed. If you’re looking for a family-based, fee-based, comprehensive financial partner, I can highly recommend Goran/Independent Investment Advisors. In fact, I have already recommended him to my close friends and family.
[](https://www.google.com/maps/reviews/data=!4m8!14m7!1m6!2m5!1sCi9DQUlRQUNvZENodHljRjlvT25GdGVtUm9TWEUzV1VGWGMxaFJVWFZNT1ZwV00xRRAB!2m1!1s0x0:0xfe632ab4317467fb!3m1!1s2@1:CAIQACodChtycF9oOnFtemRoSXE3WUFXc1hRUXVMOVpWM1E%7C0cVI8sc5U-v%7C?hl=en-US)
Young Park
7/23/2025
I’ve been working with Goran for a few months now and it has been an informative and enlightening experience. I was extremely intimidated by the task of figuring out finances, on my own and so late in life, but Goran is very supportive and responsive. My questions are answered quickly and thoroughly, and in a respectful manner. I can even say I’ve been excited to learn more and actively participate in financial decisions. I found Goran and Independent Investment Advisors by doing my homework (interviewed advisors, read reviews, attended workshops to learn the terminology, etc) and I feel my diligence paid off. I look forward to my continued work with Goran and IIA and attaining my financial goals and milestones.
[](https://www.google.com/maps/reviews/data=!4m8!14m7!1m6!2m5!1sCi9DQUlRQUNvZENodHljRjlvT2pkeFQyMWhlREZRY25CNlF6VmliM2hQVmw5eGJXYxAB!2m1!1s0x0:0xfe632ab4317467fb!3m1!1s2@1:CAIQACodChtycF9oOjdxT21heDFQcnB6QzVib3hPVl9xbWc%7C0cf6QcUs9Hm%7C?hl=en-US)
DeVonda Stoops
8/25/2025
Our experience with Goran and Independent Investment Advisors has been superb. From the initial consultation to our current steady state, Goran has helped us not only establish a robust plan but took the time to educate and inspire us. We’re grateful to have Goran supporting us on our financial journey and look forward to a brighter future as a result.
[](https://www.google.com/maps/reviews/data=!4m8!14m7!1m6!2m5!1sCi9DQUlRQUNvZENodHljRjlvT2w5blVUSjBlbUUzYzBwdGNHUkpRbXRsY1ZkNlNIYxAB!2m1!1s0x0:0xfe632ab4317467fb!3m1!1s2@1:CAIQACodChtycF9oOl9nUTJ0emE3c0ptcGRJQmtlcVd6SHc%7C0cTjBRJOzt0%7C?hl=en-US)
Tom Freeman
7/19/2025
Regulatory Disclosure Regarding Google Reviews: The above reviews are automatically imported from Google in real time and may include feedback from both clients and non-clients. Reviews reflect individual experiences and opinions and should not be construed as a guarantee of future performance or client satisfaction. Client Reviews: All client reviews represent individuals who have engaged our services. Clients are systemically invited to leave a Google review, typically after the completion of the initial financial planning process and/or portfolio construction. However, reviews may be posted at any time, including well after these milestones. Non-Client Reviews: While we aim to feature only client feedback, Google’s platform allows anyone to leave a review. As a result, some reviews may come from individuals who have not directly engaged our advisory services. No Compensation or Incentives: We do not offer compensation, discounts, or other incentives in exchange for reviews. All reviews are publicly available on Google, and we encourage prospective clients to conduct their own due diligence when evaluating financial service providers.
## Independent
With an emphasis on independence, the advisor is free to use the best possible strategies and assets for clients’ portfolios.
[Learn More](https://independentadvisorsnw.com/homepage/overview/)
## Passionate
The founder’s love for financial markets and passion for investing is the foundation of the company. What started as a family office is now a boutique wealth management practice for like-minded clients. Integrity and complete transparency are at the forefront of everything.
## Fiduciary
Clients’ interests come first. Period!
[Learn more ](https://independentadvisorsnw.com/homepage/overview/)
## Impartial and Transparent
We never earn commissions, fees, or kickbacks on your investments. You know what your costs, risks, and opportunities are and how well your portfolio is performing.
## Non-Custodial
Free to handpick the best and the most reliable broker-dealers and technology providers to safeguard clients’ assets.
[Learn More](https://independentadvisorsnw.com/homepage/overview/)
## Compatible
A relationship with your [wealth advisor](https://independentadvisorsnw.com/homepage/are-we-the-right-wealth-advisor-for-you/) is very personal. As such, it can only be effective if values, thinking, and approach to building wealth are genuinely compatible. Get in touch and let’s discuss if we can work together!
## How We Work
Our fee structure is transparent and straightforward, and we only invest either directly into underlying assets or low-cost Exchange Traded Funds. We don’t earn commissions, rebates, or incentives of any kind. There are no conflicts of interest.
We use the best-of-breed technology providers and are free to pick any asset globally, including derivatives, which we use to generate income or provide volatility protection.
We construct our portfolios from scratch for every client. We tailor the risk/reward profile to our client’s needs and personality. We review industry research and market internals every single day to keep a pulse on what is going on.
## How Others Work
Many Investment Advisors are also broker-dealers earning commissions, incentives, and rebates on your investments. Some are associated with large wire-houses and may earn sales commissions, especially on investments such as Mutual Funds.
Many wire-house Investment Advisors have a much smaller universe of accessible investments. The parent company picks and chooses which assets are available on their platform, and derivatives are generally not an option.
Many Investment Advisors use model portfolios built for them by their parent company or by their investment partners.
## Want to learn more about how we think; and how we work the capital markets?
Please check out our Market(s) Insights Blog. You will find monthly market insights videos and a variety of other relevant articles. There are several points of view represented, such as Investment Advisor, Active Trader, and Financial Planner.
[Market(s) Insights Blog](https://independentadvisorsnw.com/homepage/markets-insights/)
---
\*\*A hedging strategy is not appropriate for every investor and is not insurance against losses.
---
### [Tax Optimization Strategies for High Earners](https://independentadvisorsnw.com/homepage/education/tax-optimization-strategies-for-high-earners/)
**Published:** October 25, 2023
**Author:** Financial Planner
**Content:**
[< back to Investor Education Center](https://independentadvisorsnw.com/homepage/education/)
# Tax Optimization Strategies for High Earners
High earners often find themselves facing substantial tax bills each year, but there are strategies available to help optimize their tax situation and keep more of their hard-earned money. In this comprehensive guide, we will explore the various tax optimization strategies tailored for individuals with significant incomes.
## Understanding the Tax Landscape
High earners, typically those earning over $200,000 (or $400,000 for couples filing jointly), face a unique set of challenges when it comes to taxes. The tax system in the United States is progressive, meaning that as income increases, so does the tax rate. This means high earners can benefit significantly from tax optimization strategies.
## Maximizing Tax-Efficient Investments
One key strategy is tax-efficient investing. High earners can take advantage of tax-deferred retirement accounts, such as 401(k)s and IRAs, to reduce their taxable income. By contributing to these accounts, they not only [save for retirement](https://independentadvisorsnw.com/homepage/financial-calculators/retirement-savings-calculator/) but also lower their current-year tax liability. Additionally, they can employ tax-efficient investment strategies like [capital gains](https://independentadvisorsnw.com/how-roth-ira-conversions-can-escalate-capital-gains-taxes/) management and tax-loss harvesting.
## Strategic Use of Tax Credits and Deductions
High earners should be aware of tax credits and deductions that can help lower their tax bill. For example, the Child Tax Credit and the Earned Income Tax Credit can provide substantial tax relief for families. Itemized deductions, including those for charitable contributions and mortgage interest, can also play a significant role in reducing taxable income.
## Tax-Advantaged Savings and Retirement Planning
Advanced retirement planning is crucial for high earners. Strategies like the Backdoor Roth IRA and Health Savings Accounts (HSAs) can provide substantial tax benefits. These accounts allow individuals to [save for retirement and medical expenses while minimizing tax](https://independentadvisorsnw.com/the-6-hidden-tax-saving-opportunities-opened-up-by-new-tax-rules/) liability.
## Asset Allocation and Tax Efficiency
High earners should pay attention to asset allocation and tax efficiency. By holding tax-efficient investments in taxable accounts and tax-inefficient ones in tax-advantaged accounts, they can minimize their annual tax bills. Regular portfolio rebalancing helps maintain tax efficiency.
## Estate and Inheritance Tax Planning
Estate and inheritance taxes can be significant concerns for high-net-worth individuals. To minimize these tax burdens, strategies like trusts and gifting can be employed. Regularly reviewing and updating estate plans is essential to ensure they align with current tax laws.
## Staying Compliant and Working with Professionals
Compliance with tax laws is paramount for high earners. Tax professionals or [financial advisors who specialize in high-income tax planning](https://independentadvisorsnw.com/homepage/education/top-ten-financial-planning-tips-for-business-owners/) can provide invaluable guidance. Regular tax planning and monitoring help ensure continued tax optimization.
Tax optimization is a critical aspect of financial planning for high earners. By understanding the tax landscape, maximizing tax-efficient investments, strategically using tax credits and deductions, and engaging in advanced planning, high earners can substantially reduce their tax liability. Asset allocation, estate planning, compliance, and professional guidance are all essential components of a successful tax optimization strategy. Ultimately, taking proactive steps to optimize taxes can lead to greater financial security and a more prosperous future.
To further explore these strategies and tailor them to your unique [financial situation, consider consulting a financial advisor](https://independentadvisorsnw.com/independent-investment-advisors-receives-financial-advisory-of-the-year-oregon-award/) with expertise in high-income tax planning. Your financial advisor can help you navigate the complexities of tax optimization and create a customized plan that aligns with your goals.
Remember, while these strategies can be highly effective, tax laws and regulations change over time. It’s essential to stay informed and adapt your tax optimization strategy as needed to ensure ongoing financial success.
---
### [Free Financial Planning Resources and Decision Guides](https://independentadvisorsnw.com/resources/)
**Published:** April 17, 2026
**Author:** Financial Planner
**Content:**
# Free Financial Planning Resources and Decision Guides
We believe informed decisions lead to better financial outcomes. Over the years, we’ve developed practical planning tools, checklists, and flowcharts to help clients and families navigate complex financial decisions with clarity and confidence. We are pleased to make many of these resources available here at no cost—no email required.
If you find these materials helpful, sharing your experience through a [Google ](https://g.page/r/CXQmvSzlgJ7gEBM/review)review is always appreciated. Your feedback helps others discover trusted, practical tools and supports our continued effort to provide meaningful financial education.
## Retirement Planning
### Can I Contribute to a Roth IRA? (2026 Eligibility Flowchart)
This decision flowchart helps determine whether you are eligible to contribute to a Roth IRA based on income, filing status, and earned income requirements. It walks through the key thresholds that govern full, partial, or ineligible contributions, including the 2026 contribution limits of up to **$7,500 (or $8,600 if age 50 or older)** and the income phaseout ranges that apply to single and married taxpayers. This guide is especially useful for year-end tax planning and retirement savings decisions.
[ Can I Contribute to a Roth IRA? (2026 Eligibility Flowchart) (8212 downloads )](https://independentadvisorsnw.com/download/3049/?tmstv=1788998122)
### Can I Make a Backdoor Roth IRA Contribution? (2026 Decision Guide)
This flowchart helps determine whether a Backdoor Roth IRA contribution is appropriate based on income, existing IRA balances, and employer retirement plan options. It outlines the key considerations that often impact the tax outcome of a conversion, including the aggregation and pro rata rules that apply when pre-tax IRA assets are present. The guide also walks through the basic steps involved in completing a Backdoor Roth contribution—from making a non-deductible IRA contribution to converting the funds into a Roth IRA—helping individuals avoid common planning mistakes.
[ Can I Make a Backdoor Roth IRA Contribution? (2026 Decision Guide) (8290 downloads )](https://independentadvisorsnw.com/download/3053/?tmstv=1788998122)
## Tax Planning
### 2026 Important Financial Planning Numbers
This quick-reference guide summarizes many of the key tax thresholds, retirement plan limits, and planning figures that frequently change each year. It is designed to help individuals and families stay informed about important numbers that can influence contribution decisions, tax planning strategies, and retirement planning opportunities. The guide includes updated limits for retirement accounts, income tax brackets, Social Security thresholds, Medicare premiums, and other commonly referenced planning figures for 2026.
[ Important Numbers 2026 (8090 downloads )](https://independentadvisorsnw.com/download/3042/?tmstv=1788998122)
### Important Financial Planning Milestones by Age (2026 Guide)
This guide outlines key financial planning milestones that occur at different ages throughout life, helping individuals anticipate important eligibility rules and planning opportunities before they arise. It highlights critical ages related to retirement contributions, Social Security benefits, Medicare enrollment, Required Minimum Distributions (RMDs), and other planning triggers that often drive financial and tax decisions. Having visibility into these milestones can help families avoid missed deadlines and make more informed long-term planning decisions.
[ Financial Planning Milestones by Age (2026 Guide) (8211 downloads )](https://independentadvisorsnw.com/download/3045/?tmstv=1788998122)
### Tax Withholding Estimator
Use this tool to estimate the correct amount of tax your employer (W-2) or pension provider should withhold each year.
You can download a completed [Form W-4](https://www.irs.gov/forms-pubs/about-form-w-4) or [Form W-4P](https://www.irs.gov/forms-pubs/about-form-w-4-p) and give it to your employer or pension provider. Depending on the results, this could help you avoid having too little tax withheld, making it less likely you’ll owe a penalty when you file your tax return. Or, it may help you avoid having too much tax withheld, giving you a bigger paycheck now but a smaller refund later.
[IRS Tax Withholding Estimator](https://www.irs.gov/individuals/tax-withholding-estimator)
## Investment Planning
–
## Equity Compensation & Concentrated Stock
–
## Estate & Legacy Planning
–
## Life Events & Major Financial Decisions
–
## Small Business & Self-Employed Planning
–
## Financial Organization & Planning Tools
---
### [IRA and HSA Contribution Strategies: A Guide to Tax-Efficient Retirement and Healthcare Savings](https://independentadvisorsnw.com/homepage/education/ira-and-hsa-contribution-strategies-a-guide-to-tax-efficient-retirement-and-healthcare-savings/)
**Published:** April 10, 2026
**Author:** Financial Planner
**Content:**
[< back to Investor Education Center](https://independentadvisorsnw.com/homepage/education/)
# IRA and HSA Contribution Strategies: A Guide to Tax-Efficient Retirement and Healthcare Savings
Saving for retirement and managing healthcare costs are two of the most important financial priorities individuals face throughout their working years. Two accounts frequently used to address both goals are **Individual Retirement Accounts (IRAs)** and **Health Savings Accounts (HSAs)**.
These accounts offer meaningful tax advantages, but the rules governing contributions, eligibility, and long-term planning can be complex—especially for high-income professionals, business owners, and individuals with multiple retirement plans.
At **Independent Investment Advisors**, IRA and HSA decisions are rarely made in isolation. They are typically part of a broader strategy that coordinates retirement savings, tax planning, investment management, and long-term financial goals.
This guide explains how these accounts work, how contribution decisions affect taxes and retirement outcomes, and how to use them effectively as part of a comprehensive financial plan.
---
# Understanding the Role of IRAs and HSAs in a Long-Term Financial Plan
Both IRAs and HSAs provide tax advantages, but they serve different purposes within a financial strategy.
**IRAs are primarily retirement savings vehicles.**
They help individuals accumulate assets for future income while providing tax benefits during the contribution or withdrawal phase.
**HSAs are designed to fund healthcare expenses.**
However, when used strategically, they can also function as an additional retirement savings account.
In practice, these accounts often complement employer-sponsored retirement plans such as 401(k)s, especially for individuals seeking to:
- Reduce taxable income
- Diversify future tax exposure
- Increase long-term savings capacity
- Manage rising healthcare costs in retirement
- Improve overall tax efficiency
For many households, particularly those with higher earnings, the value of these accounts comes not from the contribution itself—but from **how the account fits into a coordinated tax strategy over time.**
---
# IRA Contribution Basics: What Every Investor Should Know
An Individual Retirement Account allows individuals to save for retirement with potential tax advantages.
There are two primary types of IRAs:
**Traditional IRA**
Contributions may be tax-deductible, and investments grow tax-deferred until withdrawal.
**Roth IRA**
Contributions are made with after-tax dollars, but qualified withdrawals in retirement are tax-free.
Contribution limits are set annually by the IRS and apply across all IRA accounts combined. Eligibility rules may depend on income, participation in employer-sponsored retirement plans, and filing status.
Key concepts that influence IRA planning include:
- Earned income requirements
- Contribution limits
- Income-based phaseouts
- Deduction eligibility
- Tax treatment of withdrawals
- Required Minimum Distribution (RMD) rules
- Coordination with employer retirement plans
Understanding these factors is essential to avoid penalties and maximize the long-term value of retirement savings.
---
# Traditional vs. Roth IRA: Choosing the Right Strategy
Selecting between a Traditional and Roth IRA is not simply a tax decision—it is a **lifetime tax planning decision.**
The choice often depends on:
- Current income level
- Expected future tax rates
- Retirement timeline
- Existing retirement assets
- Eligibility for deductions
- Long-term withdrawal strategy
### Situations Where a Traditional IRA May Be Beneficial
A Traditional IRA is often considered when:
- Current tax rates are relatively high
- A tax deduction is available
- Retirement income is expected to be lower
- The goal is to reduce taxable income in the current year
### Situations Where a Roth IRA May Be Beneficial
A Roth IRA may be preferred when:
- Current tax rates are relatively low
- Long-term tax-free income is a priority
- Retirement income is expected to be higher
- Estate planning flexibility is desired
- Tax diversification is important
In many cases, the most effective strategy is not choosing one account over the other, but maintaining **both types of retirement assets** to create flexibility in retirement.
---
# Roth IRA Eligibility and High-Income Planning Considerations
One of the most common planning challenges involves income limitations for Roth IRA contributions.
As income increases, the amount an individual is allowed to contribute to a Roth IRA gradually decreases and may eventually be eliminated.
This is particularly relevant for:
- Technology professionals
- Executives
- Business owners
- Dual-income households
When income exceeds eligibility thresholds, individuals may still be able to build Roth assets through alternative strategies such as:
- Roth conversions
- Backdoor Roth contributions
- Employer plan Roth options
- Tax diversification planning
These strategies require careful coordination to avoid unintended tax consequences.
---
# Health Savings Accounts: A Unique Tax-Advantaged Account
Health Savings Accounts are available to individuals enrolled in qualified High Deductible Health Plans (HDHPs).
HSAs offer a rare combination of tax benefits that make them one of the most efficient savings vehicles available.
They provide:
**Tax-deductible contributions**
**Tax-free investment growth**
**Tax-free withdrawals for qualified medical expenses**
This structure is often referred to as a **triple tax advantage.**
Because healthcare expenses tend to increase with age, HSAs can play an important role in retirement planning—especially for individuals seeking to manage long-term medical costs.
---
# Using an HSA as a Long-Term Retirement Strategy
While HSAs are commonly used to pay current medical expenses, many investors choose to treat them as long-term investment accounts.
This approach may involve:
- Paying medical expenses out-of-pocket
- Allowing HSA funds to remain invested
- Using the account to cover healthcare costs in retirement
After age 65, HSA withdrawals for non-medical expenses are permitted, though they may be subject to income tax.
Because of this flexibility, HSAs are often viewed as:
- A supplemental retirement account
- A tax-efficient savings vehicle
- A hedge against rising healthcare costs
- A planning tool for long-term financial security
---
# Common Mistakes to Avoid with IRA and HSA Contributions
Even experienced investors can encounter issues when managing tax-advantaged accounts.
Some of the most common mistakes include:
### Exceeding Contribution Limits
Contributing more than the IRS allows can result in ongoing penalties if the error is not corrected.
### Contributing Without Meeting Eligibility Requirements
This can occur when:
- Income exceeds Roth IRA limits
- Health plan coverage does not qualify for HSA contributions
- Employer contributions are overlooked
### Ignoring Coordination with Other Retirement Plans
Individuals with multiple retirement accounts may unintentionally create inefficiencies by:
- Overlapping tax strategies
- Missing deduction opportunities
- Failing to diversify tax exposure
### Treating Contributions as One-Time Decisions
Effective planning typically requires ongoing coordination rather than annual decision-making.
---
# Why IRA and HSA Planning Should Be Ongoing, Not Seasonal
Many investors think about retirement contributions only during tax season. In reality, the most effective strategies are developed throughout the year.
Ongoing planning allows individuals to:
- Adjust contributions as income changes
- Respond to tax law updates
- Manage investment risk
- Coordinate retirement and healthcare savings
- Optimize long-term financial outcomes
For households with complex financial situations—such as variable income, equity compensation, or multiple retirement plans—this coordination becomes even more important.
---
# How IRA and HSA Contributions Fit into a Comprehensive Financial Plan
In practice, contribution decisions are rarely isolated transactions.
They are often connected to broader planning considerations such as:
- Retirement income planning
- Tax optimization strategies
- Investment allocation decisions
- Estate planning goals
- Risk management planning
- Healthcare cost planning
For example:
A business owner may coordinate IRA contributions with profit-sharing plan contributions.
A technology professional may align HSA funding with equity compensation planning.
A retiree may use Roth assets to manage taxable income during retirement.
These decisions are most effective when evaluated within the context of an integrated financial plan.
---
# When to Seek Professional Guidance
While many contribution decisions appear straightforward, the underlying tax and planning implications can be complex.
Professional guidance may be particularly valuable for individuals who:
- Have multiple retirement accounts
- Earn higher incomes
- Receive stock-based compensation
- Own a business
- Are approaching retirement
- Are planning major financial transitions
In these situations, small planning decisions can have meaningful long-term tax and retirement consequences.
---
# The Bottom Line
IRAs and HSAs are two of the most valuable tools available for building retirement savings and managing healthcare costs.
Used effectively, they can help individuals:
- Reduce taxes
- Increase long-term savings
- Improve retirement flexibility
- Manage future healthcare expenses
- Strengthen overall financial security
However, the greatest value of these accounts comes not from the contribution itself—but from how they are integrated into a comprehensive financial strategy.
For individuals seeking to make informed decisions about retirement savings, tax planning, and long-term financial goals, the team at **Independent Investment Advisors** can help evaluate how IRA and HSA strategies fit into a broader financial plan.
---
### [Investor Education Center: Empowering Your Path to Financial Success](https://independentadvisorsnw.com/homepage/education/)
**Published:** July 13, 2020
**Author:** Investment Advisor
**Content:**
### [Financial Calculators](https://independentadvisorsnw.com/homepage/financial-calculators/)
[](https://independentadvisorsnw.com/homepage/financial-calculators/)A critical component of any financial plan and ongoing wealth management process is modeling through various what-if scenarios. We use these financial calculators to do just that. Creating a best-case and a worst-case makes up an [investment planning](https://independentadvisorsnw.com/advisor-qa-how-do-you-help-your-clients-adjust-their-retirement-and-investment-strategies-in-response-to-evolving-tax-laws/) framework we use to manage our client’s wealth over the years to come.
### [Tax Optimization Strategies for High Earners](https://independentadvisorsnw.com/homepage/education/tax-optimization-strategies-for-high-earners/)
[](https://independentadvisorsnw.com/homepage/education/tax-optimization-strategies-for-high-earners/)High earners often find themselves facing substantial tax bills each year, but there are [strategies available to help optimize their tax](https://independentadvisorsnw.com/homepage/education/tax-optimization-strategies-for-high-earners/) situation and keep more of their hard-earned money. In this comprehensive guide, we will explore the various [tax optimization](https://independentadvisorsnw.com/advisor-qa-how-to-guide-to-tax-optimized-investing-tax-deductions-and-incentives/) strategies tailored for individuals with significant incomes.
### [Are You Facing Early Retirement Decision?](https://independentadvisorsnw.com/homepage/education/facing-early-retirement-decision/)
[](https://independentadvisorsnw.com/homepage/education/facing-early-retirement-decision/)
You weren’t planning on making retirement decisions so soon. You thought you had years to go before you entered the critical transition period, where the choices you make now set the stage for the next 30 years of your life.
### [Guide to recessions: 9 key things you need to know!](https://independentadvisorsnw.com/homepage/education/guide-to-recessions/)
[](https://independentadvisorsnw.com/homepage/education/guide-to-recessions/)How bad will the next recession be? That’s one of the questions we hear most often, especially now as the Federal Reserve aggressively hikes interest rates to rein in inflation at 40-year highs.
### [Cryptocurrency Explained](https://independentadvisorsnw.com/homepage/education/cryptocurrency-explained/)
[](https://independentadvisorsnw.com/homepage/education/cryptocurrency-explained/)
Cryptocurrency isn’t the black sheep it once was. It’s hit the mainstream, and it’s grabbing up more headlines and investors than ever before. These days, about 1 in 7 Americans own some type of cryptocurrency. And a little more than half of them bought it for the first time in 2020
### [What should I do with my old 401(k) or employer plan?](https://independentadvisorsnw.com/homepage/education/what-should-i-do-with-my-old-401k-or-employer-plan/)
[](https://independentadvisorsnw.com/homepage/education/what-should-i-do-with-my-old-401k-or-employer-plan/)When you leave an employer (whether you’re changing jobs or retiring), your retirement plan doesn’t automatically move for you. You must make a critical decision (or risk having that decision made for you in a way that’s better for the company or costs you money).
### [RSUs, ISOs, NSOs & ESPPs: How to Minimize Taxes & Maximize Gains](https://independentadvisorsnw.com/homepage/education/rsus-isos-nsos-espps-how-to-minimize-taxes-maximize-gains/)
[](https://independentadvisorsnw.com/homepage/education/rsus-isos-nsos-espps-how-to-minimize-taxes-maximize-gains/)
Discover effective tax strategies for managing RSUs, ISOs, NSOs, and ESPPs. Tailored for technology professionals in Hillsboro, Oregon, this guide helps you optimize your equity compensation.
### [How Far Could a Cool $1 Million Go in Retirement?](https://independentadvisorsnw.com/homepage/education/how-far-could-1-million-go-in-retirement/)
[](https://independentadvisorsnw.com/homepage/education/how-far-could-1-million-go-in-retirement/)
A million dollars used to be the ultimate target for retirement portfolios. Retiring as a millionaire brought status and confidence that you could live comfortably during your golden years.
### [“Hidden” 401(k) Strategies Used by Some Investors](https://independentadvisorsnw.com/homepage/education/hidden-401k-strategies-used-by-some-investors/)
[](https://independentadvisorsnw.com/homepage/education/hidden-401k-strategies-used-by-some-investors/)
Most high earners are already leveraging the power of their employer-sponsored 401(k) to [save for retirement](https://independentadvisorsnw.com/what-advice-would-you-give-to-someone-seeking-to-minimize-taxes-while-maximizing-retirement-and-investment-savings/). They [understand the well-publicized advantages: tax](https://independentadvisorsnw.com/advisor-qa-how-to-guide-to-tax-optimized-investing-understand-tax-advantaged-retirement-accounts/) deferral, the “free money” provided by the employer match, and the “catch-up” provision after age 50. However, some investors understand that there is so much more “hidden” beneath the surface of their 401(k) than just the visible benefits.
### [Portfolio of $500,000-$2 million? Discover the “Perfect Cocktail” Strategy Used by Wealthy Investors](https://independentadvisorsnw.com/homepage/education/portfolio-of-500000-2-million/)
[](https://independentadvisorsnw.com/homepage/education/portfolio-of-500000-2-million/)If you’re not sure where to find the right techniques for your bespoke portfolio, you’re in the right place. This pivotal guide is your ticket to the financial strategy that serves your needs now and in the future, by providing you with the same tools that ultra-high-net-worth (UHNW) investors know and use.
### [Boutique vs. Big-Box Wealth Management: Which is Right for You?](https://independentadvisorsnw.com/homepage/education/boutique-vs-big-box-wealth-management-which-is-right-for-you/)
[](https://independentadvisorsnw.com/homepage/education/boutique-vs-big-box-wealth-management-which-is-right-for-you/)If you’re a mid-career tech professional, your financial life is likely more complex than most. You may have equity compensation in multiple forms (RSUs, ISOs, ESPPs, NSOs), a growing investment portfolio, rising income, and a host of competing goals
### [The 3 Pillars of Successful Retirement Plans](https://independentadvisorsnw.com/homepage/education/the-3-pillars-of-successful-retirement-plans/)
[](https://independentadvisorsnw.com/homepage/education/the-3-pillars-of-successful-retirement-plans/)
If you’re within 5 years of retirement, you’re in a critical period – if you take action now, you may still be able to make up for past mistakes. The decisions you make now will define your retirement lifestyle and your ability to retire successfully.
### [How to Choose a Financial Advisor](https://independentadvisorsnw.com/homepage/education/how-to-choose-a-financial-advisor/)
[](https://independentadvisorsnw.com/homepage/education/how-to-choose-a-financial-advisor/)Recent Vanguard study found that, on average, a $500K investment would grow to over $3.4 million under the care of an advisor over 25 years, whereas the expected value from self-management would be $1.69 million, or 50% less. In other words, an advisor-managed portfolio would average 8% annualized growth over a 25-year period, compared to 5% from a self-managed portfolio.
### [Sudden Wealth Inheritance?](https://independentadvisorsnw.com/homepage/education/sudden-wealth-inheritance/)
[](https://independentadvisorsnw.com/homepage/education/sudden-wealth-inheritance/)
Coming into money? You have a lot of new decisions to make. Without a strategy or careful planning for your sudden wealth, you could open yourself up to many risks – even losing your sudden wealth completely. Learn more about these easily avoided pitfalls in this guide.
### [IRA and HSA Contribution Strategies: A Guide to Tax-Efficient Retirement and Healthcare Savings](https://independentadvisorsnw.com/homepage/education/ira-and-hsa-contribution-strategies-a-guide-to-tax-efficient-retirement-and-healthcare-savings/)
[](https://independentadvisorsnw.com/homepage/education/ira-and-hsa-contribution-strategies-a-guide-to-tax-efficient-retirement-and-healthcare-savings/)
Saving for retirement and managing healthcare costs are two of the most important financial priorities individuals face throughout their working years. Two accounts frequently used to address both goals are Individual Retirement Accounts (IRAs) and Health Savings Accounts (HSAs).
**[1](https://independentadvisorsnw.com/homepage/education/) [2](https://independentadvisorsnw.com/homepage/education_2/)**
---
### [Bethany & Cedar Mill Living Sponsor Spotlight](https://independentadvisorsnw.com/about/bethany-cedar-mill-living-sponsor-spotlight/)
**Published:** September 17, 2020
**Author:** Investment Advisor
**Content:**
# Bethany & Cedar Mill Living Sponsor Spotlight
Goran Ognjenovic is the founder and principal investment advisor of Independent Investment Advisors. He and his wife Danijela have lived in Oregon since 1998 and have been Cedar Mill residents since 2007. Danijela is also Goran’s business partner at Independent Investment Advisors, and comes from a background in Operations Management for a top global sports company. She is a business manager with 10+ years of experience. This business team duo are both Portland State University graduates and have two children; a boy and girl who both attend Findley Elementary School. Goran shares, “We are big fans of the NW lifestyle as we like to do a lot of outdoor activities. We spend a lot of time in central Oregon as we enjoy skiing, boating, hiking, biking, and more recently, golf!” Goran is also a soccer coach at Oak Hills Soccer Club.
Goran’s involvement with investing, active trading, and capital markets goes back to the dot- com era’s early days. Goran says, “Those were the first and exciting beginnings of online brokerages and the Regulation NMS (National Market System). I took on the challenge of learning financial markets and the responsibility of managing personal investments. I did this originally out of interest, passion, and intellectual intrigue. But also, because I wanted the flexibility to pick the most appropriate investments regardless of who the asset manager was. Those early days were full of trials, tribulations, steep learning curves, and lots of fun!”
For Independent Investment Advisors, what started as a personal investment journey evolved into a family investment office in the years that followed. Finally, in 2017, it grew into a professional practice. Today, Goran continues to view investing and working in the capital markets as a way to share his experience to financially secure and establish people he cares about. He loves that what started out as a personal passion has grown into an opportunity to benefit many and allows him to do what he enjoys in the process! “Financial markets are the first thing I look at in the morning, and the last thing I look at before going to bed. I invest, actively trade, develop, run market scanning tools, and love every minute of it – I truly can’t get enough!”
Goran also chose to become an independent fiduciary advisor, as he believes in complete transparency with no interest conflicts. He enjoys the challenge and freedom of finding the best investment options for a client’s unique situation without any pressure for recommending a specific product. As an independent advisor, he also takes advantage of many best-of-breed industry technology solutions, and loves the precision this offers each unique financial plan he works with.
Within the firm’s context, Goran works with a select number of clients, and manages their diverse set of investment portfolios. “Many of my clients are small-business owners. Working together, we have developed a wide range of financial investment solutions specifically focused on a small-business owner’s needs and expectations. I work with our business-owner clients on retirement planning, money management for their business, tax-efficient investing, estate investments, college savings for their kids, inheritance, trusts, and everything in between!” The investment needs of a small-business owner are slightly different from an average corporate employee, so Goran is excited to specialize in this area of financial literacy.
Independent Investment Advisors hopes that small-business owners in our community will consider this time-tested tip when it comes to planning for retirement. “Many small-business owners underestimate the importance of a *standalone individual retirement plan* separate from their business. The financial security offered by a separate individual [retirement plan](https://iiaproduction.wpengine.com/homepage/investor-education-center/6-small-business-retirement-plans/) and investment account come with the additional perks of immediate tax deferral, a reduction in annual tax liability, and also protecting that asset from business liability. Whatever your long or short-term business plans may be, get a boost in the right direction with IRA or 401K options that truly harness your strengths. “Whether you need more flexibility, structure or a little of both, this critical step can ensure that you successfully reach *true* retirement security.”
Independent Investment Advisors
Goran Ognjenovic
Phone: 971.350.8068
Email:
www.independentadvisorsnw.com
---
### [General Questions About Independent Investment Advisors Services](https://independentadvisorsnw.com/services/services-faq/)
**Published:** December 5, 2025
**Author:** Investment Advisor
**Content:**
Managing wealth, planning for retirement, navigating taxes, and understanding equity compensation can feel overwhelming—especially for busy technology professionals, executives, and small-business owners. To help bring clarity, we’ve compiled answers to the most common questions we receive as a fee-only fiduciary Registered Investment Advisor. These FAQs cover our planning process, investment approach, tax strategy, equity compensation guidance, virtual advisory services, and how we serve clients across Hillsboro, Beaverton, Portland, and nationwide. If you have questions not addressed here, we’re always available to discuss your situation in more detail.
## **Q1: Are you a fiduciary financial advisor?**
**Yes. Independent Investment Advisors is a fee-only fiduciary Registered Investment Advisor, meaning we are legally required to act in your best interest at all times. We do not sell products or earn commissions.**
---
## **Q2: Do you work with clients virtually or outside Oregon?**
**Yes. We serve clients nationwide through secure virtual meetings, online planning tools, and digital portfolio management. We work with technology professionals, executives, and families across the U.S.**
---
## **Q3: What types of clients do you specialize in?**
**We primarily serve technology professionals, small-business owners, executives, and high-net-worth families who need integrated financial planning, investment management, tax strategy, and equity compensation guidance.**
---
## **Q4: Do you help with RSUs, ESPPs, and stock options?**
**Yes. We specialize in equity compensation planning, including RSUs, ESPPs, ISOs, NSOs, AMT analysis, and managing concentrated stock positions for tech-industry clients.**
---
## **Q5: What services do you provide?**
**We offer comprehensive financial planning, wealth management, tax strategy, equity compensation planning, retirement planning, RMD planning, Roth conversions, inherited IRA guidance, and small-business financial planning.**
---
## **Q6: Are you fee-only or commission-based?**
**We are fee-only. We do not receive commissions or accept compensation from product sales. Our only compensation comes directly from our clients.**
---
## **Q7: Do you provide tax planning?**
**Yes. We provide integrated tax planning, including strategies for equity compensation, capital gains, Roth conversions, retirement distributions, and multi-year tax optimization.**
---
## **Q8: Do you help with retirement planning?**
**Yes. We build retirement income strategies, tax-efficient withdrawal plans, Social Security analysis, RMD planning, and long-term projections tailored to your goals.**
---
## **Q9: How do you manage investments?**
**We use a data-driven approach to portfolio construction, risk management, and tax-efficient investing. Portfolios are tailored to your goals, risk tolerance, and overall financial plan.**
---
## **Q10: Do you work with small-business owners?**
**Yes. We assist with retirement plans, compensation structures, tax planning, entity evaluations, and long-term business and personal financial strategies.**
---
## **Q11: What does the onboarding process look like?**
**We start with a complimentary consultation, followed by data gathering, financial analysis, plan development, and portfolio alignment. Everything can be done virtually or in person.**
---
## **Q12: Are you available to clients in Portland and Beaverton?**
**Yes. We serve clients throughout Portland, Beaverton, Cedar Mill, Bethany, Hillsboro, and the surrounding metro area, as well as clients nationwide through virtual meetings.**
---
## **Q13: Do you help with required minimum distributions (RMDs)?**
**Yes. We provide RMD planning, IRA distribution strategies, tax-efficient withdrawal coordination, and annual monitoring.**
---
## **Q14: Can you help with inherited IRAs?**
**Yes. We guide clients through SECURE Act rules, 10-year distribution timelines, tax planning, and beneficiary strategy for inherited IRAs.**
---
## **Q15: Do you offer one-time financial plans or ongoing advisory?**
**We offer both. Many clients engage us for ongoing planning and wealth management, while others begin with a standalone financial plan and choose ongoing service later.**
---
## **Q16: Are meetings required in person?**
**No. We offer fully virtual meetings and flexible scheduling designed for busy professionals. In-person meetings are optional at our Hillsboro or Portland/Beaverton office.**
---
## **Q17: Do you help optimize employee benefits like 401(k)s and HSAs?**
**Yes. We help evaluate and optimize employer benefits such as 401(k) plans, HSAs, FSAs, deferred compensation, and equity compensation programs.**
---
## **Q18: What makes your firm different from larger financial institutions?**
**We are a boutique, independent, fee-only fiduciary firm focused on a limited number of families. This allows for deeper planning, integrated tax strategy, and highly personalized investment management.**
---
## **Q19: Is there a minimum investment?**
**We do not publish strict asset minimums. Most clients come to us with complex planning needs, equity compensation, or multi-layered tax considerations.**
---
### [Contact Us](https://independentadvisorsnw.com/contact-us/)
**Published:** September 18, 2019
**Author:** Investment Advisor
**Content:**

## **CONTACT US**
**Phone/SMS: 971.350.8068**
[**info@independentadvisorsnw.com**](mailto:info@independentadvisorsnw.com)
[Hillsboro Office: 9620 NE Tanasbourne Dr, Suite 300, Hillsboro, OR 97124](https://independentadvisorsnw.com/locations/hillsboro-oregon/)
[Portland Office: 13827 NW Thompson Rd, Portland, OR 97229](https://independentadvisorsnw.com/locations/portland-beaverton-oregon/)
### **SCHEDULE A MEETING**
[SCHEDULE A 30 MINUTE INTRODUCTORY CALL](https://outlook.office365.com/book/IndependentInvestmentAdvisors@mlignw.com/)
[SCHEDULE A 60 MINUTE INTRODUCTORY CALL](https://outlook.office365.com/book/IndependentInvestmentAdvisors60min@mlignw.com/)
[Online Financial Advisor | Virtual Fiduciary Wealth Planning](https://independentadvisorsnw.com/locations/virtual-financial-advisor-online-wealth-management-for-clients-across-the-u-s/)
### **MESSAGE US**
[message US](https://independentadvisorsnw.com/contact-us/contact-form/)
[REQUEST A PORTFOLIO REVIEW](https://independentadvisorsnw.com/contact-us/portfolio-review-request/)
[NEWSLETTER SIGNUP ](https://independentadvisorsnw.com/contact-us/markets-insights-signup/)
## Interactive Brokers
### [Account Management Portal](https://ndcdyn.interactivebrokers.com/sso/Login?RL=1)
Start here to fund your account, transfer funds or positions, set up direct deposit, configure Bill Pay and view your transaction history.
## Charles Schwab
### [Account Management Portal](https://www.schwab.com/client-home)
Start here to fund your account, transfer funds or positions, set up direct deposit, configure Bill Pay and view your transaction history.
Get complimentary access to our Wealth Management platform so you can view and track your net worth, income, and spending.
[**GET STARTED >** **START YOUR FINANCIAL PLAN**](https://app.rightcapital.com/account/sign-up?referral=6hYSryvU83RoJbpuPuVq2g&type=client).
---
### [Virtual Financial Advisor & Online Wealth Management for Clients Across the U.S.](https://independentadvisorsnw.com/locations/virtual-financial-advisor-online-wealth-management-for-clients-across-the-u-s/)
**Published:** December 5, 2025
**Author:** Investment Advisor
**Content:**
# Nationwide Fee-Only Fiduciary Financial Planning & Wealth Management
Independent Investment Advisors provides comprehensive financial planning, wealth management, investment strategy, and tax planning services to clients **anywhere in the United States** through a fully virtual advisory experience. As a fee-only fiduciary Registered Investment Advisor, we deliver the same personalized, high-touch guidance online as we do for our local Oregon clients—without commissions, product sales, or hidden incentives.
We work with technology professionals, small-business owners, executives, and high-net-worth families across the country who want a disciplined, integrated approach to long-term financial and tax planning.
# **Who We Serve Nationwide**
Our virtual practice supports clients across all 50 states, including:
- Technology professionals with RSUs, ESPPs, stock options, or mobility-related tax issues
- Executives managing deferred compensation, concentrated equity, or multi-state income
- High-earning families seeking integrated financial and tax planning
- Small-business owners evaluating retirement plans, compensation structures, and planning needs
- Individuals seeking long-term wealth planning, retirement readiness, and investment oversight
We provide the same level of service remotely that clients receive in-person at our Oregon offices.
# **Comprehensive Online Financial Planning & Wealth Management**
We help clients achieve their goals with customized, comprehensive strategies for financial, investment, equity compensation, risk, and tax planning. All services are available virtually:
### **Financial Planning & Retirement Planning**
Online planning sessions, digital onboarding, secure document sharing, and interactive retirement modeling.
### **Wealth Management & Investment Management**
Portfolio construction, monitoring, risk management, rebalancing, and ongoing investment oversight—all accessible through modern online reporting tools.
### **Tax Strategy & Annual Tax Planning**
Proactive guidance on RSUs, ESPPs, stock options, AMT exposure, capital gains, Roth conversions, and multi-year planning strategies.
### **Equity Compensation Guidance for Tech Professionals**
Nationwide expertise in managing stock compensation, evaluating exercise strategies, and planning liquidity events.
### **RMD Planning, Roth Conversions & IRA Strategy**
Virtual support for retirement income planning, tax-efficient conversions, and regulatory compliance.
### **Inheritance & Estate Planning Coordination**
We work with your CPA, estate attorney, and other professionals—no matter where they are located.
### **Small-Business & Entrepreneur Planning**
Virtual support for retirement plan design, entity structure reviews, tax optimization, and business transition planning.
# **Our Virtual Process: Designed for Busy, High-Earning Professionals**
We offer a streamlined, technology-forward experience using secure, modern tools:
- Video meetings via Zoom or your preferred platform
- Secure digital document uploads
- Online performance reporting
- E-signature for forms and agreements
- Real-time screen-share planning sessions
- Cloud-based financial plan access
Clients across the country choose our virtual model for convenience, transparency, and the ability to work with a fiduciary advisor who specializes in advanced tax and equity-compensation planning.
# **Why Work With Independent Investment Advisors — Virtually**
Clients engage us because we offer:
- Fee-only, fiduciary advice—no commissions or sales incentives
- Expertise in tax strategy and equity compensation
- A boutique, multi-family-office–style experience
- Deep planning for high-net-worth and tech-industry clients
- A structured annual service calendar and proactive communications
- Personalized, data-driven investment oversight
Our remote service model provides the same high level of customization and rigor regardless of where you live.
# **Serving Clients Across All 50 States**
We currently work virtually with clients nationwide, including:
- West Coast: California, Washington, Colorado
- Southwest: Arizona, Nevada, Texas
- East Coast: New York, Massachusetts, Virginia, North Carolina
- Midwest: Illinois, Ohio, Minnesota
- Remote workers, hybrid employees, and multi-state taxpayers
Our team is equipped to support planning needs involving multi-state tax considerations and employer-specific equity programs common across major tech hubs.
# **Schedule a Virtual Consultation**
If you’re looking for a **virtual financial advisor** who provides integrated financial planning, tax strategy, investment management, and equity-compensation expertise, we’re ready to help—wherever you are.
**[Schedule a complimentary online consultation](https://outlook.office365.com/owa/calendar/IndependentInvestmentAdvisors@mlignw.com/bookings/)**
---
### [Hillsboro Financial Advisor & Wealth Management | Independent Investment Advisors](https://independentadvisorsnw.com/locations/hillsboro-oregon/)
**Published:** December 5, 2025
**Author:** Investment Advisor
**Content:**
# Fiduciary, Fee-Only Financial Planning and Wealth Management in Hillsboro, Oregon
Independent Investment Advisors is a boutique, fee-only fiduciary Registered Investment Advisor serving individuals and families throughout **Hillsboro, Orenco Station, AmberGlen, Tanasbourne, Reedville, and the Silicon Forest technology corridor**. We provide comprehensive financial planning, wealth management, investment strategy, and tax planning for technology professionals, small-business owners, and high-net-worth families.
# **Serving the Heart of Hillsboro’s Technology Corridor**
Hillsboro is home to many of Oregon’s largest employers, including **Intel, Nike, Amazon, Salesforce, Genentech, Tektronix, and dozens of fast-growing startups**. We specialize in guiding clients through the complex financial decisions that come with careers in the tech and engineering fields.
Our expertise includes:
- RSUs, ESPPs, and stock option planning
- AMT analysis for ISO exercises
- Managing concentrated stock positions
- Tax-efficient investment strategies
- Multi-state and remote work tax considerations
We help busy professionals in Orenco, AmberGlen, Tanasbourne, and South Hillsboro simplify complexity and build long-term financial stability.
# **Comprehensive Wealth Management & Financial Planning in Hillsboro**
We help clients achieve their goals with customized, comprehensive strategies for financial, investment, equity compensation, risk, and tax planning. Our services include:
### **Financial Planning & Retirement Planning**
Goal-based planning, retirement income strategies, tax-efficient withdrawal planning, and Social Security optimization.
### **Wealth Management & Investment Management**
Data-driven portfolio design, risk management, rebalancing, and long-term investment oversight.
### **Equity Compensation & Tax Strategy**
Planning for RSUs, ESPPs, stock options, AMT, and tax-efficient liquidity events.
### **Inheritance, Estate & Legacy Planning**
Coordinate with attorneys, evaluate beneficiary designations, and plan for long-term family wealth preservation.
### **RMD Planning & Roth Conversions**
Support for Required Minimum Distributions, strategic Roth conversions, and IRA tax planning.
### **Small-Business Planning**
Retirement plans, compensation structure reviews, business transition planning, and integrated tax strategy for Hillsboro small-business owners.
# **A Local Fiduciary Advisor You Can Trust**
As a **fee-only, fiduciary financial advisor**, we act solely in your best interests.
No commissions. No product sales. No hidden incentives—ever.
Clients choose Independent Investment Advisors for:
- Transparent, independent advice
- Deep expertise in tax and equity compensation
- Highly personalized planning and investment management
- A boutique, multi-family-office–style experience
- Modern digital tools and clear reporting
We intentionally serve a limited number of families to maintain a high level of attention and proactive support.
# **Proudly Serving Hillsboro & Surrounding Communities**
We work with clients across:
- **Hillsboro**
- **Orenco Station**
- **AmberGlen**
- **Reedville**
- **South Hillsboro**
- **Tanasbourne**
- **Alohaburst / Westside tech corridor**
- **Forest Grove & Cornelius**
Our local focus strengthens our ability to understand the financial needs and challenges facing professionals and families in Washington County.
# **Visit Our Hillsboro Office**
**Independent Investment Advisors**
9620 NE Tanasbourne Dr Suite 300Hillsboro, OR 97124
Conveniently located near Orenco Station and the Tanasbourne/Amberglen business district, with easy access for Intel, Nike, and other Silicon Forest professionals.
# **Schedule a Consultation**
If you’re seeking a **Hillsboro financial advisor** who offers personalized planning, tax-efficient investing, and specialized equity-compensation guidance, we’re here to help.
[**Schedule your complimentary consultation**](https://outlook.office365.com/owa/calendar/IndependentInvestmentAdvisors@mlignw.com/bookings/)
---
### [Fee-Only Fiduciary Financial Planning and Wealth Management in Portland & Beaverton, Oregon](https://independentadvisorsnw.com/locations/portland-beaverton-oregon/)
**Published:** December 5, 2025
**Author:** MMGI Admin
**Content:**
# Fee-Only Fiduciary Financial Planning and Wealth Management in Portland & Beaverton, Oregon
Independent Investment Advisors is a boutique, fee-only fiduciary Registered Investment Advisor serving individuals and families throughout **Portland, Beaverton, Cedar Mill, Bethany, West Hills, Raleigh Hills, Multnomah Village, and the Westside tech corridor**. We provide comprehensive financial planning, wealth management, investment strategy, and advanced tax planning for technology professionals, small-business owners, executives, and high-net-worth families.
# **Serving Portland’s Westside, Urban Professionals & Beaverton’s Technology Community**
The greater Portland area is home to a diverse mix of technology companies, engineering firms, creative organizations, and multinational employers, including **Nike, Intel, Tektronix, Amazon, Salesforce, Precision Castparts, and Providence**. Many clients face complex equity compensation, multi-state tax issues, or the need for integrated financial oversight.
We specialize in:
- RSUs, ESPPs, and stock option planning
- ISOs and AMT strategy
- Tax-efficient stock diversification
- Advanced investment and portfolio design
- Retirement income and distribution strategy
- Multi-state income tax considerations for mobile and hybrid workers
Professionals in **Cedar Mill, Bethany, Raleigh Hills, Multnomah Village, Beaverton Central, The Round, and downtown Portland** trust us to bring clarity and disciplined guidance to their financial lives.
# **Comprehensive Wealth Management & Financial Planning in Portland & Beaverton**
We help clients achieve their goals with customized, comprehensive strategies for financial, investment, equity compensation, risk, and tax planning. Our services include:
### **Financial Planning & Retirement Planning**
Goal-based planning, retirement projections, tax-efficient withdrawal strategies, and Social Security optimization.
### **Wealth Management & Investment Management**
Portfolio design, risk management, rebalancing, tax-loss harvesting, and long-term investment oversight.
### **Equity Compensation & Tax Strategy**
RSUs, ESPPs, stock options, AMT planning, and concentrated equity risk management.
### **Inheritance, Estate & Legacy Planning**
Beneficiary reviews, multi-generational planning, coordination with estate attorneys, and integrated legacy strategy.
### **RMD Planning & Roth Conversions**
Support for Required Minimum Distributions, strategic Roth IRA conversions, and retirement tax planning.
### **Small-Business & Executive Planning**
Retirement plans, equity structures, business-transition guidance, and compensation planning for Portland and Beaverton small-business owners and executives.
# **A Local Fee-Only, Fiduciary Advisor Serving Portland & Beaverton**
As a fee-only Registered Investment Advisor, we always act in your best interests.
No commissions. No product sales. No hidden incentives.
Clients work with us because we provide:
- Transparent, data-driven financial and tax planning
- A boutique, multi-family-office–style experience
- Deep specialization in tax planning and equity compensation
- Customized investment strategies tailored to long-term goals
- Proactive communication and structured annual planning processes
We intentionally limit the number of families we serve to deliver a highly personalized client experience.
# **Proudly Serving Portland, Beaverton & Surrounding Communities**
Our firm supports clients across:
- **Portland (West Hills, Southwest, Northwest, Pearl District)**
- **Beaverton (Cedar Hills, Five Oaks, Triple Creek, Vose, Raleigh West)**
- **Cedar Mill**
- **Bethany**
- **Raleigh Hills**
- **Multnomah Village**
- **Garden Home**
- **Tigard, Tualatin & Lake Oswego**
- **Westside & Silicon Forest tech corridor**
Our local knowledge helps us better understand the unique financial needs of professionals and families in the region.
# **Visit Our Portland / Beaverton Office**
**Independent Investment Advisors**
13843 Northwest Thompson Road, Portland, OR 97229
Convenient to downtown Portland, Beaverton Central, Cedar Hills, and Bethany, with easy access via US-26 and Hwy 217.
# **Schedule a Consultation**
If you’re searching for a **Beaverton financial advisor** or **Portland fiduciary planner** specializing in comprehensive planning, tax-efficient wealth management, and sophisticated equity compensation guidance, we’re here to help.
**[Schedule your complimentary consultation](https://outlook.office365.com/owa/calendar/IndependentInvestmentAdvisors@mlignw.com/bookings/)**
---
### [Independent Investment Advisors – Local Wealth Management & Financial Planning for the Pacific Northwest](https://independentadvisorsnw.com/locations/)
**Published:** December 4, 2025
**Author:** Investment Advisor
**Content:**
# Independent Investment Advisors – Local Wealth Management & Financial Planning for the Pacific Northwest
At Independent Investment Advisors, we provide fee-only, fiduciary financial planning, wealth management, and tax strategy services to technology professionals, small-business owners, executives, and families throughout the Hillsboro and greater Portland metro area. As an independent boutique RIA, we focus on a limited number of households, delivering personalized, data-driven guidance with full transparency and no commissions.
## **Comprehensive Financial Planning and Wealth Management**
We help clients achieve their goals with customized, comprehensive strategies for financial, investment, equity compensation, risk, and tax planning. Whether you’re navigating stock compensation, preparing for retirement, analyzing your cash flow, or managing a complex financial portfolio, our team integrates planning and investment management into one cohesive approach.
Our core services include:
- **Wealth Management & Investment Management**
- **Financial Planning & Retirement Planning**
- **Equity Compensation Planning (RSUs, ESPPs, Stock Options, AMT)**
- **Tax Planning & Ongoing Tax Strategy**
- **Education Planning & Cash Flow Planning**
- **Small-Business Financial Planning & Retirement Plans**
- **Inheritance & Estate Planning Coordination**
- **RMD Planning, Roth Conversions & Inherited IRA Planning**
## **A Fiduciary, Fee-Only Advisor You Can Trust**
As a fiduciary Registered Investment Advisor, we act solely in your best interests.
No commissions. No product sales. No hidden incentives—ever.
We serve clients throughout:
- **Hillsboro**
- **Beaverton**
- **Portland**
- **Tualatin Valley / Silicon Forest Tech Corridor**
- **Cedar Mill & Bethany**
- **Orenco, AmberGlen & South Hillsboro**
- **Tigard, Tualatin, Sherwood, and surrounding communities**
Technology professionals and small-business owners in the region rely on us for unbiased, sophisticated wealth and tax planning.
## **Specialized Expertise for Technology Professionals**
The Portland/Hillsboro area is home to major employers such as Intel, Nike, Salesforce, Tektronix, Amazon, and numerous startups. We help tech-industry clients manage the complexity that comes with:
- RSUs
- ESPPs
- Non-qualified stock options
- Incentive stock options
- Concentrated stock risk
- AMT exposure
- Multi-state tax considerations
Our planning is built on real data—not speculation—and focuses on long-term wealth preservation.
## **Local, Personalized Service for High-Net-Worth Families**
We limit the number of families we serve so we can offer deeper planning, proactive communication, and customized portfolio management. Clients benefit from our boutique, multi-family-office-style approach:
- Integrated financial & tax planning
- Customized asset allocation and portfolio management
- Tax-efficient investing strategies
- Coordination with CPAs, estate attorneys & other professionals
- Transparent reporting and modern digital client experience
## **Visit Us at Either Local Office**
### **Hillsboro Office**
**Independent Investment Advisors**
[9620 NE Tanasbourne Dr Suite 300, Hillsboro, OR 97124](https://independentadvisorsnw.com/locations/hillsboro-oregon/)
Convenient for clients in Hillsboro, Orenco, AmberGlen, South Hillsboro, and the Silicon Forest tech corridor.
### **Portland / Beaverton Office**
**Independent Investment Advisors**
[13843 Northwest Thompson Road, Portland, OR 97229](https://independentadvisorsnw.com/locations/portland-beaverton-oregon/)
Serving clients across Portland, Beaverton, Cedar Mill, Bethany, Tigard, and surrounding communities.
## **Schedule a Consultation**
If you’re looking for a fiduciary advisor who provides comprehensive planning, integrated tax strategy, and highly personalized wealth management, we’re here to help.
**Schedule a complimentary virtual introductory consultation** **[here](https://outlook.office365.com/owa/calendar/IndependentInvestmentAdvisors@mlignw.com/bookings/)**!
---
### [Services](https://independentadvisorsnw.com/services/)
**Published:** September 20, 2019
**Author:** Investment Advisor
**Content:**

## Comprehensive Plan + Ongoing Risk Management + Time = Success!
Financial success isn’t the result of chance — it’s the outcome of clear planning, disciplined execution, and long-term perspective. At Independent Investment Advisors, **we partner with clients to create personalized strategies that evolve with their lives and the markets**.
We work collaboratively with your broader team of professionals such as CPA’s, estate attorneys, and other advisors to ensure every piece of your financial life is connected and working toward the same goals. Our **approach avoids unnecessary complexity and illiquidity, focusing instead on transparent, proven strategies: diversified portfolios of equities, ETFs, bonds, real estate investment trusts, and carefully selected managers**. Where appropriate, we also employ advanced tools such as options strategies to manage risk or define investment outcomes.
[**Client Focus & Approach**](#Client-Focus-&-Approach)
[**Integrated Comprehensive Financial, retirement & Tax Planning**](#Integrated-Comprehensive-Financial-Planning)
[**Investment Portfolio Management**](#Investment-Portfolio-Management)
---
## Client Focus & Approach
We provide **integrated, comprehensive wealth management services** — including financial planning, tax strategies, and investment portfolio management — for individuals, families, estates, trusts, and business owners.
Every new client relationship begins with an in-depth discovery process. We assess your investable assets, goals, constraints, and risk tolerance, often in collaboration with your other trusted professionals such as estate attorneys, tax advisors, and CPA’s.
From this foundation, we design a customized investment strategy tailored to your objectives. Portfolios are implemented thoughtfully and adjusted over time, with allocation changes made in response to both market conditions and your evolving needs.
---
## Integrated Comprehensive Financial Planning
We believe financial planning is not a one-time project but an ongoing process that evolves with your life. Our planning services integrate all areas of wealth management — investments, taxes, retirement, Insurance, estate, and beyond — into a single, coordinated strategy.
### **Core Financial Planning Services**
Every client engagement begins with a holistic financial plan that addresses the essentials of financial well-being:
#### **Retirement Planning**
- **Build a Personalized Roadmap** – Develop a clear plan to achieve financial independence, tailored to your lifestyle goals and long-term vision.
- **Structure Reliable Income Streams** – Coordinate savings, investments, Social Security, pensions, and other sources to create sustainable retirement income.
- **Optimize Withdrawals** – Sequence withdrawals strategically across taxable, tax-deferred, and tax-free accounts to extend portfolio longevity and improve tax efficiency.
- **Plan for Longevity and Risks** – Account for healthcare costs, inflation, and potential market downturns so your retirement plan adapts to changing conditions.
#### **Tax Planning**
- **Integrate Tax Efficiency Across Your Portfolio** – Design investment strategies that minimize tax drag and maximize after-tax returns.
- **Manage Equity Compensation** – Develop tailored strategies for RSUs, ESPPs, and stock options to reduce tax surprises and improve after-tax value.
- **Coordinate with Your CPA** – Partner with your tax professional to implement advanced tax strategies with accuracy and consistency.
- **Leverage Strategic Timing** – Identify opportunities such as Roth conversions, charitable giving, or tax-loss harvesting to lower overall tax liability.
#### **Estate Planning**
- **Align Wealth with Legacy Goals** – Ensure your estate plan reflects your financial objectives, family values, and multi-generational priorities.
- **Coordinate Estate Documents** – Work alongside estate attorneys to establish or update wills, trusts, and charitable giving strategies.
- **Review Beneficiary Designations** – Confirm accounts are properly structured to transfer assets efficiently and according to your wishes.
- **Minimize Potential Estate Taxes** – Explore strategies to reduce tax exposure and preserve more wealth for heirs and charitable causes.
#### **Education Planning**
- **Create Tax-Advantaged Savings Strategies** – Use 529 plans, custodial accounts, and other tools to maximize growth while reducing tax impact.
- **Plan for Multiple Generations** – Design funding strategies for children, grandchildren, or other loved ones, aligned with your broader financial plan.
- **Balance Competing Priorities** – Coordinate education savings goals with retirement, tax, and investment strategies to ensure financial balance.
- **Review Funding Flexibility** – Evaluate trust-based solutions or other vehicles that provide both control and adaptability for future education needs.
### **Advanced Planning Solutions**
For clients with complex needs, we offer specialized planning strategies that address unique financial circumstances:
#### **Equity Compensation & Concentrated Stock Planning**
- **Manage Concentrated Wealth Risks** – Develop strategies to reduce the financial risks tied to large equity positions or employer stock holdings.
- **Optimize Equity Compensation Timing** – Evaluate when to exercise stock options and sell RSUs/ESPP shares to balance tax efficiency with growth potential.
- **Diversify Thoughtfully** – Create structured diversification strategies that reduce single-stock risk while protecting long-term wealth.
- **Maximize After-Tax Outcomes** – Coordinate equity decisions with tax planning to capture more value and reduce surprises.
#### **Risk Management & Insurance Planning**
- **Identify Key Financial Risks** – Assess potential risks such as disability, liability, or loss of income that could affect your long-term financial goals.
- **Integrate Insurance Strategically** – Align insurance solutions (life, disability, long-term care, liability coverage) with your broader wealth management plan.
- **Coordinate with Estate & Tax Planning** – Ensure protection strategies are consistent with your estate plan, tax considerations, and legacy goals.
- **Adapt Coverage Over Time** – Regularly review insurance needs as careers evolve, families grow, and wealth accumulates.
#### **Business & Succession Planning**
- **Prepare for Liquidity Events** – Develop strategies for selling, transitioning, or passing down your business while safeguarding personal wealth.
- **Integrate Business & Personal Wealth** – Align business ownership decisions with family financial planning and retirement strategies.
- **Support Family-Owned Business Transitions** – Design succession plans that preserve both the business and family harmony across generations.
- **Plan for Growth & Exit** – Balance reinvestment in business growth with long-term exit strategies that protect your legacy.
#### **Debt & Credit Planning**
- **Use Leverage Strategically** – Structure debt in ways that support wealth-building opportunities without creating unnecessary financial strain.
- **Optimize Credit Access** – Improve borrowing terms and access to credit while keeping overall costs manageable.
- **Balance Debt with Goals** – Ensure debt decisions align with retirement, investment, and tax strategies.
- **Enhance Financial Flexibility** – Create a plan for repayment and refinancing to maintain liquidity and adaptability over time.
#### **An Ongoing Partnership**
Our financial planning process is not static. As your life evolves — career transitions, liquidity events, retirement, or generational planning — we revisit and adjust your plan to keep you aligned with your goals.
---
## Investment Portfolio Management
Our investment philosophy is rooted in discipline, diversification, and alignment with each client’s unique goals, tax profile, and risk tolerance. Every portfolio is customized and may include both **core strategies** for long-term stability and **advanced solutions** for clients with more specialized needs.
### **Core Strategies**
These approaches form the foundation of most client portfolios:
#### **Allocated Portfolio**
- **Diversified Across Asset Classes** – Build portfolios with a mix of equities, bonds, ETFs, and carefully selected professional managers to reduce risk and enhance stability.
- **Balanced Geographic Exposure** – Maintain a U.S.-weighted focus while incorporating global investments where appropriate for broader diversification.
- **Dynamic Allocation Adjustments** – Review and adjust allocations regularly based on client needs, economic trends, and market opportunities.
- **Long-Term Goal Alignment** – Structure portfolios around mid- to long-term objectives such as retirement, legacy planning, or wealth preservation.
#### **Tactical Portfolio**
- **Active Management Approach** – Designed for clients with higher risk tolerance who seek to take advantage of shorter-term opportunities.
- **Flexible Investment Tools** – Utilize ETFs, individual securities, and options to respond quickly to market trends and opportunities.
- **Responsive Allocation Shifts** – Adjust allocations proactively in response to changing economic data, market volatility, or client circumstances.
- **Higher Engagement Strategy** – Provide more frequent oversight and decision-making for clients who prefer an active investment approach.
#### **Defined Outcome Portfolio**
- **Moderate Growth with Boundaries** – Target growth potential within defined outcome ranges to create clarity around possible results.
- **Options-Based Structuring** – Use ETFs and options to shape return profiles, manage downside risk, and capture opportunities efficiently.
- **Actively Managed Positions** – Monitor and adjust positions to stay aligned with client goals and evolving market conditions.
- **Suited for Balanced Investors** – Ideal for those seeking growth but with clearer expectations around risk and reward.
### **Advanced Solutions**
For clients with more complex wealth management needs, we provide specialized investment approaches that enhance customization, tax efficiency, and diversification.
#### **Direct Indexing Strategies**
- **Own Individual Securities** – Replicate an index by directly owning its underlying securities, rather than holding a single ETF or mutual fund.
- **Enhance Tax Efficiency** – Use tax-loss harvesting at the individual security level to offset gains and improve after-tax results.
- **Customize Exposure** – Adjust index holdings to manage concentrated stock positions, avoid overlap with employer stock, or reduce sector concentration.
- **Incorporate Values-Based Investing** – Personalize portfolios by excluding certain industries or overweighting companies that align with your values and priorities.
- **Flexible & Transparent Approach** – Gain greater control over portfolio construction while maintaining broad market exposure.
#### **Alternative Investments** *(for qualified investors)*
- **Expand Diversification Beyond Traditional Markets** – Access strategies with return drivers not directly correlated to stocks and bonds.
- **Potential for Enhanced Risk-Adjusted Returns** – Incorporate alternatives that may help manage volatility and improve long-term outcomes.
- **Broad Range of Options** – Depending on suitability, strategies may include private equity, private credit, hedge funds, real estate, infrastructure, or structured products.
- **Carefully Evaluated for Fit** – Each opportunity is assessed for liquidity, risk profile, and alignment with your overall wealth management strategy.
- **Integrated into the Bigger Picture** – Ensure that alternative holdings complement your core portfolio, estate plan, and tax strategy.
#### **Our Role as Fiduciary Advisors**
Whether your portfolio is built on **core strategies** alone or enhanced with **advanced solutions**, our role is the same:
- Ensure each strategy aligns with your goals and risk tolerance.
- Integrate investments with your tax, estate, and financial planning.
- Provide ongoing monitoring and adjustments as markets and your life change.
---
---
### [Solutions](https://independentadvisorsnw.com/solutions/)
**Published:** April 10, 2020
**Author:** Investment Advisor
**Content:**

## Integrated Wealth Solutions for Complex Lives
At Independent Investment Advisors, we serve individuals, families, estates, trusts, professionals, and business owners with solutions that bring together **financial and retirement planning, tax strategies, and investment management**. Our integrated approach ensures that every part of your financial life works in harmony — so you can focus on what matters most.
[**Mid-Career Technology Professionals**](#Mid-Career-Technology-Professionals)
[**Retirement Solutions**](#Retirement-Solutions)
[**Tax Optimization Strategies**](#Tax-Optimization-Strategies)
[**Estate & Inheritance Planning**](#Estate-&-Inheritance-Planning)
[**Business Owner Solutions**](#Business-Owner-Solutions)
[**Investment & Wealth Management**](#Investment-&-Wealth-Management)
---
## Solutions for Mid-Career Technology Professionals
Technology professionals often build significant wealth through a mix of salary, bonuses, and equity compensation — but managing those resources effectively requires careful planning. [We specialize in helping tech executives, engineers, and mid-career professionals:](https://independentadvisorsnw.com/solutions/wealth-management-for-tech-professionals-in-portland-hillsboro-beaverton-and-seattle/)
- **Manage Equity Compensation** – Evaluate stock options, RSUs, ESPPs, and concentrated stock positions to balance long-term growth with near-term tax efficiency.
- **Plan for Liquidity Events** – Determine when and how to exercise options or sell shares, diversify holdings, and manage the tax impact of major equity transactions.
- **Optimize Tax Strategies** – Integrate income, investment, and equity compensation into a tax-aware plan designed to minimize liability and maximize after-tax wealth.
- **Pursue Early Financial Independence** – Design roadmaps for career transitions or early retirement, incorporating aggressive savings goals and flexible income strategies.
- **Build Family Wealth Plans** – Coordinate education savings, estate planning, and insurance to protect loved ones and prepare for future generations.
- **Reduce Concentrated Stock Risk** – Implement diversification strategies for those whose net worth is tied to employer stock or a single sector.
---
## Retirement Solutions
A secure and fulfilling retirement requires more than just saving — it demands a coordinated strategy that adapts over time. We help clients:
- **Develop Customized Retirement Plans** – Align lifestyle goals with financial realities through scenario testing and projections.
- **Maximize Retirement Accounts** – Optimize contributions and withdrawals across 401(k)s, IRAs, and Roth IRAs for long-term growth and tax efficiency.
- **Simplify Accounts** – Consolidate multiple employer retirement accounts into a streamlined portfolio with greater flexibility and oversight.
- **Evaluate Roth Conversions** – Identify opportunities where converting to a Roth IRA may reduce lifetime tax liability.
- **Create Business Retirement Plans** – Establish SEP IRAs, SIMPLE IRAs, or custom solutions tailored for self-employed professionals and business owners.
---
## Tax Optimization Strategies
Taxes can be one of the largest expenses high-net-worth families face. We integrate tax planning into every aspect of wealth management by:
- **Designing Tax-Efficient Portfolios** – Place investments strategically in taxable, tax-deferred, and tax-free accounts to reduce drag on returns.
- **Managing Equity Compensation** – Structure the exercise and sale of stock options, RSUs, and ESPPs to limit tax surprises.
- **Coordinating with CPAs** – Partner with your tax professional to ensure strategies are implemented accurately and proactively.
- **Leveraging Charitable Giving** – Use donor-advised funds, appreciated stock donations, or other strategies to reduce tax burdens while supporting causes you care about.
---
## Estate & Inheritance Planning
Preserving wealth for future generations requires careful planning. We help clients:
- **Clarify Legacy Goals** – Ensure your estate plan reflects both financial priorities and family values.
- **Coordinate Estate Documents** – Work alongside your estate attorney to align wills, trusts, and other documents with your broader financial strategy.
- **Prepare for Inheritance** – Provide guidance when receiving a windfall (inheritance, settlement, insurance payout) to make informed short- and long-term decisions.
- **Implement Gifting Strategies** – Establish trust, custodial, or charitable accounts to transfer wealth effectively and tax-efficiently.
---
## Business Owner Solutions
[Small business owners face unique financial challenges](https://independentadvisorsnw.com/solutions/financial-investment-solutions-for-small-business-owners/) — both personally and professionally. With deep experience in this area, we provide solutions such as:
- **Business Retirement Plans** – Create SEP IRAs, SIMPLE IRAs, or tailored retirement plans to benefit both owners and employees.
- **Succession & Exit Planning** – Prepare for liquidity events, ownership transfers, or business sales while protecting personal wealth.
- **Integrated Tax Strategies** – Optimize both personal and business finances to reduce overall tax liability.
- **Business Cash Management** – Build operating cash strategies that preserve value, keep pace with inflation, and maintain liquidity.
- **HOA & Nonprofit Solutions** – Support organizations in managing reserve funds and operating capital with conservative, goal-based portfolios.
---
## Investment & Wealth Management
Our portfolios are designed to support your goals with clarity and transparency. Depending on your needs, we provide:
- **Allocated Portfolios** – Long-term, diversified investment strategies across equities, bonds, ETFs, and managers with adjustments based on markets and client needs.
- **Tactical Portfolios** – Actively managed portfolios using ETFs, individual securities, and options for clients seeking shorter-term opportunities with higher risk tolerance.
- **Defined Outcome Portfolios** – Structured strategies using ETFs and options designed to manage downside risk while pursuing moderate growth.
- **Direct Indexing Strategies** – Customize index exposure for tax-loss harvesting, values-based investing, or to offset concentrated stock positions.
- **Alternative Investments** – For qualified clients, access to private equity, private credit, hedge funds, and real assets as part of a broader diversification strategy.
---
## Why Clients Choose Us
---
Our clients come to us because they want:
- **Independent, fiduciary, and fee-only advice** — always aligned with their best interests.
- **Integrated solutions** that address planning, investments, taxes, and estate needs together.
- **Specialized expertise** in equity compensation, small business wealth, and complex family needs.
- **A boutique relationship** that provides clarity, personalized attention, and ongoing guidance.
---
### [Can I Contribute to a Roth IRA in 2025? [Free Flowchart Download]](https://independentadvisorsnw.com/can-i-contribute-to-a-roth-ira-in-2025-free-flowchart-download/)
**Published:** May 14, 2025
**Author:** Goran Ognjenovic
**Content:**
**Enjoyed the free flowchart?**
We invest significant time and expertise to create these resources and offer them freely—no email required. If you found the Roth IRA flowchart helpful, please consider leaving us a [Google review](https://g.page/r/CftndDG0KmP-EBM/review). Your feedback not only supports our work but also helps others discover valuable tools like this. Thank you!
**Confused about Roth IRA contribution rules for 2025?**
Our free downloadable flowchart breaks it all down—clearly, visually, and with updated IRS income limits. Whether you’re filing solo or jointly, this tool helps you determine eligibility in seconds.
✅ Understand Roth IRA income thresholds
✅ Learn what counts as earned income
✅ See how traditional IRA contributions may affect your eligibility
✅ Quick reference for clients, DIY investors, or anyone planning for retirement
---
#### 📥 **Download the 2025 Roth IRA Contribution Flowchart (PDF)**
This simple yet comprehensive tool will walk you through the decision-making process step-by-step.
👉[ ]()**[Click here to download](https://independentadvisorsnw.com/download/2968/?tmstv=1747241136)**
---
#### Who Is This Flowchart For?
- **Tech professionals and high-income earners** navigating MAGI limits
- **Dual-income households** evaluating contribution limits
- **DIY investors and financial planners** seeking IRS-compliant guidance
- **Anyone 50+** considering catch-up contributions
---
#### About the Creator
This guide is licensed to **Goran Ognjenovic**, founder of Independent Investment Advisors in Hillsboro, Oregon. We specialize in tax-aware investment and retirement strategies for professionals and families throughout the Pacific Northwest.
> “Clear, simple guidance like this can prevent costly tax mistakes and ensure you’re making the most of your retirement options.” — *Goran Ognjenovic*
---
#### 📌 Stay Informed
Want more planning checklists, tax tips, and investment strategies?
[Subscribe to our newsletter](https://independentadvisorsnw.com/contact-us/markets-insights-signup/) or [schedule a consultation](https://outlook.office365.com/book/IndependentInvestmentAdvisors@mlignw.com/).
---
**Disclaimer**: This tool is for informational purposes only and does not constitute investment or tax advice. Consult a qualified advisor for personalized recommendations.
---
### [About](https://independentadvisorsnw.com/about/)
**Published:** September 19, 2019
**Author:** Investment Advisor
**Content:**
# About Us
At **Independent Investment Advisors**, we believe that financial success is built on trust, transparency, and a truly personalized approach.
As a **fee-only fiduciary firm**, we are committed to acting in your best interest—providing **tax-efficient wealth management, retirement planning, and investment strategies** tailored to high-net-worth individuals, business owners, and professionals.
🏆 **Awarded Best Financial Planner in Hillsboro 2024**, we proudly serve clients across the **Portland Metro Area, including Hillsboro and Beaverton**. Whether you’re looking for a fiduciary financial advisor in Portland or prefer personalized financial guidance close to home, we’re here to help. **[Learn more about our services in Hillsboro & Beaverton here](https://independentadvisorsnw.com/about/top-fiduciary-financial-advisor-in-hillsboro-or-wealth-planning-you-can-trust/)**.
Our mission is simple: **help you grow and protect your wealth so you can focus on what matters most.** Whether you’re planning for retirement, navigating a business transition, or looking for an investment strategy that aligns with your long-term goals, we’re here to guide you every step of the way.
## About Our Leadership Team
---
Goran Ognjenovic
Founder and Principal Advisor
With **over 18 years of experience** in financial markets, I bring a **strategic, analytical, and client-focused approach** to wealth management. My journey began in 2003 as an individual trader and investor, where I developed a **deep understanding of portfolio construction, market cycles, and long-term investment success**. In 2015, I founded **Independent Investment Advisors**, driven by the belief that **every client deserves transparent, fiduciary-driven financial guidance tailored to their unique goals**.
As a **fee-only fiduciary**, my commitment is to **serve my clients’ best interests—always**.
I specialize in working with **high-net-worth individuals, business owners, and professionals**, helping them achieve financial security through **tax-efficient investment strategies, retirement planning, and risk management**.
🏆 **Awarded Best Financial Planner in Hillsboro 2024**, I take pride in providing high-quality, independent financial advice to clients across the **Portland Metro Area, including Hillsboro and Beaverton**.
🏅 **Recognized in ETF.com’s Top 100 Financial Leaders List**, I have been honored for my expertise and leadership in **investment strategy and portfolio management**.
### **Why Clients Trust Me:**
✅ **Proven Market Expertise** – Nearly two decades of navigating complex financial markets.
✅ **Holistic Financial Planning** – A **comprehensive approach** integrating investments, tax strategies, and estate planning.
✅ **Clear, Strategic Guidance** – I simplify complex financial decisions so clients can **act with confidence**.
✅ **Local & Personalized Service** – Based in the **Portland Metro Area**, serving clients in **Hillsboro, Beaverton, and beyond**.
My mission is simple: **to help you protect, grow, and optimize your wealth—so you can focus on what matters most.** Whether you’re preparing for retirement, planning for your business, or seeking investment strategies that align with your goals, I’m here to help you navigate your financial journey with clarity and confidence.
---
Danijela Ognjenovic
Founder and Operations Director
As the **Director of Operations & Client Experience Manager** at **Independent Investment Advisors**, I ensure that every aspect of our firm runs smoothly, efficiently, and with a client-first approach. With over **10 years of experience** in **business operations, management, marketing, and customer service**, I specialize in creating seamless experiences for our clients, from onboarding to ongoing support.
I hold a **Bachelor of Science degree from Portland State University** and have a strong background in strategic operations. Before joining **Independent Investment Advisors**, I managed high-level operations for one of the **top global sports brands**, where I led customer service, marketing, sales, and financial management initiatives. I spearheaded a **new client service strategy that increased customer satisfaction by 15%**, reinforcing my passion for delivering **exceptional client experiences**.
At **Independent Investment Advisors**, I oversee all **behind-the-scenes operations**, ensuring that our processes, technology, and client interactions align with our **high standards of fiduciary excellence**. My goal is to **streamline workflows, enhance client engagement, and provide top-tier service** so our clients feel supported at every stage of their financial journey.
I take pride in **building meaningful client relationships**, ensuring every detail is handled with care and precision. Whether it’s coordinating account management, optimizing internal processes, or enhancing communication, I am dedicated to making sure our clients have the best possible experience.
## Our Certified Financial & Tax Planning Support Team

## Features & Articles
### [ETF.com: Recognized as a Top 100 Financial Advisor by ETF.com!](https://independentadvisorsnw.com/exciting-news-recognized-as-a-top-100-financial-advisor-by-etf-com/)
### [Goran Ognjenovic on Mastering Wealth: A CEO Weekly Feature](https://independentadvisorsnw.com/goran-ognjenovic-featured-in-a-ceo-weekly-article-mastering-wealth-with-ognjenovics-strategic-insights-sep-9th-2024/)
### [USA Today: Goran Ognjenovic on Life Holistic Wealth Management](https://independentadvisorsnw.com/goran-ognjenovic-featured-in-a-usa-today-article-independent-investment-advisors-offers-a-holistic-approach-to-wealth-management-aug-27th-2024/)
### [Forbes Spotlight: Goran Ognjenovic on Inspiring Customer-Success Strategies](https://independentadvisorsnw.com/goran-ognjenovic-featured-in-a-forbes-article-3-strategies-for-small-businesses-to-remain-customer-centric-may-15th-2024/)
### [Nasdaq.com: Goran Ognjenovic on Holistic Approach to Wealth Management for Financial Success](https://independentadvisorsnw.com/goran-ognjenovic-featured-in-a-nasdaq-article-a-holistic-approach-to-wealth-management-for-financial-success-march-5th-2024/)
### [MSN Article: Goran Ognjenovic Wealth Management Blueprint: Charting a Path to Secure Retirement](https://independentadvisorsnw.com/goran-ognjenovic-featured-in-a-msn-article-wealth-management-blueprint-charting-a-path-to-secure-retirement-december-8th-2023/)

[](https://adviserinfo.sec.gov/firm/summary/286170)
### [FREQUENTLY ASKED QUESTIONS](https://independentadvisorsnw.com/about/faq/)
Chief Investment Advisor interview with Sabrina Medyanikov publisher of Bethany & Cedar Mill Living social magazine.
Watch our Chief Investment Advisor interview with Sabrina Medyanikov publisher of Bethany & Cedar Mill Living. You will learn more about how we work with clients and when you should start working with an Investment Advisor.
[Click here to read the full Bethany & Cedar Mill Living Magazine Sponsor Spotlight](https://independentadvisorsnw.com/about/bethany-cedar-mill-living-sponsor-spotlight/)
It’s been a long time since investors have had to worry about inflation. Now it’s making headlines, because prices are rising faster than expected.
Congress recently released a blueprint of what future tax laws could look like. Here’s what you need to know.
Equity markets in turmoil. It’s the end of the world! Not!
---
## Our News & Announcements
### [Independent Investment Advisors Receives 2023 Best of Portland Award – Financial Planner](https://independentadvisorsnw.com/independent-investment-advisors-receives-2023-best-of-portland-award-financial-planner/)
[Financial Planner](https://independentadvisorsnw.com/author/financial-planner/)
March 30, 2023
PORTLAND January 22, 2023 – For two consecutive years, Independent Investment Advisors has been selected for the 2023 Best of Portland Award in the Financial Planner category by the Portland Award Program.
[Continue Reading Independent Investment Advisors Receives 2023 Best of Portland Award – Financial Planner](https://independentadvisorsnw.com/independent-investment-advisors-receives-2023-best-of-portland-award-financial-planner/)
### [Independent Investment Advisors Receives Financial Advisory of the Year – Oregon Award](https://independentadvisorsnw.com/independent-investment-advisors-receives-financial-advisory-of-the-year-oregon-award/)
[Investment Advisor](https://independentadvisorsnw.com/author/investment-advisor/)
November 30, 2022
PORTLAND October, 2022 — Independent Investment Advisors has been selected for the 2022/23 Financial Advisory of the Year | Oregon by the Corporate Livewire and LTG / USA Prestige Guide
[Continue Reading Independent Investment Advisors Receives Financial Advisory of the Year – Oregon Award](https://independentadvisorsnw.com/independent-investment-advisors-receives-financial-advisory-of-the-year-oregon-award/)
### [Independent Investment Advisors Receives 2022 Best of Portland Award](https://independentadvisorsnw.com/independent-investment-advisors-receives-2022-best-of-portland-award/)
[Financial Planner](https://independentadvisorsnw.com/author/financial-planner/)
August 1, 2022
PORTLAND July 22, 2022 — Independent Investment Advisors has been selected for the 2022 Best of Portland Award in the Financial Planner category by the Portland Award Program. Each year, the Portland Award Program identifies companies that we believe have achieved exceptional success in their local community and business category.
[Continue Reading Independent Investment Advisors Receives 2022 Best of Portland Award](https://independentadvisorsnw.com/independent-investment-advisors-receives-2022-best-of-portland-award/)
### [We are thrilled to announce our third managed portfolio program: Structured or Defined Outcome Portfolio](https://independentadvisorsnw.com/we-are-thrilled-to-announce-our-third-managed-portfolio-program-structured-or-defined-outcome-portfolio/)
[Portfolio Manager](https://independentadvisorsnw.com/author/portfolio-manager/)
September 15, 2020
This portfolio program is well suited for a general investment or savings portfolio—an investor looking to grow their investment at a moderate rate without a long-term investment horizon. Perhaps even for a real estate investor looking to diversify. The portfolio approach primarily consists of US registered index ETF’s and derivatives, more specifically, options. The portfolio approach also takes advantage of…
[Continue Reading We are thrilled to announce our third managed portfolio program: Structured or Defined Outcome Portfolio](https://independentadvisorsnw.com/we-are-thrilled-to-announce-our-third-managed-portfolio-program-structured-or-defined-outcome-portfolio/)
### [We expanded our custodian and technology provider agreements to include Charles Schwab Institutional.](https://independentadvisorsnw.com/we-expanded-our-custodian-and-technology-provider-agreements-to-include-charles-schwab-institutional/)
[Investment Advisor](https://independentadvisorsnw.com/author/investment-advisor/)
August 7, 2020
We are happy to announce that we have expanded our custodial network to include Charles Schwab. Schwab is an industry leader—proudly supporting more independent advisors than any other custodian. Our new relationship allows our allocated portfolio clients to diversify and expand their portfolios, especially in fixed income space.
[Continue Reading We expanded our custodian and technology provider agreements to include Charles Schwab Institutional.](https://independentadvisorsnw.com/we-expanded-our-custodian-and-technology-provider-agreements-to-include-charles-schwab-institutional/)
### [Independent Investment Advisors featured by Bethany & Cedar Mill Living Magazine](https://independentadvisorsnw.com/independent-investment-advisors-bethany-cedar-mill-living-feature/)
[Investment Advisor](https://independentadvisorsnw.com/author/investment-advisor/)
May 26, 2020
We are thrilled to announce the Bethany & Cedar Mill Living magazine feature. Our founder and principal investment advisor is getting featured as the local financial expert in the Bethany & Cedar Mill Living magazine. A social magazine for residents of Bethany & Cedar Mill neighborhoods located in Portland, OR. We have been Cedar Mill residents for thirteen years, so…
[Continue Reading Independent Investment Advisors featured by Bethany & Cedar Mill Living Magazine](https://independentadvisorsnw.com/independent-investment-advisors-bethany-cedar-mill-living-feature/)
### [Our Trading-Tools API Engine Is Live](https://independentadvisorsnw.com/our-tradingtools-api-engine-is-live/)
[Active Trader](https://independentadvisorsnw.com/author/active-trader/)
February 13, 2020
We are thrilled to announce that after roughly 18 months of development, our Trading-Tools Real Tick API engine is live and performing as expected. We now can build granular and highly customized market scans, automated trading systems and rules, and place, manage, and allocate orders into various portfolios.
[Continue Reading Our Trading-Tools API Engine Is Live](https://independentadvisorsnw.com/our-tradingtools-api-engine-is-live/)
### [We expanded our custodian and technology provider agreements to include Wedbush Securities Institutional Advanced Clearing Services.](https://independentadvisorsnw.com/we-expanded-our-custodian-and-technology-provider-agreements-to-include-wedbush-securities-institutional-advanced-clearing-services/)
[Investment Advisor](https://independentadvisorsnw.com/author/investment-advisor/)
January 15, 2020
We are happy to announce that we have expanded our custodial network to include Wedbush Securities Institutional. As a clearing leader for over 40 years, Wedbush Securities Advanced Clearing Services specializes in providing custom tailored clearing and custody and full-service solutions.
[Continue Reading We expanded our custodian and technology provider agreements to include Wedbush Securities Institutional Advanced Clearing Services.](https://independentadvisorsnw.com/we-expanded-our-custodian-and-technology-provider-agreements-to-include-wedbush-securities-institutional-advanced-clearing-services/)
---
### [Boutique vs. Big-Box Wealth Management: Which is Right for You?](https://independentadvisorsnw.com/homepage/education/boutique-vs-big-box-wealth-management-which-is-right-for-you/)
**Published:** April 16, 2025
**Author:** Ian Teh
**Content:**
[< back to Investor Education Center](https://independentadvisorsnw.com/homepage/education/)
# Boutique vs. Big-Box Wealth Management: Which is Right for You?
### How Your Choice of Advisor Could Impact the Next Decade of Your Wealth!
If you’re a mid-career tech professional, your financial life is likely more complex than most. You may have equity compensation in multiple forms (RSUs, ISOs, ESPPs, NSOs), a growing investment portfolio, rising income, and a host of competing goals—retirement, kids’ education, lifestyle planning, aging parents, and maybe a liquidity event on the horizon.
And yet, despite all that complexity, most tech professionals still default to one big question when seeking help:
**“Should I work with a big, national wealth management firm—or is a smaller, boutique advisor a better fit?”**
Here’s how to make the right decision for your goals, your wealth, and your peace of mind.
---
## What Do We Mean by Big-Box vs. Boutique Wealth Management?
### Big-Box Wealth Management
Think of large, nationally recognized firms: Merrill Lynch, Morgan Stanley, UBS, Fidelity, or Schwab. These firms:
- Are often affiliated with banks or brokerage platforms
- Offer a wide range of standardized products and services
- Rely heavily on proprietary technology and platforms
- Employ a largely digital experience with high application abandonment rates (up to 68%)
- May have incentives to recommend proprietary mutual funds with internal fees 0.75–1.5% higher than boutique-curated solutions,【[Buffalo Funds](https://buffalofunds.com/wp-content/uploads/Potential-Advantages-of-Boutique-Managers.pdf)】【[Advisorpedia](https://www.advisorpedia.com/viewpoints/advice-big-box-shop-or-private-firm/)】
### Boutique Wealth Management
Smaller, independent RIAs (Registered Investment Advisors) or fiduciary wealth management firms:
- Typically focus on a specific client niche (e.g., tech professionals, business owners, retirees)
- Use independent, best-in-class tools and third-party platforms
- Have adaptable architecture that allows quarterly investment model updates—compared to 12–18 month cycles in big-box shops【[F2 Strategy](https://www.f2strategy.com/insight/the-battle-between-flexibility-and-integration-in-wealthtech)】
- Are often free of proprietary product pressure, reducing conflicts of interest【[F2 Strategy](https://www.f2strategy.com/insight/the-battle-between-flexibility-and-integration-in-wealthtech)】【[Advisorpedia](https://www.advisorpedia.com/viewpoints/advice-big-box-shop-or-private-firm/)】
---
## Key Differences That Matter to You
### 🔹 Personalization & Client Load
- **Big Box:** Advisors may manage 150–300+ clients; personalization tends to be limited and templated.
- **Boutique:** Advisors typically manage fewer than 100 clients, enabling deeper personal relationships and tailored financial plans. These relationships often help guide clients through emotional decision-making around money【[LinkedIn Pulse](http://www.linkedin.com/pulse/rise-boutique-financial-firms-why-high-net-worth-clients-peyton-5ep7e)】.
### 🔹 Fiduciary vs. Product-Driven Models
- **Big Box:** May operate under a suitability standard and use commission-based structures. Advisors often recommend in-house mutual funds or annuities, which come with hidden 12b-1 fees, platform fees, and revenue-sharing agreements—costing investors 0.3%–1.7% annually in drag【[Seeking Alpha](https://seekingalpha.com/article/4496852-suitability-vs-fiduciary)】【[Advisorpedia](https://www.advisorpedia.com/viewpoints/advice-big-box-shop-or-private-firm/)】.
- **Boutique:** Most operate as fiduciaries. They are legally obligated to act in your best interest, and typically avoid conflicts by avoiding proprietary products. 83% of boutique RIAs use third-party tools like Nitrogen to support planning and scenario modeling for ISO exercises【[F2 Strategy](https://www.f2strategy.com/insight/the-battle-between-flexibility-and-integration-in-wealthtech)】.
### 🔹 Tech Stack & Planning Agility
- **Big Box:** Use proprietary platforms and are often restricted in what they can recommend. Model updates typically occur every 12–18 months, making them slower to react to market changes【[McKinsey](https://www.mckinsey.com/industries/financial-services/our-insights/us-wealth-management-amid-market-turbulence-an-industry-converges)】【[F2 Strategy](https://www.f2strategy.com/insight/the-battle-between-flexibility-and-integration-in-wealthtech)】.
- **Boutique:** Tech-agnostic firms can integrate specialized tools to manage tax optimization, estate planning, and equity compensation. With fewer bureaucratic layers, boutiques can respond more quickly to client requests and market volatility【[Private Wealth](https://privatewealth.com/trusting-a-boutique-wealth-management-firm-pays-off/)】【[F2 Strategy](https://www.f2strategy.com/insight/the-battle-between-flexibility-and-integration-in-wealthtech)】.
### 🔹 Holistic Planning vs. Product Focus
- **Big Box:** Investment-centric models often neglect the nuances of tax timing, 83(b) elections, or multi-generational equity transfer strategies. Up to 34% of equity recipients are underprepared for changes in compensation structure as a result【[Kitces](https://www.kitces.com/blog/equity-compensation-planning-executives-stockopter-option-grants-share-grants-valuation-analysis-modeling/)】.
- **Boutique:** Planning is core to their value proposition—equity comp modeling, tax optimization, retirement simulations, and estate coordination are baked into the relationship from the start.
---
## What Tech Professionals Really Need from an Advisor
If you’re working in tech—especially in Hillsboro’s growing Silicon Forest ecosystem or remote roles for companies like Intel, Meta, Amazon, or smaller startups—your financial complexity demands more than investment management:
✅ RSU and ISO planning with tax-efficient sales strategies
✅ NSO and 83(b) modeling for growth-stage startups
✅ Managing risk and overconcentration from company stock
✅ Tax-smart diversification and liquidity planning
✅ Coordinated estate, retirement, and insurance strategies
These areas require flexibility, planning depth, and a customized approach—not mass-market products and templated portfolios.
---
## Boutique vs. Big Box: Side-by-Side Comparison
FeatureBig-Box FirmBoutique FirmClient-to-advisor ratioHigh (~200–300)Low (~50–100)PersonalizationLimitedHighly tailoredFiduciary standardSometimesAlwaysProduct useOften proprietaryZero proprietary productsFee transparencyVaries; may include hidden feesFlat or AUM-based; clearTech tools & flexibilityProprietary; limited adaptabilityCurated tech stack; fast model updatesApplication completion rateLower (up to 68% abandon apps)High (simplified onboarding)Planning integrationInvestment-focusedHolistic (tax, equity, estate, goals)---
## How to Decide What’s Right for You
Ask yourself:
- Do I want a relationship or a product?
- Do I want fast answers and personalized advice—or access to an 800 number?
- Do I need integrated tax, investment, and equity compensation planning?
- Do I value a flexible advisor or one tied to a corporate platform?
If you want **true planning depth, objectivity, and service continuity**, a boutique wealth manager may be the better fit.
---
## Final Thoughts: Choose Fit Over Familiarity
There’s no one-size-fits-all answer—but your choice of advisor will affect everything from your tax bill to your peace of mind. For high-earning professionals with complex needs, the **flexibility, responsiveness, and strategic depth of a boutique firm** often delivers better long-term outcomes.
*\*\*written and researched by Ian Teh*
---
### [RSUs, ISOs, NSOs & ESPPs: How to Minimize Taxes & Maximize Gains](https://independentadvisorsnw.com/homepage/education/rsus-isos-nsos-espps-how-to-minimize-taxes-maximize-gains/)
**Published:** March 20, 2025
**Author:** Ian Teh
**Content:**
# RSUs, ISOs, NSOs & ESPPs: How to Minimize Taxes & Maximize Gains
## Why Tech Professionals in Oregon Need a Smart Tax Strategy for Equity Compensation
Hillsboro, Oregon, is home to some of the country’s most innovative technology companies, including Intel, NVIDIA, and multiple startups in the Silicon Forest. Many professionals working in these companies receive a significant portion of their compensation through Restricted Stock Units (RSUs), Incentive Stock Options (ISOs), Non-Qualified Stock Options (NSOs), and Employee Stock Purchase Plans (ESPPs). While these forms of equity compensation can be a powerful wealth-building tool, they also come with complex tax implications that can erode potential gains if not managed strategically.

Understanding vesting schedules, tax treatment, and local Oregon tax considerations is crucial for maximizing profits and minimizing tax liabilities. Here’s what you need to know if you work in Hillsboro’s booming tech sector.
## Understanding the Tax Treatment of RSUs, ISOs, NSOs & ESPPs:
### Restricted Stock Units (RSUs) & Tax Treatment:
✅ Taxed as ordinary income upon vesting.
✅ Additional gains are subject to capital gains tax if held post-vesting.
✅ Oregon does not have a sales tax, but all RSU income is subject to Oregon state income tax.
✅ RSUs can be used as collateral for loans to unlock liquidity without triggering a taxable event.
💡 Best Practice: Because RSUs are taxed as income at vesting, many professionals in Hillsboro sell them immediately to reinvest in a diversified portfolio and avoid further concentration in employer stock. Alternatively, donating RSU shares to a Donor Advised Fund (DAF) can provide tax benefits while funding future charitable giving.
### Incentive Stock Options (ISOs) & Tax Planning:
✅ No tax upon grant or exercise, but AMT (Alternative Minimum Tax) may apply.
✅ If held for 2+ years from grant & 1+ year from exercise, gains are taxed at long-term capital gains rates.
✅ Oregon follows federal AMT rules, meaning high-income earners should carefully plan ISO exercises.
✅ Selling ISOs and realizing a large negative AMT adjustment in the same year as a new exercise can help reduce AMT credit loss.
✅ Early ISO exercise at a startup can significantly increase long-term net gains while lowering upfront costs.
💡 Best Practice: ISOs can be a great long-term wealth builder, but exercising too many at once can trigger AMT. Work with a tax advisor to exercise them gradually to minimize tax impact.
### Non-Qualified Stock Options (NSOs) & Tax Treatment:
✅ NSOs are taxed as ordinary income upon exercise, unlike ISOs.
✅ Subject to payroll taxes (Social Security & Medicare), making them more costly tax-wise than ISOs.
✅ Capital gains tax applies if held after exercise and sold later.
✅ NSOs do not qualify for AMT treatment, which can be beneficial for high earners.
✅ If exercised while the company’s valuation is low, employees can minimize their taxable income.
💡 Best Practice: Pairing NSO exercises with ISO exercises can help minimize or eliminate AMT exposure by offsetting AMT implications of ISOs with ordinary income from NSOs (3040 Wealth). Selling just enough shares to cover tax costs can help retain more ownership while managing cash flow.
### Comparison of NSOs vs. ISOs:
FeatureNSOISOTaxed at ExerciseYes (Ordinary Income)NoSubject to AMT?NoYes (if not managed)Payroll Tax Applies?YesNoCapital Gains EligibilityYes (if held post-exercise)Yes (if held 2+ years from grant & 1+ year from exercise)Best forHigh earners who want flexibilityEmployees planning for long-term capital gains### Employee Stock Purchase Plans (ESPPs) & Tax Optimization:
✅ Stock purchased at a discount (usually 15%).
✅ If shares are held for 1 year after purchase & 2 years after offering date, gains qualify for long-term capital gains tax.
✅ Early sales result in higher tax rates, with gains taxed as ordinary income.
✅ Using the lookback feature to purchase shares at the lowest price during the offering period can maximize your discount and potential gains.
💡 Best Practice: If you work at Intel or another Hillsboro-based tech firm offering ESPPs, holding shares for the required period can lead to significant tax savings. However, diversification is key—consider selling some ESPP shares once eligible to avoid overconcentration.
## Advanced Tax Strategies for High-Income Earners in Hillsboro:
### Pairing NSOs with ISOs to Manage AMT Exposure.
Pairing NSO exercises with ISO exercises can help minimize AMT exposure by offsetting AMT implications of ISOs with ordinary income from NSOs.
83(b) Election for NSOs: If you have nonvested NSOs, filing an 83(b) election allows you to shift taxation from ordinary income to capital gains, which can result in lower overall taxes if the company’s stock appreciates.
### Tax-Efficient Strategies for Exercising NSOs:
✅ Exercise NSOs when the company’s valuation is lower to minimize the amount taxed at ordinary income rates.
✅ Sell just enough shares to cover tax costs, retaining more ownership while managing cash flow.
### Using Pledged Lines to Borrow Against Stock Holdings vs. Selling:
For tech professionals who want liquidity without immediately selling stock holdings, a pledged line of credit (also called a securities-backed line of credit, or SBLOC) allows borrowing against stock holdings without triggering a taxable event. This strategy can be especially beneficial for those with highly appreciated stock who want to access funds while deferring capital gains taxes.
✅ Liquidity without selling: Borrowing against stock holdings can provide access to capital for major purchases, investments, or emergency needs without forcing a sale.
✅ Tax efficiency: Since no sale occurs, capital gains taxes are not triggered, preserving more wealth in the long run.
✅ Potential risks: If stock values drop significantly, lenders may require additional collateral or loan repayment, so careful risk management is essential.
💡 Best Practice: Use pledged lines for short-term liquidity needs, but be mindful of market volatility and maintain a diversified portfolio to avoid excessive risk exposure.
Final Takeaway: Proactive Tax Planning Can Save You Thousands. Equity compensation can be a major wealth-building tool—but only if managed correctly. Without a tax plan, you risk giving up a large portion of your gains to unnecessary taxes.
---
### [Frequently Asked Questions (FAQs) – Independent Investment Advisors](https://independentadvisorsnw.com/about/faq/)
**Published:** April 10, 2020
**Author:** Investment Advisor
**Content:**
## **Frequently Asked Questions (FAQs) – Independent Investment Advisors**
*Serving clients in* ***Beaverton, Hillsboro, and the Portland Metro Area****.*
### **General Questions**
**1. What does a fiduciary financial advisor do?**
A **fiduciary financial advisor** is legally and ethically bound to act in your best interests. As a **fee-only fiduciary**, we provide **unbiased financial advice** without earning commissions from financial products. [Learn more about our fiduciary approach.](https://independentadvisorsnw.com/services/)
**2. Why should I choose Independent Investment Advisors?**
🏆 **Awarded Best Financial Planner in Hillsboro 2024**
🏅 **Named to ETF.com’s Top 100 Leaders List**
⭐ **2024 Five Star Wealth Manager Award Recipient**
We specialize in **tax-efficient investment strategies, [retirement planning,](https://independentadvisorsnw.com/advisor-qa-how-to-guide-to-tax-optimized-investing-examples-of-strategies-that-combine-tax-efficiency-with-effective-retirement-planning/) and wealth management** for high-net-worth individuals, professionals, and business owners in **Beaverton, Hillsboro, and Portland Metro**. [See how we can help you.](https://independentadvisorsnw.com/about/)
**3. Where are you located, and do you work with clients outside of Beaverton and Hillsboro?**
Our office is located in the **Portland Metro Area**, and we work with clients **throughout Oregon and nationwide** via secure virtual consultations. [Explore our services in Beaverton.](https://independentadvisorsnw.com/solutions/wealth-management-for-tech-professionals-in-portland-hillsboro-beaverton-and-seattle/)
---
### **Investment & Financial Planning**
**4. What investment strategies do you use?**
We focus on **evidence-based investment strategies**, including **diversified portfolios, [tax optimization,](https://independentadvisorsnw.com/advisor-qa-how-to-guide-to-tax-optimized-investing-tax-deductions-and-incentives/) and risk management** tailored to your financial goals. [Learn about our investment approach.](https://independentadvisorsnw.com/advisor-qa-how-to-guide-to-tax-optimized-investing-tax-deductions-and-incentives/)
**5. How do you manage risk in investment portfolios?**
Our strategies include **diversification, [tax-efficient investing,](https://independentadvisorsnw.com/how-does-an-individuals-risk-tolerance-influence-their-tax-efficient-retirement-and-investment-decisions/) and active risk management** to help protect your wealth. [Discover our portfolio management strategies.](https://independentadvisorsnw.com/tech-stocks-your-portfolio-how-to-avoid-overconcentration-risk/)
**6. Can you help with 401(k) rollovers and retirement planning?**
Yes! We assist with **401(k) rollovers, IRA strategies, and comprehensive retirement planning** to maximize your savings and minimize tax liabilities. [Start planning your retirement](https://app.rightcapital.com/account/sign-up?referral=6hYSryvU83RoJbpuPuVq2g&type=client).
---
### **Tax & Estate Planning**
**7. How does tax [planning fit into my financial](https://independentadvisorsnw.com/about/top-fiduciary-financial-advisor-in-beaverton-or-wealth-planning-for-your-future/) strategy?**
We integrate **tax-efficient investment strategies** to reduce tax liabilities, including **capital gains tax minimization, Roth conversions, and strategic asset location**. [Optimize your tax strategy.](https://independentadvisorsnw.com/advisor-qa-how-to-guide-to-tax-optimized-investing-tax-deductible-strategies/)
**8. Do you provide estate planning services?**
Yes, we coordinate with estate attorneys to develop **estate and legacy planning strategies** that align with your long-term financial goals. Learn about estate planning.
---
### **Working With Us**
**9. How do I get started?**
We begin with a **free consultation** to understand your financial goals and assess how we can help. [Schedule a consultation today.](https://outlook.office365.com/book/IndependentInvestmentAdvisors@mlignw.com/)
**10. How do you charge for your services?**
We operate on a **transparent fee-only model**, meaning no hidden fees or commissions—just straightforward financial guidance. [See our pricing structure.](https://files.adviserinfo.sec.gov/IAPD/Content/Common/crd_iapd_Brochure.aspx?BRCHR_VRSN_ID=936938)
**11. Can I manage some of my investments on my own while working with you?**
Yes! We offer **co-managed portfolio options**, allowing you to stay involved while benefiting from our expertise. [Explore our investment services.](https://independentadvisorsnw.com/solutions/)
**12. How do you protect my personal and financial information?**
We follow strict **confidentiality and cybersecurity protocols** to ensure your financial data is protected at all times. [Learn about our security measures.](https://independentadvisorsnw.com/about/privacy-policy/)
---
### **Contact Us**
📞 **Call us at 971-350-8068**
📍 **Serving Beaverton, Hillsboro, and the Portland Metro Area**
📅 **[Schedule a Free Consultation](https://outlook.office365.com/owa/calendar/IndependentInvestmentAdvisors@mlignw.com/bookings/)**
Choosing the right financial advisor is a critical decision. Let’s discuss your goals and create a **customized financial strategy** that works for you!
---
### [Tax Strategies to Minimize Taxes & Maximize Gains in Oregon](https://independentadvisorsnw.com/homepage/education_2/tax-strategies-to-minimize-taxes-maximize-gains-in-oregon/)
**Published:** March 7, 2025
**Author:** Ian Teh
**Content:**
[< back to Investor Education Center](https://independentadvisorsnw.com/homepage/education_2/)
# Tax Strategies to Minimize Taxes & Maximize Gains in Oregon
Navigating Oregon’s tax landscape effectively is crucial for preserving and growing your wealth. Whether you’re managing investment income, equity compensation, or planning for retirement, implementing strategic tax-saving techniques can significantly impact your financial future. With Oregon’s relatively high state income taxes, residents must be especially proactive in minimizing tax liability.
One of the most effective ways to optimize and reduce taxes is by fully utilizing tax-advantaged accounts. These accounts not only provide valuable tax breaks but also serve as essential tools for long-term wealth accumulation. Many tax-saving strategies focus on projecting and planning for future tax rates, considering both economic trends and personal financial decisions.
## Maximize Tax Savings with Retirement Accounts
### 401(k), 403(b), and 457 Plans
Employer-sponsored retirement accounts offer tax-deferred growth and immediate tax savings by reducing taxable income. In 2025, the contribution limits for these plans are:
- **$23,500** for individuals
- **$7,500 additional “catch-up” contribution** for those aged 50 and older
- **New Super Catch-Up Rule**: Starting in 2025, individuals aged 60 to 63 can contribute an additional **$10,000** (or 150% of the standard catch-up contribution, whichever is greater) to their 401(k) or 403(b), providing a significant tax planning opportunity for those nearing retirement.
For Oregon residents, pre-tax contributions to employer retirement plans can be particularly beneficial since Oregon does not tax retirement withdrawals from out-of-state sources, making Roth conversions and multi-state planning even more relevant.
### Traditional and Roth IRAs
Depending on your financial situation and income level, a **Traditional IRA** offers an immediate tax deduction, while a **Roth IRA** provides tax-free withdrawals in retirement. Given Oregon’s state tax structure, Roth accounts can be especially advantageous for those who anticipate higher future income or are planning for intergenerational wealth transfer.
---
## Health Savings Accounts (HSA): Triple Tax Benefits
An **HSA** is one of the most tax-efficient investment accounts available, offering: ✔ **Tax-deductible contributions**
✔ **Tax-free investment growth**
✔ **Tax-free withdrawals** for qualified medical expenses
For 2025, HSA contribution limits are:
- **$4,300** for individuals
- **$8,550** for families
- **$1,000 additional catch-up contribution** for individuals 55 and older
Oregon does not provide a state-level deduction for HSA contributions, but the federal benefits make HSAs a valuable tool for reducing long-term healthcare costs.
---
## 529 Education Savings Plans: Tax-Advantaged College Savings
529 plans offer **tax-free growth and withdrawals** when used for qualified education expenses. While Oregon **no longer provides a state tax deduction for contributions**, residents can still benefit from federal tax advantages.
💡 **Pro Tip**: Even if you don’t have children, you can open a 529 account for yourself to save for continuing education or future academic pursuits.
---
# Advanced Tax Strategies to Reduce Lifetime Tax Liability
## **Roth Conversions: Optimizing for Tax-Free Growth**
A Roth IRA conversion moves funds from a Traditional IRA into a Roth IRA, requiring you to pay taxes now in exchange for **tax-free withdrawals later**. This strategy is beneficial if: ✅ You expect to be in a **higher tax bracket in retirement**
✅ You have **low taxable income in a particular year**
✅ You want to **reduce Required Minimum Distributions (RMDs)** and future tax liability
### Oregon-Specific Roth Strategy
Because Oregon does not tax Roth IRA withdrawals, **converting while in a lower tax bracket** is a smart way to reduce state and federal tax burdens over time.
---
## **Tax-Efficient Charitable Giving Strategies**
Strategic philanthropy can reduce your taxable income while supporting causes you care about. Key options include:
✔ **Bunching Donations with a Donor-Advised Fund (DAF)**
Contribute multiple years’ worth of charitable donations in one year to exceed the standard deduction and maximize tax savings.
✔ **Qualified Charitable Distributions (QCDs)**
If you’re **70½ or older**, you can donate up to **$100,000 per year** directly from your IRA to a qualified charity. This reduces taxable income and satisfies RMDs without increasing your adjusted gross income (AGI).
✔ **Donating Appreciated Securities**
Instead of selling stocks and paying **capital gains taxes**, donate them directly to a charity. You’ll avoid capital gains tax and receive a deduction for the full market value.
---
## **Tax-Efficient Withdrawal Strategies in Retirement**
A well-planned withdrawal sequence can reduce taxes and **increase the longevity of your portfolio**.
### Optimal Withdrawal Order:
1️⃣ **Taxable Accounts (Brokerage Accounts)** – Withdraw from these first to allow tax-advantaged accounts to continue growing.
2️⃣ **Tax-Deferred Accounts (401(k), Traditional IRA)** – Withdraw next to balance tax brackets.
3️⃣ **Tax-Free Accounts (Roth IRAs)** – Withdraw last for maximum tax-free growth.
💡 **Key Retirement Tax Considerations in Oregon**
- **No state tax on Social Security income**
- **State tax exemption of up to $6,250 for some pension income**
- **High-income retirees may benefit from partial-year residency strategies to reduce state taxes**
---
# **Final Thoughts**
Effective tax planning can make a **substantial difference** in your overall wealth. Whether you’re maximizing **tax-advantaged accounts, leveraging Roth conversions, or optimizing withdrawal strategies**, a proactive approach ensures long-term financial success.
🔹 **Oregon residents face unique tax considerations**, making it crucial to work with a **qualified financial advisor** who understands local and federal tax laws.
---
### [Investor Education: Empowering Your Path to Financial Success](https://independentadvisorsnw.com/homepage/education_2/)
**Published:** October 25, 2023
**Author:** Financial Planner
**Content:**
### [Is it Time to See a Financial Advisor?](https://independentadvisorsnw.com/homepage/education/is-it-time-to-see-a-finanacial-advisor/ "independentadvisorsnw.com/homepage/investor-education-center/is-it-time-to-see-a-finanacial-advisor/")
[](https://independentadvisorsnw.com/homepage/education/is-it-time-to-see-a-finanacial-advisor/)
*Are you managing your money by yourself or preparing for retirement? How do you know when its time to consult a [financial or investment](https://independentadvisorsnw.com/independent-investment-advisors-receives-financial-advisory-of-the-year-oregon-award/) advisor?*
### [Outearned Your Financial Strategy?](https://independentadvisorsnw.com/homepage/education/outearned-your-financial-strategy/)
[](https://independentadvisorsnw.com/homepage/education/outearned-your-financial-strategy/)
Has your income suddenly become more complex? Gone are the days of a straightforward salary, plus bonuses and maybe commissions. To get where you are, you’ve taken on more responsibility and achieved higher-level decision-making abilities.
### [Business Owner Exit Planning](https://independentadvisorsnw.com/homepage/education/business-owner-exit-planning/)
[](https://independentadvisorsnw.com/homepage/education/business-owner-exit-planning/)
If you’re a business owner who is thinking of stepping back, selling, or retiring, you have a lot to think about. Do you have a clear picture of what your exit strategy looks like? This guide breaks down what you need to know to plan your personal exit strategy. Check it out!
### [Invest with Your Head, Not with Your Heart](https://independentadvisorsnw.com/homepage/education/invest-with-your-head-not-with-your-heart/)
[](https://independentadvisorsnw.com/homepage/education/invest-with-your-head-not-with-your-heart/)
Are you moved by the swings in the stock market, ready to trade at a moments notice? Or are you looking for the hottest stock that will undoubtedly make you thousands of dollars?
### [Annual and Lifetime Gift Tax Exclusions Primer](https://independentadvisorsnw.com/homepage/education/annual-and-lifetime-gift-tax-exclusions-primer/)
[](https://independentadvisorsnw.com/homepage/education/annual-and-lifetime-gift-tax-exclusions-primer/)
As the year-end approaches, it’s essential to start tax and gift planning efforts. There are several nuances to current federal rules when it comes to gift tax exclusions. Here are some of the most notable details you everyone needs to know.
### [The Simple 3-Step Medicare Guide](https://independentadvisorsnw.com/homepage/education/the-simple-3-step-medicare-guide/)
[](https://independentadvisorsnw.com/homepage/education/the-simple-3-step-medicare-guide/)
Whether you’re looking into Medicare for the first time, or taking advantage of annual enrollment to update your strategy, we’ve broken down the critical choices you must make into a simple decision-making tool
### [Do You Know What Constitutes Your Credit Score?](https://independentadvisorsnw.com/homepage/education/do-you-know-what-constitutes-your-credit-score/ "independentadvisorsnw.com/homepage/investor-education-center/do-you-know-what-constitutes-your-credit-score/")
[](https://independentadvisorsnw.com/homepage/education/do-you-know-what-constitutes-your-credit-score/)
Are you bewildered by your credit score? Are you wondering how to increase your score or why your score has taken a nosedive?
### [Prospects for Investing in the 2020s](https://independentadvisorsnw.com/homepage/education/prospects-for-investing-in-the-2020s/)
[](https://independentadvisorsnw.com/homepage/education/prospects-for-investing-in-the-2020s/)
The third decade of the 21st century started with a strong economy, record low unemployment levels, and benign inflation. But late in the first quarter over the span of two weeks, investors faced the fastest stock market correction in history.
### [What Should You Do With An Old 401(k)?](https://independentadvisorsnw.com/homepage/education/what-should-you-do-with-an-old-401k/)
[](https://independentadvisorsnw.com/homepage/education/what-should-you-do-with-an-old-401k/)
If you are considering a job change in the future or have already made the transition, you may be wondering, “What should I do with my old 401k”? You have several options to consider – cash it out, let it be, or roll it over into your new plan or an IRA. There are benefits and drawbacks of each to consider.
### [Advisor Q&A: How to Guide to Tax Optimized Investing](https://independentadvisorsnw.com/homepage/education/advisor-qa-how-to-guide-to-tax-optimized-investing/)
[](https://independentadvisorsnw.com/homepage/education/advisor-qa-how-to-guide-to-tax-optimized-investing/)
In the complex landscape of financial planning, mastering the art of tax-efficient [investing is crucial for optimizing](https://independentadvisorsnw.com/advisor-qa-how-to-guide-to-tax-optimized-investing-tax-deductions-and-incentives/) wealth accumulation and achieving long-term financial goals. This comprehensive guide, ‘Advisor Q&A: Tax-Efficient Investing,’ brings together expert insights and actionable advice.
### [Economic Correlation Cyclical and Non-Cyclical Stocks](https://independentadvisorsnw.com/homepage/education/economic-correlation-cyclical-and-non-cyclical-stocks/)
[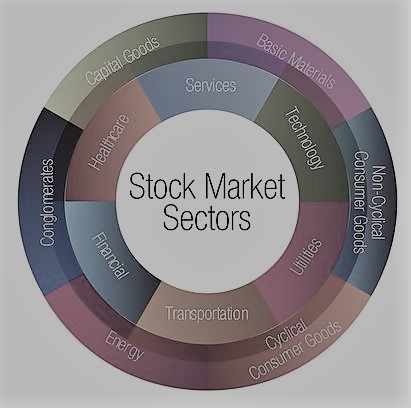](https://independentadvisorsnw.com/homepage/education/economic-correlation-cyclical-and-non-cyclical-stocks/)
When the U.S. experiences robust economic growth, specific stock market sectors tend to rise while others hold steady or even decline by comparison. The stocks of companies that experience higher revenues are typically categorized as cyclical.
### [Top Ten Financial Planning Tips for Business Owners](https://independentadvisorsnw.com/homepage/education/top-ten-financial-planning-tips-for-business-owners/)
[](https://independentadvisorsnw.com/homepage/education/top-ten-financial-planning-tips-for-business-owners/)
If you are a [business owner](https://independentadvisorsnw.com/homepage/education/top-ten-financial-planning-tips-for-business-owners/) this is a must read. Some very important tips on how to think about your future and your business.
### [End of Year Financial Checkup](https://independentadvisorsnw.com/homepage/education/end-of-year-financial-checkup/)
[](https://independentadvisorsnw.com/homepage/education/end-of-year-financial-checkup/)
The end of a fiscal year brings many opportunities to reflect on our financial objectives, our financial blunders, and our financial accomplishments for the year. Think back to the goals you set for yourself at the beginning of the year. Did you get where you wanted to? If not, why? If so, congratulations! Let’s rinse and repeat!
### [Give Smarter & Make a Greater Impact with Philanthropy](https://independentadvisorsnw.com/homepage/education/give-smarter-make-a-greater-impact-with-philanthropy/ "Give Smarter & Make a Greater Impact with Philanthropy")
[](https://independentadvisorsnw.com/homepage/education/give-smarter-make-a-greater-impact-with-philanthropy/)What inspires you to give? Most of us give for the same basic reasons. We want to help others, make a positive difference in the world—and giving feels good. It makes us happy, and it connects us to the causes we care about.
### [Tax Strategies to Minimize Taxes & Maximize Gains in Oregon](https://independentadvisorsnw.com/homepage/education_2/tax-strategies-to-minimize-taxes-maximize-gains-in-oregon/)
[](https://independentadvisorsnw.com/homepage/education_2/tax-strategies-to-minimize-taxes-maximize-gains-in-oregon/)Navigating Oregon’s tax landscape effectively is crucial for preserving and growing your wealth. Whether you’re managing investment income, equity compensation, or planning for retirement, implementing strategic tax-saving techniques can significantly impact your financial future.
### [Brokers vs. Advisors: What’s the Difference?](https://independentadvisorsnw.com/homepage/education/brokers-vs-advisors-whats-the-difference/)
[](https://independentadvisorsnw.com/homepage/education/brokers-vs-advisors-whats-the-difference/)While brokers and advisors may fill similar roles in a client’s life, the services they offer and fees they charge can vary greatly.
### [Primer to Gross Domestic Product](https://independentadvisorsnw.com/homepage/education/gross-domestic-product-a-primer/)
[](https://independentadvisorsnw.com/homepage/education/gross-domestic-product-a-primer/)
The economic indicator known as Gross Domestic Product (GDP) represents the dollar value of all purchased goods and services over one year. It is comprised of purchases from all private and public consumption, including for-profit, nonprofit, and government sectors.
### [Borrowing From Your Retirement Plan: New CARES Act Rules](https://independentadvisorsnw.com/borrowing-from-your-retirement-plan-new-cares-act-rules/)
[](https://independentadvisorsnw.com/borrowing-from-your-retirement-plan-new-cares-act-rules/)In late March, Congress passed the Coronavirus Aid, Relief and Economic Security Act (CARES Act). This bill offered provisions related to distributions from retirement accounts.
### [6 Small Business Retirement Plans](https://independentadvisorsnw.com/homepage/education/6-small-business-retirement-plans/)
[](https://independentadvisorsnw.com/homepage/education/6-small-business-retirement-plans/)
Like almost everything else, setting up a retirement savings plan falls on the shoulders of a small business owner. The [plan you chose depends on your business’s](https://independentadvisorsnw.com/homepage/education/top-ten-financial-planning-tips-for-business-owners/) size, how it’s structured, and how much money you think you can afford to put aside.
### [Opportunities Opened Up By New TAX Rules](https://independentadvisorsnw.com/homepage/education/opportunities-opened-up-by-new-tax-rules/)
[](https://independentadvisorsnw.com/homepage/education/opportunities-opened-up-by-new-tax-rules/)
The Tax Cut and Jobs Act (TCJA), passed at the end of 2017, and SECURE (Setting Every Community Up for Retirement Enhancement) Act, passed at the end of 2019, radically changed your tax picture.1 Most Americans are going to pay less in taxes under the new tax brackets, and a few are going to use this great [opportunity to permanently lower the taxes](https://independentadvisorsnw.com/homepage/education/opportunities-opened-up-by-new-tax-rules/) they pay.
**[1](https://independentadvisorsnw.com/homepage/education/) [2](https://independentadvisorsnw.com/homepage/education_2/)**
---
### [Wealth Management for Tech Professionals in Portland, Hillsboro, Beaverton, and Seattle](https://independentadvisorsnw.com/solutions/wealth-management-for-tech-professionals-in-portland-hillsboro-beaverton-and-seattle/)
**Published:** March 3, 2025
**Author:** MMGI Admin
**Content:**
# Wealth Management for Tech Professionals in Portland, Hillsboro, Beaverton, and Seattle
**Financial Strategies Designed for High-Earning Innovators**
As a tech professional, you’ve built your career on innovation, problem-solving, and driving forward the future. But when it comes to managing your wealth, navigating stock options, optimizing tax strategies, and planning for long-term financial security, the landscape can be just as complex as the technology you build. That’s where we come in.
### **Why Work with Us?**
At **Independent Investment Advisors**, we specialize in providing sophisticated wealth management solutions tailored to the unique needs of tech professionals in Portland, Hillsboro, Beaverton, and Seattle. Whether you’re an engineer, developer, founder, or executive, we take a boutique approach—working with a select number of client families to provide holistic financial planning, tax strategies, investment management, and estate planning.
### **The Challenges We Solve for Tech Professionals**
✅ **Equity Compensation Planning** – Navigating RSUs, ISOs, NSOs, and ESPPs can be daunting. We help you understand when and how to exercise your stock options to minimize taxes and maximize gains.
✅ **Tax-Efficient Wealth Growth** – Tech professionals often face high tax burdens. We build proactive tax strategies, including tax-loss harvesting, charitable giving strategies, and tax-efficient investment allocations.
✅ **Diversification Strategies** – Concentrated stock positions can create risk. We design customized diversification strategies to protect and grow your wealth while managing risk exposure.
✅ **Early Retirement & Financial Independence Planning** – Whether you’re pursuing FIRE (Financial Independence, Retire Early) or just want more flexibility, we create roadmaps to financial freedom tailored to your aspirations.
✅ **Private Investments & Alternative Assets** – We offer access to exclusive investment opportunities, including private equity, venture capital, and real estate, to align with your long-term goals.
✅ **Estate Planning for Tech Professionals** – From protecting intellectual property to creating trusts for future generations, we ensure your wealth is structured efficiently for legacy planning.
### **Our Approach: Boutique, Holistic, and Personalized**
Unlike large financial firms that provide cookie-cutter solutions, we focus on a select group of high-net-worth clients to deliver tailored strategies that evolve with your career and life changes. Our expertise spans:
- Coordinating with CPAs and attorneys to optimize your financial strategy.
- Implementing multi-generational wealth planning.
- Advising on liquidity events like IPOs, acquisitions, and stock sales.
### **Serving the Tech Community in Portland, Hillsboro, Beaverton, and Seattle**
Tech careers often come with rapid changes, from promotions and startup equity to career pivots and exit strategies. We ensure your financial strategy adapts as fast as your career evolves. We work closely with tech professionals in the Pacific Northwest’s thriving innovation hubs to provide strategic financial guidance that aligns with your goals.
**Let’s talk about your financial future.** [Schedule a consultation](https://outlook.office365.com/owa/calendar/IndependentInvestmentAdvisors@mlignw.com/bookings/) today to see how we can help you optimize your wealth and build long-term security.
---
### [Top Fiduciary Financial Advisor in Beaverton, OR – Wealth Planning for Your Future!](https://independentadvisorsnw.com/about/top-fiduciary-financial-advisor-in-beaverton-or-wealth-planning-for-your-future/)
**Published:** March 2, 2025
**Author:** MMGI Admin
**Content:**
# **Top Fiduciary Financial Advisor in Beaverton, OR – Wealth Planning for Your Future**
### **Your Trusted Independent Financial Advisor in Beaverton, OR**
Selecting the right financial advisor is one of the most important decisions you can make for your financial future. At **Independent Investment Advisors**, we provide **fee-only, fiduciary wealth management services** to individuals, business owners, and families in **Beaverton, OR, and the greater Portland Metro Area**.
🏆 **Awarded Best Financial Planner in Hillsboro 2024** – Recognized for excellence and client service.
🏅 **Named to the Top 100 ETF.com Leaders List** – Acknowledged for leadership and expertise in investment management.
🏆 **2023 Best of Portland Award Winner** – Honored for our commitment to excellence in the Portland Metro Area.
⭐ **2024 Five Star Wealth Manager Award Recipient** – Recognized for outstanding client service and industry leadership.
If you’re looking for a **personalized, tax-efficient approach** to financial planning, our team is ready to help.
---
## **Why Choose a Fiduciary Financial Advisor in Beaverton?**
As a **fee-only fiduciary firm**, we are legally bound to act in your best interest—unlike brokers who may earn commissions on financial products. Our goal is to provide **unbiased, transparent financial advice** that aligns with your long-term objectives.
Our clients choose us because they:
✅ **Need Tax-Efficient Investment Strategies** – We create portfolios designed to minimize taxes while maximizing growth.
✅ **Are Preparing for Retirement or Major Life Transitions** – Whether you’re approaching retirement, selling a business, or managing generational wealth, we offer expert guidance.
✅ **Own a Business or Have Complex Financial Needs** – We specialize in financial planning for **business owners, executives, and professionals** in Beaverton and beyond.
✅ **Value Personalized, Ongoing Financial Guidance** – We provide a **high-touch, relationship-driven approach** tailored to each client’s needs.
---
## **Our Comprehensive Wealth Management Services**
At **Independent Investment Advisors**, we offer a full range of financial services, including:
📌 **Investment Management** – Custom portfolios aligned with your goals and risk tolerance. 📌 **Tax Planning & Optimization** – Strategies designed to minimize tax liabilities and increase after-tax returns. 📌 **Retirement Planning** – Personalized income strategies to help secure a worry-free retirement. 📌 **Estate & Legacy Planning** – Ensuring your wealth is protected and transferred efficiently to future generations. 📌 **Risk Management & Asset Protection** – Protecting your financial future from unexpected risks.
---
## **Proudly Serving Beaverton, OR & Surrounding Communities**
Our office is conveniently located near **Beaverton, OR**, and we proudly serve clients across:
- **Beaverton, Hillsboro, and the Greater Portland Metro**
- **Tanasbourne, Cedar Hills, and Raleigh Hills**
- **Local business owners, tech professionals, and retirees**
We work with clients both **in-person and virtually**, utilizing **secure digital financial tools** to provide comprehensive wealth management solutions.
---
## **Schedule a Free Consultation Today**
📞 **Call us at 971-350-8068** or **[Schedule a Consultation](https://outlook.office365.com/owa/calendar/IndependentInvestmentAdvisors@mlignw.com/bookings/)**
Choosing the right financial advisor is an important decision. Let’s discuss your financial goals and determine if we’re the right fit for you.
---
### [Top Fiduciary Financial Advisor in Hillsboro, OR – Wealth Planning You Can Trust!](https://independentadvisorsnw.com/about/top-fiduciary-financial-advisor-in-hillsboro-or-wealth-planning-you-can-trust/)
**Published:** March 2, 2025
**Author:** MMGI Admin
**Content:**
# **Top Fiduciary Financial Advisor in Hillsboro, OR – Wealth Planning You Can Trust**!
### **Your Trusted Independent Financial Advisor in Hillsboro, OR**
Finding the right financial advisor is a crucial decision that impacts your wealth, retirement, and legacy. At **Independent Investment Advisors**, we provide **fee-only, fiduciary wealth management services** to professionals, business owners, and families in **Hillsboro, OR**, and the greater Portland Metro Area.
🏆 **Awarded Best Financial Planner in Hillsboro 2024** – Recognized for our commitment to excellence and client service.
If you’re looking for a **personalized, tax-efficient approach** to financial planning, we are here to help.
---
## **Why Work with a Fiduciary Financial Advisor in Hillsboro?**
As an **independent, fee-only fiduciary**, we are legally obligated to act in your best interest—unlike brokers who may earn commissions on financial products. This means our only priority is **your financial success**.
Our clients choose us because they:
✅ **Want a Tax-Efficient Investment Strategy** – We integrate investment management with proactive tax planning to minimize liabilities.
✅ **Are Preparing for Retirement or Major Life Transitions** – Whether retiring, selling a business, or receiving an inheritance, we help navigate these decisions with confidence.
✅ **Own a Business or Have Complex Financial Needs** – We provide financial planning tailored for **business owners, executives, and professionals** in Hillsboro and beyond.
✅ **Value a Long-Term Financial Partner** – We work closely with you to adapt your financial strategy as life evolves.
---
## **Comprehensive Wealth Management Services**
At **Independent Investment Advisors**, we provide holistic financial services, including:
📌 **Investment Management** – Customized, diversified portfolios tailored to your long-term goals. 📌 **Tax Planning & Optimization** – Strategies to reduce tax burdens for professionals and business owners. 📌 **Retirement Planning** – Secure your financial future with a personalized income strategy. 📌 **Estate & Legacy Planning** – Ensure your wealth is preserved for future generations. 📌 **Risk Management & Asset Protection** – Safeguard your financial well-being from unexpected challenges.
---
## **Serving Clients in Hillsboro, OR & Beyond**
Our office is conveniently located near **Hillsboro, OR**, and we proudly serve clients across:
- **Hillsboro, Beaverton, and the Greater Portland Metro**
- **Tanasbourne, Orenco Station, and Bethany**
- **Local tech industry professionals and business owners**
We work with clients both in-person and virtually, offering **secure digital financial tools** for remote collaboration.
---
## **Schedule a Free Consultation Today**
📞 **Call us at 971-350-8068** or **[Schedule a Consultation](https://outlook.office365.com/owa/calendar/IndependentInvestmentAdvisors@mlignw.com/bookings/)**
Choosing the right wealth advisor is a major decision. Let’s discuss your financial goals and see if we’re the right fit for you. **[Book a free consultation today!](https://outlook.office365.com/owa/calendar/IndependentInvestmentAdvisors@mlignw.com/bookings/)**
---
### [Are We the Right Wealth Advisor for You? | Fiduciary Financial Planning in Portland, OR](https://independentadvisorsnw.com/homepage/are-we-the-right-wealth-advisor-for-you/)
**Published:** November 1, 2022
**Author:** Investment Advisor
**Content:**
# Are We the Right Wealth Advisor for You? | Fiduciary Financial Planning in Portland, Oregon
#### **A Personalized, Fiduciary Approach to Your Wealth**
Finding the right financial advisor isn’t just about numbers—it’s about trust, transparency, and a shared vision for your future. At **Independent Investment Advisors**, we specialize in helping **high-net-worth families, technology professionals, business owners, and professionals** in **Portland Metro Area** create financial strategies that grow and protect wealth for generations.
If you’re looking for a **fee-only fiduciary advisor** with a **holistic, personalized approach**, please read on!
## **Who We Work Best With**
We are an ideal fit for clients who:
✅ **Value a Fiduciary Relationship** – We act solely in your best interest, providing **unbiased financial guidance** without hidden fees or commissions.
✅ **Are Busy Executives, Technology Professionals Professionals or Business Owners** – You’re focused on your career, business, or family and need **a trusted partner to manage your wealth efficiently**.
✅ **Want a Proactive, Tax-Efficient Strategy** – We integrate **investment management, tax planning, estate strategies, and risk management** to maximize your financial success.
✅ **Have $1M+ in Investable Assets** – Our approach is tailored for individuals and families with complex financial situations that require expert coordination.
✅ **Are Preparing for Retirement or a Major Life Transition** – Whether you’re **retiring, selling a business, or receiving an inheritance**, we help you **navigate financial decisions with confidence**.
## **Why Choose Independent Investment Advisors?**
### **1. A Boutique Experience with National Expertise**
Unlike large firms that treat clients as account numbers, we take the **time to understand your goals, values, and unique financial complexities**. You’ll always work with an experienced advisor—not be passed off to a junior representative.
### **2. Integrated Tax and Investment Planning**
Most advisors focus solely on investments. We go beyond that by incorporating **proactive tax strategies, estate planning, and risk management** to ensure you keep more of what you earn.
### **3. Fee-Only, No Commissions, No Hidden Costs**
We are a **fee-only fiduciary**, meaning we **don’t receive commissions from financial products**. Our only priority is **your best financial outcome**.
### **4. A Long-Term Partnership**
We believe in **building lifelong relationships** with our clients, regularly adjusting financial strategies as life evolves. You’ll receive **ongoing, proactive advice** tailored to your changing needs.
### **5. Based in Portland, Oregon, Serving Clients Nationwide**
Though we are based in Portland, Oregon we work with clients **locally and across the country** via **virtual meetings and secure digital financial tools**.
## **Our Services: Comprehensive Wealth Management**
🔹 **Investment Management** – Custom portfolio strategies aligned with your long-term goals.
🔹 **Tax Planning & Optimization** – Reduce tax liabilities with strategic planning.
🔹 **Retirement Planning** – Create a reliable **income strategy for retirement security**.
🔹 **Estate & Legacy Planning** – Ensure your wealth is protected and passed on as intended.
🔹 **Risk Management & Asset Protection** – Safeguard your financial future from unexpected risks.
## **How to Get Started**
🔹 **Step 1:** Schedule a free, no-obligation consultation.
🔹 **Step 2:** We’ll discuss your financial situation, goals, and whether we’re the right fit.
🔹 **Step 3:** If we’re a match, we’ll create a **custom financial strategy** tailored to your needs.
📞 **Call us at 971-350-8068** or **[Schedule a Consultation](https://outlook.office365.com/owa/calendar/IndependentInvestmentAdvisors@mlignw.com/bookings/)**
### **Still Unsure? Let’s Talk.**
Choosing the right wealth advisor is a major decision. We invite you to **schedule a free consultation** to see if our approach aligns with your financial needs.
👉 **Click [Here ](https://outlook.office365.com/owa/calendar/IndependentInvestmentAdvisors@mlignw.com/bookings/)to Book a Free Consultation**
---
### [Financial Investment Solutions for Small Business Owners](https://independentadvisorsnw.com/solutions/financial-investment-solutions-for-small-business-owners/)
**Published:** September 15, 2020
**Author:** Investment Advisor
**Content:**
## Financial Planning and Investment Management Solutions for Small Business Owners
If you are a small business owner, you have substantially different financial investment needs. Many of our clients are small business owners. Working together over the years, we have developed a wide range of financial investment solutions specifically focused on a small business owner. We work together with your accountants, tax, and legal advisors throughout the year to maximize returns, reduce risk, and reduce tax liabilities as appropriate. It’s a very different engagement and relationship compared to an individual or family financial investment planning. In some cases, we can also work with your employees on retirement planning.
Small Business Financial Investment Solutions
## Small Business Owner Retirement Planning
More often than not, our retirement planning conversation with small business owner starts with a sensitive debate. Many small business owner clients don’t believe or don’t recognize they need a standalone individual retirement plan separate from their business. They look at their business as a source of their income and a future source of their retirement. While we sincerely hope the future will bring just that it’s not a prudent [financial planning](https://independentadvisorsnw.com/homepage/education/top-ten-financial-planning-tips-for-business-owners/) practice. It’s highly recommended that small business owners establish a separate from their business individual retirement plan and investment account. They can immediately take advantage of tax deferral, reducing their annual tax liability while also protecting that asset from business liability.
## Money Management of Business Operating Cash
Another significant difference between small business owner’s financial investment needs and general individuals or family’s investment needs is the need to manage business operating cash. Over the years, we have developed a portfolio program that allows business owners to earn a higher interest return on their operating cash while keeping their funds available.
## General Investment Portfolio Management
Many of our small business owner clients have been fortunate not only to earn a great living in their small business but also to build up a savings account. Many of them want those savings accounts to grow at a higher rate but with reduced risk and a short-term investment view. They want growth, but they also want to be able to use the funds for their lifestyle. For this reason, we created a defined or structured outcome portfolio program. We use index ETF’s and derivatives, more specific options, to reduce risk while providing portfolio growth.
There are several retirement plans available to small business owners and their employees. Some of them are listed below. We work with our clients and their other advisors (accountants, tax, legal) to identify and establish the best plan.
### Traditional and Roth IRAs
The Individual Retirement Account (IRA) and Roth IRA are both forms of qualified accounts. They each carry valuable tax benefits, with the primary difference being when the tax benefit is available to you. You contribute to the Roth with after-tax dollars, meaning you have already paid the taxes upfront. As such, the Roth IRA allows a month to grow TAX-FREE with TAX-FREE withdraws. With the traditional IRA, you are contributing to the account pre-tax. Therefore, your retirement benefits are subject to taxation when you begin to collect them.
### SIMPLE IRA
SIMPLE IRA is defined as a Savings Incentive Match Plan for Employees. It is essentially a company-sponsored plan, in the same way, that a 401(k) is. SIMPLE IRA allows you to contribute on a pre-tax basis considerably more to what your standard allowance is.
### SEP IRA
The Simplified Employee Pension or SEP IRA is a plan that allows employers to contribute to a traditional IRA set up by the employer for themselves and their employees. Similar to SIMPLE IRA, the program will enable you to contribute on a pre-tax basis considerably more to what your standard allowance is. It’s also very flexible as SEP IRA allows an employer to skip contributions during down years. If the business isn’t doing as well for whatever reason.
### The Simple 401(k)
In essence, it’s a mashup of the savings incentive match plan for employees and the regular 401(k). They’ve taken some critical elements of both and created this hybrid type of retirement account. Similar to the other programs, it will enable you to contribute on a pre-tax basis considerably more to what your standard allowance is. It also allows the owner and the employees to contribute individually and create even more considerable tax-deferred earnings.
---
### [How to Choose a Financial Advisor](https://independentadvisorsnw.com/homepage/education/how-to-choose-a-financial-advisor/)
**Published:** August 16, 2021
**Author:** Financial Planner
**Content:**
[< back to Investor Education Center](https://independentadvisorsnw.com/homepage/education/)
Choosing a financial advisor is a major life decision that can determine your financial trajectory for years to come.
A 2020 Northwestern Mutual study found that 71% of U.S. adults admit their [financial planning](https://independentadvisorsnw.com/homepage/education/top-ten-financial-planning-tips-for-business-owners/) needs improvement. However, only 29% of Americans work with a financial advisor.1
The value of working with a financial advisor varies by person and advisors are legally prohibited from promising returns, but research suggests people who work with a financial advisor feel more at ease about their finances and could end up with about 15% more money to spend in retirement.6
A recent Vanguard study found that, on average, a $500K investment would grow to over $3.4 million under the care of an advisor over 25 years, whereas the expected value from self-management would be $1.69 million, or 50% less. In other words, an advisor-managed portfolio would average 8% annualized growth over a 25-year period, compared to 5% from a self-managed portfolio.7
Vanguard study found that on average a $500K investment would grow to over $34 million under the care of an advisor over 25 years whereas the expected value from self management would be $169 million or 50 less### Always Hire an Advisor Who Is a Fiduciary
By definition, a fiduciary is an individual who is ethically bound to act in another person’s best interest. This obligation eliminates conflict of interest concerns and makes an advisor’s advice more trustworthy.
### Don’t Hire the First Advisor You Meet
While it’s tempting to hire the advisor closest to home or the first advisor in the yellow pages, this decision requires more time. Take the time to interview at least a few advisors before picking the best match for you.
### Don’t Choose an Advisor with the Wrong Specialty
Some financial advisors specialize in retirement planning, while others are best for [business owners](https://independentadvisorsnw.com/homepage/education/business-owner-exit-planning/) or those with a high net worth. Some might be best for young professionals starting a family. Be sure to understand an advisor’s strengths and weaknesses – before signing the dotted line.
### Don’t Pick an Advisor With an Incompatible Strategy
Each advisor has a unique strategy. Some advisors may suggest aggressive investments, while others are more conservative. If you prefer to go all in on stocks, an advisor that prefers bonds and index funds is not a great match for your style.
### Always Ask About Credentials
To give investment advice, financial advisors are required to pass a test. Ask your advisor about their licenses, tests, and credentials. Financial advisors tests include the Series 7, and Series 66 or Series 65. Some advisors go a step further and become a Certified Financial Planner, or CFP.
### Understand How They are Paid
Some advisors are “fee only” and charge you a flat rate no matter what. Others charge a percentage of your assets under management. Some advisors are paid commissions by mutual funds, a serious conflict of interest. If the advisor earns more by ignoring your best interests, do not hire them.
Sources:
1\. Northwestern Mutual study
2\. Value of a Gamma-Efficient Portfolio (2017), Morningstar Investment Management.
3\. The Return on Advice (2016), Envestnet, Capital Sigma.
4\. Value of a Financial Advisor Study (2017), Russell Investments.
5\. Advisor Value (2014), Voya Retirement Research Institute.
6\. Journal of Retirement Study
7\. Vanguard (2019), Putting a Value on Your Value
---
### [Economic Correlation: Cyclical and Non-Cyclical Stocks](https://independentadvisorsnw.com/homepage/education/economic-correlation-cyclical-and-non-cyclical-stocks/)
**Published:** September 30, 2020
**Author:** Investment Advisor
**Content:**
[< back to Investor Education Center](https://independentadvisorsnw.com/homepage/education/)
# **Economic Correlation Cyclical and Non-Cyclical Stocks**
A rising tide might lift all boats, but the same cannot be said for the economy.
When the U.S. experiences robust economic growth, specific stock market sectors tend to rise while others hold steady or even decline by comparison. The stocks of companies that experience higher revenues are typically categorized as cyclical. In other words, their good fortune rests mainly on consumers being gainfully employed and having ample discretionary income with which to buy more goods and services.
Take, for example, auto manufacturers. Sales typically increase when more people can afford to buy a new car. But that’s not all the time, because the economy is cyclical – it ebbs and flows over time. Therefore, companies that produce non-essential products – sometimes referred to as consumer discretionary goods and services – tend to flourish during economic cycles of strength and rising GDP. That is why they are called cyclical stocks.
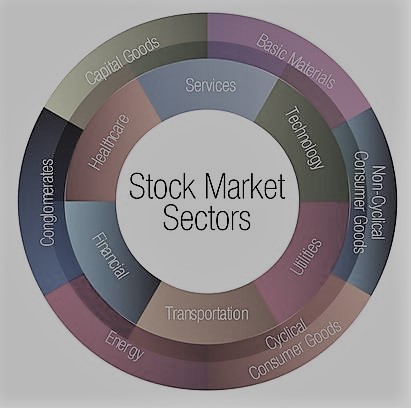Economic Correlation of Cyclical and Non-Cyclical Stocks. A rising tide might lift all boats, but the same cannot be said for the economy.
But when the economic future is in decline or uncertain, people tend to delay buying non-essential items like a new car. When the economy takes a nosedive, more consumers are affected, buy less stuff, manufacturing takes a hit, and companies start laying off their workforce.
Despite these unfortunate circumstances, people still have to eat. They buy essential items, such as food and toothpaste and toilet paper. These are considered consumer staples, and the stocks of companies that produce these types of goods are defined as non-cyclical stocks. That’s because those companies are expected to continue earning revenues regardless of economic cycles. Non-cyclical industries include food and beverage, tobacco, household, and personal products.
Another non-cyclical sector is utilities. Utilities are slightly different because people tend to purchase relatively the same amount of utility service – with exceptions for extreme weather or making slight thermostat adjustments to save money – whether the economy is robust or in a downward spiral. Because of this, utility companies are considered a very stable business model.
For investors, that means they are well-established, long-term performers and usually pay out high dividends. Not only are utility stocks a good option for retirees seeking income to supplement their Social Security benefits, but they offer a haven for investors to relocate assets during periods of economic decline.
In light of recent cautions by economists predicting a recession in 2020, this could be an excellent time to [review your portfolio](https://independentadvisorsnw.com/contact-us/portfolio-review-request/) from the perspective of cyclical versus non-cyclical holdings. It doesn’t mean you need to sell completely out of your stock allocation; perhaps temper your holdings to equities that tend to perform reliably regardless of the economy. Besides consumer staples and utilities, consider companies that specialize in national defense, waste management, data processing, and payments.
Also, be aware that the past three decades have boasted several of the longest-running economic expansions in U.S. history (1991 to 2001; 2001 to early 2007; 2009 through 2019). This tells us that U.S. economic growth cycles appear to be lengthening while declines are relatively shorter and followed up with impressive recovery periods.
So, take heart. If you decide to transfer some of your assets to less flashy, non-cyclical securities, you might not have to leave them there for long. However, it’s always a good idea to maintain a diversified portfolio, so you don’t have to make adjustments based on economic cycles. And as always, consult an investment professional to help you make these important decisions.
---
### [Guide to recessions: 9 key things you need to know!](https://independentadvisorsnw.com/homepage/education/guide-to-recessions/)
**Published:** September 23, 2022
**Author:** Investment Advisor
**Content:**
[< back to Investor Education Center](https://independentadvisorsnw.com/homepage/education/)
# Guide to recessions: 9 key things you need to know!
*Here is some great research put together by some very smart people! Provided to our community by the curtesy of one of our partners: Capital Group.*
## How bad will the next recession be?
That’s one of the questions we hear most often, especially now as the Federal Reserve aggressively hikes interest rates to rein in inflation at 40-year highs. It seems clear to us that the U.S. will enter a recession by early 2023, if it hasn’t already. Our expectation is that it will be less damaging than the 2008 global financial crisis, but the full extent of the economic impact won’t be known for some time.
## 3 facts about market recoveries
To help you prepare for these uncertain times, we researched 70 years of data including the last 11 economic downturns to distill our top insights and answer key questions about recessions:
[1. What is a recession?](#What-is-a-recession?)
[2. What causes recessions?](#What-causes-recessions?)
[3. How-long-do-recessions-last?](#How-long-do-recessions-last? "3. How-long-do-recessions-last?")
[4. What happens to the stock market during a recession?](#What-happens-to-the-stock-market-during-a-recession?)
[5. What economic indicators can warn of a recession?](#What-economic-indicators-can-warn-of-a-recession? "5. What economic indicators can warn of a recession?")
[6. Are we in a recession?](#Are-we-in-a-recession?)
[7. How should you position your stock portfolio for a recession?](#How-should-you-position-your-stock-portfolio-for-a-recession?)
[8. How should you position your bond portfolio for a recession?](#How-should-you-position-your-bond-portfolio-for-a-recession?)
[9. What should you do to prepare for a recession?](#What-should-you-do-to-prepare-for-a-recession?)
## 1. What is a recession?
A recession is commonly defined as at least two consecutive quarters of declining GDP (gross domestic product) after a period of growth, although that isn’t enough on its own. The National Bureau of Economic Research (NBER), which is responsible for business cycle dating, defines recessions as “a significant decline in economic activity spread across the economy, lasting more than a few months, normally visible in real GDP, real income, employment, industrial production and wholesale-retail sales.” In this guide, we will use NBER’s official dates.
## 2. What causes recessions?
Past recessions have occurred for many reasons, but typically are the result of economic imbalances that, ultimately, need to be corrected. For example, the 2008 recession was caused by excess debt in the housing market, while the 2001 contraction was caused by an asset bubble in technology stocks. An unexpected shock such as the COVID-19 pandemic, widespread enough to damage corporate profits and trigger job cuts, also can be responsible.
When unemployment rises, consumers typically reduce spending, which further pressures economic growth, company earnings and stock prices. These factors can fuel a vicious cycle that topples an economy. Although they can be painful to live through, recessions are a natural and necessary means of clearing out excesses before the next economic expansion.
As Capital Group vice chair Rob Lovelace recently noted, “You can’t have such a sustained period of growth without an occasional downturn to balance things out. It’s normal. It’s expected. It’s healthy.”
## 3. How long do recessions last?
Recessions are painful, but expansions have been powerful!
Sources Capital Group National Bureau of Economic Research Refinitiv Datastream Chart data is latest available as of 83122 and shown on a logarithmic scale The expansion that began in 2020 is still considered current as of 83122 and is not included in the average expansion summary statistics Since NBER announces recession start and end months rather than exact dates we have used month end dates as a proxy for calculations of jobs added Nearest quarter end values used for GDP growth ratesThe good news is that recessions generally haven’t lasted very long. Our analysis of 11 cycles since 1950 shows that recessions have persisted between two and 18 months, with the average spanning about 10 months. For those directly affected by job loss or business closures, that can feel like an eternity. But investors with a long-term investment horizon would be better served looking at the full picture.
Recessions have been relatively small blips in economic history. Over the last 70 years, the U.S. has been in an official recession less than 15% of all months. Moreover, their net economic impact has been relatively small. The average expansion increased economic output by almost 25%, whereas the average recession reduced GDP by 2.5%. Equity returns can even be positive over the full length of a contraction since some of the strongest stock rallies have occurred during the late stages of a recession.
## 4. What happens to the stock market during a recession?
The exact timing of a recession is hard to predict, but it’s still wise to think about how one could affect your portfolio. Bear markets (market declines of 20% or more) and recessions (economic declines) have often overlapped — with equities leading the economic cycle by six to seven months on the way down and again on the way up.
Equities have typically peaked months before a recession, but can bounce back quickly!
Sources Capital Group Federal Reserve Board Haver Analytics National Bureau of Economic Research Standard Poors Data reflects the average change in the SP 500 Index and economic activity using industrial production as a proxy of all completed economic cycles from 1950 to 2021 The cycle peak refers to the highest level of economic activity in each cycle before the economy begins to contract Both lines are indexed to 100 at each economic cycle peak and also indexed to 0 months beforeafter cycle peak on the x axis A negative number left of the cycle peak reflects the average change in each line in the months leading up to the cycle peak The positive numbers right of the cycle peak indicate the average changes after the cycle peakStill, aggressive market-timing moves, such as shifting an entire portfolio into cash, can backfire. Some of the strongest returns can occur during the late stages of an economic cycle or immediately after a market bottom. A dollar cost averaging strategy, in which investors systematically invest equal amounts at regular intervals, can be beneficial in down markets. This approach can allow investors to purchase more shares at lower prices while remaining positioned for when the market eventually rebounds.
## 5. What economic indicators can warn of a recession?
Wouldn’t it be great to know ahead of time when a recession is coming? Despite the impossibility of pinpointing the exact start of a recession, there are some generally reliable signals worth watching closely in a late-cycle economy.
Source Capital Group Reflects latest data available as of 83122Many factors can contribute to a recession, and the main causes often change. Therefore, it’s helpful to look at several different aspects of the economy to better assess where excesses and imbalances may be building. Keep in mind that any indicator should be viewed more as a mile marker than a distance-to-destination sign.
Four examples of economic indicators that can warn of a recession include the yield curve, unemployment rate, consumer sentiment and housing starts. Aggregated metrics, such as The Conference Board Leading Economic Index® (LEI), which combines 10 different economic and financial signals into a single analytic system to predict peaks and troughs, have also been consistently reliable over time.
These factors suggest the U.S. is in a late part of the economic cycle and moving closer to a recession, even as the labor market remains relatively resilient. New economic data can quickly change the story though.
## 6. Are we in a recession?
Although it may feel like we’re already in one, we believe an official recession is still unlikely until later this year or early 2023. Despite the impact that high inflation has had on consumer sentiment and corporate earnings, a strong labor market continues to support the economy in the near term.
The likelihood of a recession rose sharply in recent months.
Sources Federal Reserve Bank of New York Refnitiv Datastream As of 83122 Shaded bars represent US recessions as defined by the National Bureau of Economic ResearchThe exact timing will likely depend on the pace and magnitude of the Fed’s moves. It is hard to see a clear path to bring inflation back to the Fed’s 2% target without pushing the economy into recession. In our view, the only way to break the spiral of escalating wages and prices is to create a lot of slack in the labor market. The unemployment rate may need to rise to at least 5% or 6% before wage growth starts to moderate. We believe this will make a recession very difficult to avoid by 2023.
Geopolitical shocks — such as an escalation in the war in Ukraine — or the consequences of a recession overseas are even harder to predict but could quicken the timeline for a U.S. recession.
## 7. How should you position your stock portfolio for a recession?
We’ve already established that equities often do poorly during recessions but trying to time the market by selling stocks is not suggested. So should investors do nothing? Certainly not.
To prepare, investors should take the opportunity to review their overall asset allocation, which may have changed significantly during the bull market, to ensure their portfolio is balanced and diversified. Consulting a financial advisor can help immensely since these can be emotional decisions for many investors.
Through 10 declines, some sectors have finished above the overall market!
\*In September 2018, the telecommunication services sector was renamed communication services, and its company composition was materially changed. The dividend yield shown is for the telecommunication services industry group, a subset of the newly constructed communication services sector. Sources: Capital Group, FactSet. Includes the last 10 periods that the S&P 500 Index declined by more than 15% on a total return basis. Sector returns for 1987 are equally weighted, using index constituents from 1989, the earliest available data set. The 2022 bear market is still considered current as of 8/31/22 and is included in this analysis. Dividend yields are as of 8/31/22.Not all [stocks respond the same during periods of economic](https://independentadvisorsnw.com/homepage/education/economic-correlation-cyclical-and-non-cyclical-stocks/) stress. In the 10 largest equity declines between 1987 and August 2022, some sectors held up more consistently than others — usually those with higher dividends such as consumer staples and utilities. Dividends can offer steady return potential when stock prices are broadly declining.
Growth-oriented stocks can still have a place in portfolios, but investors may want to consider companies with strong balance sheets, consistent cash flows and long growth runways that can withstand short-term volatility.
Even in a recession, many companies may remain profitable. Focus on companies with products and services that people will continue to use every day such as telecom, utilities and food manufacturers with pricing power.
## 8. How should you position your bond portfolio for a recession?
Fixed income is often key to successful investing during a recession or bear market. That’s because bonds can provide an essential measure of stability and capital preservation, especially when equity markets are volatile.
The market selloff in the first half of 2022 was unique in that many bonds did not play their typical safe-haven role. But in the seven previous market corrections, bonds — as measured by the Bloomberg U.S. Aggregate Index — rose four times and never declined more than 1%.
High-quality bonds have shown resilience when stock markets are unsettled.
Sources Bloomberg Index Services Ltd RIMES Standard Poors Dates shown for market corrections are based on price declines of 10 or more without dividends reinvested in the SP 500 with at least 50 recovery persisting for more than one business day between declines Includes all completed corrections between 1110 and 83122 Returns are based on total returns in USD Past results are not predictive of results in future periodsAchieving the right fixed income allocation is always important. But with the U.S. economy entering a period of uncertainty, it’s especially critical for investors to focus on core bond holdings that can provide balance to portfolios. Investors don’t necessarily need to increase their bond allocation ahead of a recession, but they should review their fixed income exposure with their financial professionals to be sure it is positioned to provide diversification from equities, income, capital preservation and inflation protection — what we consider the four key roles fixed income can play in a well-diversified portfolio.
## 9. What should you do to prepare for a recession?
Above all else, investors should stay calm when investing ahead of and during a recession. Emotions can be one of the biggest roadblocks to strong investment returns, and this is particularly true during periods of economic and market stress.
If you’ve picked up anything from reading this guide, it’s probably that determining the exact start or end date of a recession is not only impossible, but also not that critical. What is more important is to maintain a long-term perspective and make sure your portfolio is designed to be balanced enough to benefit from periods of potential growth before it happens, while being resilient during those inevitable periods of volatility.
Jared Franz is an economist with 16 years of industry experience (as of 12/31/21). He holds a PhD in economics from the University of Illinois at Chicago and a bachelor’s degree in mathematics from Northwestern University.
Darrell R. Spence covers the United States as an economist and has 29 years of industry experience (as of 12/31/2021). He holds a bachelor’s degree in economics from Occidental College. He also holds the Chartered Financial Analyst® designation and is a member of the National Association for Business Economics.
---
### [Advisor Q&A: How to guide to tax optimized investing.](https://independentadvisorsnw.com/homepage/education/advisor-qa-how-to-guide-to-tax-optimized-investing/)
**Published:** January 12, 2024
**Author:** Investment Advisor
**Content:**
[< back to Investor Education Center](https://independentadvisorsnw.com/homepage/education_2/)

# Advisor Q&A: How to guide to tax optimized investing.
In the complex landscape of financial planning, mastering the art of tax-efficient investing is crucial for optimizing wealth accumulation and achieving long-term financial goals. This comprehensive guide, ‘Advisor Q&A: Tax-Efficient Investing,’ brings together expert insights and actionable advice to empower individuals and businesses with the knowledge to navigate the intersection of [tax strategies,](https://independentadvisorsnw.com/homepage/education/tax-optimization-strategies-for-high-earners/) retirement planning, and investment decisions. From understanding the enduring benefits of tax efficiency to exploring investment options aligned with social responsibility goals, this guide serves as a valuable resource for those seeking to maximize returns while minimizing tax liabilities. Join us on a journey through key concepts, strategies, and considerations, as we unravel the intricacies of tax-efficient investing in the ever-evolving financial landscape.
It’s important to note that tax planning is complex, and the impact of changes in tax laws can vary based on individual circumstances. Nothing in this guide should be construed as financial or investment advice. The guide has been written as though-provoking education tool only. Consulting with professionals who have expertise in tax planning and financial management is crucial to making informed decisions.
**[How do tax-deductible strategies specifically aid in retirement and investment planning?](https://independentadvisorsnw.com/advisor-qa-how-to-guide-to-tax-optimized-investing-tax-deductible-strategies/)**
**[Can you discuss investment options that offer both retirement benefits and tax advantages?](https://independentadvisorsnw.com/advisor-qa-how-to-guide-to-tax-optimized-investing-investment-options-that-offer-both-retirement-benefits-and-tax-advantages/)**
**[How do tax-deferred and tax-exempt investments differ, especially in the context of retirement planning?](https://independentadvisorsnw.com/advisor-qa-how-to-guide-to-tax-optimized-investing-tax-deferred-and-tax-exempt-investments/)**
**[What should investors consider when selecting tax-advantaged retirement and investment options?](https://independentadvisorsnw.com/advisor-qa-how-to-guide-to-tax-optimized-investing-selecting-tax-advantaged-retirement-and-investment-options/)**
**[Could you provide examples of strategies that combine tax efficiency with effective retirement planning?](https://independentadvisorsnw.com/advisor-qa-how-to-guide-to-tax-optimized-investing-examples-of-strategies-that-combine-tax-efficiency-with-effective-retirement-planning/)**
**[How does diversification in a portfolio support tax efficiency in retirement and investment strategies?](https://independentadvisorsnw.com/advisor-qa-how-to-guide-to-tax-optimized-investing-portfolio-tax-efficiency-in-retirement-and-investment-strategies/)**
**[What tax deductions or incentives are available for those planning for retirement and educational expenses?](https://independentadvisorsnw.com/advisor-qa-how-to-guide-to-tax-optimized-investing-tax-deductions-and-incentives/)**
**[What essential information should individuals and businesses understand about tax-advantaged retirement accounts?](https://independentadvisorsnw.com/advisor-qa-how-to-guide-to-tax-optimized-investing-understand-tax-advantaged-retirement-accounts/)**
**[What are the enduring benefits of incorporating tax-efficient methods in retirement and investment portfolios?](https://independentadvisorsnw.com/what-are-the-enduring-benefits-of-incorporating-tax-efficient-methods-in-retirement-and-investment-portfolios/)**
---
### [Brokers vs. Advisors: What's the Difference?](https://independentadvisorsnw.com/homepage/education/brokers-vs-advisors-whats-the-difference/)
**Published:** May 12, 2021
**Author:** Investment Advisor
**Content:**
[< back to Investor Education Center](https://independentadvisorsnw.com/homepage/education_2/)
# Brokers vs. Advisors: What’s the Difference?
Text below is an article published by Us News in March of 2021. The original article can be found here:
[https://money.usnews.com/financial-advisors/articles/brokers-vs-advisors-whats-the-difference-and-do-you-need-both?src=usn\_nl\_financialadvisors](https://money.usnews.com/financial-advisors/articles/brokers-vs-advisors-whats-the-difference-and-do-you-need-both?src=usn_nl_financialadvisors)
Although they may appear the same, brokers and advisors provide different services.
While brokers and advisors may fill similar roles in a client’s life, the services they offer and fees they charge can vary greatly.
Although they may appear the same brokers and advisors provide different services“It’s always a good idea to do some of your own due diligence before hiring a professional, whether that’s looking up a broker through your Better Business Bureau, running a broker check or checking on (Financial Industry Regulatory Authority’s) website to see if the advisor has any disclosures,” says David Wright, executive director of practice development at M&O Marketing.
Wright says you can usually tell whether a professional is a broker or advisor, or a combination of the two, by the disclosures at the bottom of their website. If the person is an advisor, you can also find a Form ADV, which will tell you the products and types of financial planning the advisor specializes in, on their website or available for free from the Investment Adviser Public Disclosure database, sponsored by the U.S. Securities and Exchange Commission.
## Financial Advisor vs. Broker
The difference between financial advisors and brokers comes down to the services they provide and how they’re paid for those services. “A broker earns a commission on the sale of some type of investment, and a financial advisor earns money by giving people advice on their money,” says Mazi Bahadori, vice president of securities at Altruist. In other words: Financial advisors advise, and brokers sell.
In technical terms, a broker is a specific designation that refers to someone who is licensed by the Financial Industry Regulatory Authority, called FINRA, to buy or sell securities, says Mark Schrader, a financial planning strategist at TIAA. The title of financial advisor is murkier as there is no legal requirement that must be met to call yourself a financial advisor.
For this reason, Jason Steeno, president of CoreCap Advisors, says it’s always wise to check the background and history of your financial advisor on the Investment Adviser Public Disclosure database and via FINRA’s BrokerCheck.
“Typically, financial advisors need to learn more about you before they can give you advice, whereas brokers just need to collect the bare minimum amount of information before they can conclude that an investment can be sold to you,” Bahadori says. This is because advisors and brokers may be held to different standards.
Brokers must adhere to the suitability standard, which states that an investment or product need only be “suitable” for an investor’s situation. This means a broker could recommend one investment, even if there is a lower cost or better option available, as long as the recommended product is suitable to your needs.
“Brokers are not bad people, and there’s nothing inherently wrong with earning a commission,” Bahadori says. The problem is where their incentives lie.
“Most financial services companies simply incentivize sales and aren’t always interested in delivering the best possible outcome to their clients,” he says. “If you happen to find a broker that bucks that trend, great. But odds are people will do what they get paid to do, and that won’t always bode well for clients.”
Advisors more commonly follow the fiduciary standard, which requires them to act in their clients’ best interests at all times. A fiduciary could never recommend a suitable product if there was a better option available. That said, not all advisors are fiduciaries. Some are only held to the suitability standard, so be sure to ask rather than assume. Others are both advisors and brokers and may wear their advisor hat while helping you develop a financial plan, then put on their broker hat when recommending specific products to use as part of that plan.
“Many firms will have employees titled ‘financial advisors’ who are also licensed brokers, so it can be important to understand the capacity in which the advisor is working,” Schrader says.
Fiduciaries also cannot earn commissions because this may present conflicts of interest. They may be incentivized to put you in the product with the highest commission rather than the best one for your needs. Instead of commissions, advisors typically earn a fee for the advice they give. This can be charged as a flat or hourly fee or a percentage of the assets you have under their management. Someone who is both an advisor and broker may earn both a fee and commissions, however, so be sure to ask how a professional is compensated before hiring him or her.
## Investment Advisor vs. Broker
The key difference between an investment advisor and broker rests on one familiar word: fiduciary, Bahadori says. Unlike financial advisors or brokers who can choose to be a fiduciary or not, investment advisors are obligated, by law, to act as a fiduciary. This means anyone who calls herself an investment advisor must also be a fiduciary working in her clients’ best interests at all times.
Fiduciaries are held to a higher standard of care than brokers because, as fiduciaries, they can make decisions about your portfolio without first getting your permission. For instance, an investment advisor can make trades in your account without calling you. A broker would have to get your express permission to buy or sell a security in your account.
As fiduciaries, investment advisors cannot earn commissions. They are fee-only advisors who are paid a flat or hourly fee or a percentage of assets under management. This latter arrangement is usually 1% to 2% of the assets you hold with them, Steeno says.
“With this arrangement, the client’s interests and the advisor’s interests are more closely aligned,” he says. “When the account value increases, so does the amount the advisor collects, and vice versa.”
Brokers and investment advisors are regulated by different government agencies. Investment advisors fall under the jurisdiction of the Securities and Exchange Commission, while brokers are regulated by FINRA, says Steve Azoury, financial advisor and owner of Azoury Financial.
They also must pass different licensing exams. A broker is only required to pass the General Securities Representative Exam (Series 7), while an investment advisor must pass the Uniform Investment Adviser Law Examination (Series 65) or a combination of the Series 7 and the Uniform Combined State Law Examination (Series 66).
## Do You Need a Broker and Advisor?
The answer depends on the services you want and how much you’re willing to pay. “If you simply want to buy or sell a stock (or other investment), a broker or discount brokerage may make sense,” Schrader says. “If you have questions about saving for goals and retirement preparedness, you may expand your search to financial advisors who offer a wide range of services.” And if you are looking for someone to help you manage your investments, the best option may be an investment advisor.
Keep in mind that advisors offer more services and can help with more complex financial planning situations, but often come at a higher cost, Azoury says. They also may not be as accessible for investors who are just starting to build their wealth.
“Investment advisors typically have higher account minimums, often starting at $50,000 or more of investable assets,” Steeno says. “Brokers and investment advisors can work with accounts of any size, but with smaller accounts, it’s often hard for advisors to obtain the appropriate amount of diversification” to meet the fiduciary standard of care requirements.
At the same time, he says, he’s seen affluent clients who subscribe to more of a buy-and-hold strategy and prefer to use a broker to minimize fees. “In either case, a client’s needs and level of comfort with the fees being paid relative to the services being provided will help inform which of the two options is the better choice.”
---
### [Hidden 401k Strategies Used by Some Investors](https://independentadvisorsnw.com/homepage/education/hidden-401k-strategies-used-by-some-investors/)
**Published:** September 2, 2021
**Author:** Financial Planner
**Content:**
[< back to Investor Education Center](https://independentadvisorsnw.com/homepage/education/)

[ “Hidden” 401 (k) Strategies Used by Some Investors (14824 downloads )](https://independentadvisorsnw.com/download/1741/?tmstv=1788998122)
Have you ever seen a GROUNDHOG poking its head out of the ground?
What you see is a cute little groundhog poking his head out of his burrow. What you don’t see is the complex web of precisely engineered burrows — hidden from site. These “hidden strategies” are what allow the groundhog to live a comfortable, safe life.
In this guide, you’ll discover why your 401(k) strategy should be “engineered” like a groundhog burrow, because there’s a lot more to it than what you see on the surface.
Most high earners are already leveraging the power of their employer-sponsored 401(k) to save for retirement. They understand the well-publicized advantages: tax deferral, the “free money” provided by the employer match, and the “catch-up” provision after age 50.
However, some investors understand that there is so much more “hidden” beneath the surface of their 401(k) than just the visible benefits.
If you have an employer, you’re most likely planning to max out your 401(k) employee contribution, as well as your employer match. If you’re self-employed, you’re probably figuring out which retirement plan is best for your own business.
Yet when you research more ways to save, you might feel like you’re in the movie Groundhog Day because you find the same advice, over and over.
This special guide is designed to reveal additional “hidden” benefits of your 401(k) account that may help you supercharge your retirement plan.
Whether you’re enrolled in a group plan or considering a solo 401(k) for your business, you’ve come to the right place. Some of the questions you might be asking yourself right now include:
- How can I make the best use of the available investments inside my retirement account?
- How do I coordinate my 401(k) with the rest of my financial plan?
- What more can I be doing to save for retirement?
- Are there more tax-efficient ways of saving and investing my money?
IF THESE STRIKE A CHORD, KEEP READING…
## STRATEGY 1: Supercharge Your Contributions
When it comes to funding your 401(k), the immediate tactic is to maximize your allowable employee contribution. If you’re reading this, you probably already are. Your plan may offer you the ability to contribute either after-tax dollars into a Roth or tax-deductible money into a Traditional 401(k). Your employer match, if available, is always Traditional.
Concealed underneath is the idea that you could potentially add much more to your tax-deferred account. As you may already know, 401(k)s are a type of defined contribution (DC) plan. The annual limit to fund a DC plan for one person (including both employer and employee contributions) is much higher than your employee contribution cap.1
Some plans allow employees to add more retirement money until they reach this limit. If your 401(k) plan allows, you can contribute after-tax dollars to your plan to reach that upper threshold. They’re not tax-deductible, but they do grow tax-free as long as you obey the usual caveats. This strategy is sometimes referred to as a “Mega Backdoor Roth.”
Understanding how and when to supercharge your savings may give you a massive leg up. Critical questions to ask include:
- Am I eligible to supercharge my contributions?
- How can I balance current-year tax savings with my long-range goals?
- How do my 401(k) contributions align with the rest of my financial plan?
- What trade-offs do I need to consider if I want to supercharge my 401(k) account?
## STRATEGY 2: Optimize the Investments in Your 401(k) PLAN
Your plan provider has already given you a standard menu of investments within your 401(k).
Depending on your situation, you may benefit from advanced self-directed strategies that can increase the range of investments available to you, potentially reduce your tax bill, or improve the after-tax return of your overall portfolio.2
For example, if you already have investments that generate a lot of income, shifting them into your retirement account may create a more tax-efficient portfolio.
Though it’s not the right move for everyone, taking control of your 401(k) can potentially help you maximize the benefit of this powerful retirement tool.
Critical questions to ask include:
- Is my 401(k) optimized to fit into my overall investing strategy?
- Do I have the right blend of tax efficiency and portfolio diversification?
- Are there opportunities to better optimize my investments within my 401(k)?
- Does my 401(k) plan allow me to control the investments inside?
- Have I discussed my 401(k) investments with a financial professional?
STRATEGY 3: Make Tax-Efficient Moves For Your 401(K) PLAN
Average investors understand the “surface-level” basics of deciding between Traditional and Roth contributions. However, a “hidden” 401(k) advantage is using both types of tax-deferred accounts to create tax savings now, while generating tax-free income in retirement.
If your plan allows it, you may be able to convert your Traditional 401(k) to a Roth. Done in a tax-coordinated way, you can potentially convert portions of your Traditional account to a Roth without pushing yourself to a higher tax bracket.
When done correctly, these Roth conversion opportunities can potentially help you create more tax-free income in retirement while still getting the benefits of tax savings now.
Critical questions to ask include:
- Can I convert my Traditional 401(k) to a Roth?
- What are the future tax consequences of my existing retirement accounts?
- Should I be “filling up” my tax bracket with taxable events such as Roth conversions that don’t push me into a higher tax bracket?
- Is there a better way to balance tax efficiency now and at my retirement?
BONUS STRATEGY: for Business Owners & the Self-Employed
Entrepreneurs already know that there are plenty of options to create a retirement account. These plans, SEP and SIMPLE IRAs, can be the right answer for some business owners.
However, the solo 401(k) may allow you to set aside more money for retirement.3 You have the opportunity to create a Traditional or Roth account as well as make both employee and employer profit-sharing contributions. You’re also allowed to make solo 401(k) contributions for your spouse, as long as they work in your business.
A 401(k) can potentially turbocharge the retirement income your business generates.
Please click [here](https://independentadvisorsnw.com/solutions/financial-investment-solutions-for-small-business-owners/) for our small business owner specialty solutions page.
Critical questions to ask include:
- What kind of contributions do I plan to make to my retirement account?
- Have I discussed coordinating plans with my spouse who also works in my company?
- Do I understand the pros and cons of the various self-employment retirement plans available to me?
- How do I fit such a retirement plan into my overall financial plan?
- What is my best option to potentially maximize tax efficiency now and in the future?
You’re a high earner with a bright future. Which makes it important for you to understand what’s concealed beneath the surface of your 401(k), so you can make the most of your opportunities. You need to not only make smart choices for your investments, but also consider all the ways your retirement portfolio can be tax efficient today as well as tomorrow.
Whether you work for an employer or you’re designing the retirement plan for your own business, you can use the hidden advantages of your 401(k) to supercharge your savings for the future.
Want to take charge of your retirement? Are you knowledgeable enough to understand you need to go beyond the obvious? Contact us to set up your personal Hidden Opportunities Session to find out how you can potentially maximize all the advantages of your 401(k) retirement plan.
We can help you identify and leverage the hidden opportunities in your 401(k) to potentially boost your savings and save on taxes now and in the future.
At the moment, you’re still ahead of the game. You’re currently planning for your retirement and using what you already know about the benefits of a 401(k) plan. But now you’re poised to go deeper beneath the surface to discover how smart investors make the most of their available opportunities.
**Independent Investment Advisors**
(971) 350-8068
[www.independentadvisorsnw.com](https://independentadvisorsnw.com)
Sources:
1 –
2 –
3 –
Risk Disclosure: Investing involves risk including the potential loss of principal. No investment strategy can guarantee a profit or protect against loss in periods of declining values. Past performance does not guarantee future results. This material is for information purposes only and is not intended as an offer or solicitation with respect to the purchase or sale of any security. The content is developed from sources believed to be providing accurate information; no warranty, expressed or implied, is made regarding accuracy, adequacy, completeness, legality, reliability or usefulness of any information. Consult your financial professional before making any investment decision. For illustrative use only. Neither the named representative nor the named firm gives tax, accounting, or legal advice. This material is for information purposes only and is not intended as an offer or solicitation with respect to the purchase or sale of any security. The content is developed from sources believed to be providing accurate information; no warranty, expressed or implied, is made regarding accuracy, adequacy, completeness, legality, reliability or usefulness of any information. Consult your financial professional before making any investment decision. For illustrative use only. This information is not intended to be a substitute for specific individualized tax advice. We suggest that you discuss your specific situation with a qualified tax professional.
---
### [Facing Early Retirement Decision?](https://independentadvisorsnw.com/homepage/education/facing-early-retirement-decision/)
**Published:** September 2, 2021
**Author:** Financial Planner
**Content:**
[< back to Investor Education Center](https://independentadvisorsnw.com/homepage/education/)

[ Are You Facing Early Retirement? (3601 downloads )](https://independentadvisorsnw.com/download/1731/?tmstv=1788998122)
You weren’t planning on making retirement decisions so soon. You thought you had years to go before you entered the critical transition period, where the choices you make now set the stage for the next 30 years of your life. But the timer is ticking. You’ve got to make good decisions, fast. Most folks at this crossroads have arrived from three paths. Which one is yours?
You’ve been let go from your former employer. With experience comes wisdom— and often more expensive benefits that the firm no longer wants to pay. Can you afford to retire on what you have saved?
You’ve been offered a retirement buyout. It’s tempting, but is it the best deal for you? Will the package explode your plans down the road? What do you need to know to make the best decision?
You were dedicated to your career and loved your job for years and years … until now. You’re not sure if the hours are worth it anymore, but you don’t know if early retirement is the right move. Would it be better in the long term if you continued until full retirement age, even though you must make personal sacrifices to do so?
Whether your employer dropped the bombshell on you or not, you’re suddenly at a crossroads you didn’t expect. You need to evaluate your options speedily while sweeping up all the information you need to head in the right direction.
This timely guide is designed to help you quickly make good decisions about your future and discover whether you can afford to “cut the wires” that connect you to the workforce.
Questions you might be asking yourself include:
- What do I need to know to decide whether I can retire early?
- Is my financial situation stable enough to last throughout my lifetime (as well as my spouse’s)?
- Will I need to continue to work after my “retirement”?
- How will my family react to me no longer working?
- What resources can I count on to help me with this situation?
IF THESE QUESTIONS RESONATE WITH YOU, KEEP READING…
## QUESTION #1: Do I have enough money to retire?
Leaving the workforce can be a difficult transition for anyone, even without a short fuse on your retirement countdown. Throughout your life you’ve brought in a regular income and added to your investment assets. Now you’re facing the critical transition from income generation to drawing down your savings to fund your expenses.
If you’re too young to claim Social Security, you’ll need to create a plan to bridge the income gap until you reach claiming age. If you’re under age 59½ you may be penalized for drawing down retirement accounts (on top of the potential tax bill you’ll owe).

Many people in your situation seriously consider taking another job. But it could be hard to find another position that rewards your experience and work ethic.
Even if you’ve got enough cash on hand to avoid drawing on your investments, you may still want to adjust your investment mix. When you’re on the brink of exiting the workforce, protecting your money from fluctuations in the stock market becomes critical. Preparing your portfolio to ride out bear markets and [recessions is key](https://independentadvisorsnw.com/homepage/education/guide-to-recessions/) when your portfolio is the foundation of your retirement lifestyle.
Critical planning questions to ask include:
- Where will my income come from if I retire?
- How will I change my portfolio to have the right mix of investments?
- Will I face penalties and taxes by starting distributions now?
- How comfortable am I that my portfolio can withstand a recession in the near future?
- Should I ask for advice from someone who has experience in these situations?
## QUESTION #2: Will I be able to sustain my current lifestyle?
You may or may not have a detailed understanding of your current household expenses. Developing even a general understanding of your budget now will help avoid problems later. If you make adjustments quickly enough, you may have a better chance of a comfortable early retirement.
If you’re in the position of being able to choose early retirement instead of having it thrust upon you, the cost of quitting or taking a buyout package may not be immediately clear. It’s important to evaluate the tradeoffs between a work-free life you enjoy and the cost of cutting back on expenses.
Don’t forget to consider “hidden” costs that can sabotage your golden years. You could end up caring for elderly parents and having your buying power eroded by inflation, for example.1 Get the information you need quickly, and make sure you’re not missing anything required for a good decision.
Critical planning questions to ask include:
- What are my annual expenses?
- What expenses will vanish when I’m not working?
- Is what I’ve accumulated so far enough to cover my lifestyle?
- Will I need to take another job?
- Who can help me address the unknowns in my plan?
## QUESTION #3: What do I need to know about health care when my employer plan no longer covers my family and me?
Aside from your employer, you may be eligible to get coverage through state exchanges or COBRA.2 Right now it might not be clear how extensive or expensive these alternatives are, though they’re likely to cost more than your employer coverage.
Health care and related costs could wreck your financial plan if not carefully planned for. You’re generally not eligible for Medicare until age 65, and even then you may face additional costs for supplemental insurance and long-term care.
If you were offered a retirement buyout, your employer may provide health care coverage for a period of time after you leave. You’ll need to determine if it’s enough to cover you until you reach Medicare eligibility.

It’s critical to maintain health insurance coverage, because health status can make it very difficult to get on a new plan. And such a plan could be much more expensive. Therefore you must figure out your best course of action quickly, before you lose coverage.
Critical planning questions to ask include:
- What happens to my healthcare when I leave my employer?
- Do I have a plan to cover the health needs for my family?
- Is long-term care insurance appropriate for me?
- Is there someone who can provide good advice on paying for medical costs in retirement?
## BONUS: How do I evaluate my early retirement package?
Extremely tempted to take the money and run? You’ll want to be sure your decision won’t blow up in your face later. The package must provide enough funding and benefits for you and your family so your money lasts through retirement.
The viability of the package doesn’t just depend on the lump sum payment typically offered. Benefits that work for someone who’s five years away from being able to claim Social Security might not be right for someone ten years away.
Other confirmed job prospects are an additional factor in your decision. It could be a no-brainer if you’ve got potential employment offers already lined up. But if you don’t, the package may not be enough to finance your exit.
Conversely, your current employer’s financial health and ongoing prospects are also considerations. If you don’t take the early retirement package, the next bombshell could be a pink slip. If the company isn’t in good financial shape, they may not be able to pay everything they owe you when you need it.
Critical planning questions to ask include:
- What are the trade-offs I’ll be making by taking vs. not taking the buyout offer?
- Do I feel reasonably certain I’ll be able to find another job right away, and do I want to?
- Will this package be enough to finance my early retirement? Am I asking the right questions?
Defuse Your Early Retirement Bombshell and Create a Clear Path to Your Future
You have a limited amount of time to make critical decisions that will affect your golden years, whether or not you’re leaving on your own terms. You can’t allow too much time to elapse while you consider your options, but you don’t want to leave out any critical factors from the analysis.
You already know it’s important to determine whether your financial situation is stable enough to carry you and your family through retirement. But you don’t know what you don’t know.
You may be deciding whether to take an early retirement package from your employer. Or whether you can stop working because your career is no longer enjoyable. Or what you should do now that you’ve been let go. Whatever your personal situation, it’s imperative to take action soon.
Secure your financial prospects by calling in the bomb squad: a retirement professional who can assist you in making choices that are smart for today and tomorrow. A good place to start defusing potential disaster is by requesting your personalized FREE Retirement Rescue Session.
We can help you figure out if early retirement is right for you from a financial perspective, as well as what you need to know to make that decision. We understand the “known unknowns” in the equation and can help you work through yours.
Seeking advice gives you an opportunity to build a bomb shelter for your financial plan. You’ve already taken a first step toward making wise choices by reviewing this guide and understanding the consequences of your decisions.
Creating your early retirement defense plan begins with the next step, which is to book a call with us for your FREE Retirement Rescue Session. Schedule it now by calling or emailing us to set up your customized consultation.
**Independent Investment Advisors**
(971) 350-8068
[www.independentadvisorsnw.com](https://independentadvisorsnw.com)
1 –
2 –
Risk Disclosure: Investing involves risk including the potential loss of principal. No investment strategy can guarantee a profit or protect against loss in periods of declining values. Past performance does not guarantee future results. This material is for information purposes only and is not intended as an offer or solicitation with respect to the purchase or sale of any security. The content is developed from sources believed to be providing accurate information; no warranty, expressed or implied, is made regarding accuracy, adequacy, completeness, legality, reliability or usefulness of any information. Consult your financial professional before making any investment decision. For illustrative use only. Neither the named representative nor the named firm gives tax, accounting, or legal advice. This material is for information purposes only and is not intended as an offer or solicitation with respect to the purchase or sale of any security. The content is developed from sources believed to be providing accurate information; no warranty, expressed or implied, is made regarding accuracy, adequacy, completeness, legality, reliability or usefulness of any information. Consult your financial professional before making any investment decision. For illustrative use only. This information is not intended to be a substitute for specific individualized tax advice. We suggest that you discuss your specific situation with a qualified tax professional.
---
### [What should I do with my old 401(k) or employer plan](https://independentadvisorsnw.com/homepage/education/what-should-i-do-with-my-old-401k-or-employer-plan/)
**Published:** August 16, 2021
**Author:** Financial Planner
**Content:**
[< back to Investor Education Center](https://independentadvisorsnw.com/homepage/education/)

[ What should I do with my old 401(k) or employer plan? (15379 downloads )](https://independentadvisorsnw.com/download/1703/?tmstv=1788998122)
A clear guide to your options for 401(k), 403(b), and some 457 plans.
(Including how to avoid a surprise tax bill or IRS penalties that could put you in the crosshairs)
When you leave an employer (whether you’re changing jobs or retiring), your retirement plan doesn’t automatically move for you. You must make a critical decision (or risk having that decision made for you in a way that’s better for the company or costs you money). Your employer plan is one of your most valuable retirement assets and deciding where it should go next is a decision with plenty of nuances, pitfalls, and opportunities.
Handle it the right way, and you’ve protected your money’s tax-deferred growth and are in an optimal position for your current and future goals.
Handle it the wrong way, and you’ve given yourself a surprise tax bill, exposed yourself to potential IRS penalties, or robbed yourself of potential future wealth.
If you fall into any of these categories…
- I left my old company and I need to figure out what to do with my old plan
- I’ve got “zombie” plans sitting around and I’ve got questions about what I should do with them
- I’m at or nearing retirement and I need to figure out how to turn my retirement plan into income
You’re in the right place. After you’re done reading this guide, you’ll decide which of these strategies makes the most sense for your old retirement plan and know how to take the next steps that are right for you.
This guide will help you answer questions like:
• What should I do with the retirement plan at my old employer?
• Do I have to move it?
• Where should I put it?
• Will I owe taxes on it if I move it?
• What kind of IRA do I need?
• How do I turn it into retirement income?
Inside, you’ll find:
• Your 5 options for handling old employer plans \[including 401(k)s, 403(b)s, and some 457 plans\]
• The steps you need to follow to execute on each option
• How to avoid accidentally making your retirement account permanently taxable If you’re at or approaching retirement, you’ve got more to consider than just where to move your old plan. You’ll need to decide where your income is coming from, choose when to claim Social Security and Medicare, determine the right order to draw down your accounts, and much more.
**Option 1:** Don’t Touch a Thing If your employer’s plan allows it, you may be able to leave your account where it is, though you won’t be able to continue making contributions to it. However, you’ll be stuck dealing with whatever limited service is offered to ex-employees.
**PROS:** If you retire after age 55, you may not owe a 10% tax penalty on withdrawals. If you own considerable company stock, you might qualify for a favorable tax break (called Net Unrealized Appreciation). You may have access to plan loans. You may qualify for federal creditor protection.
**CONS:** You may end up with a trail of old accounts gathering dust. Not all employers will allow you to leave your plan (it may depend on the size of the balance). Plan fees may increase without your knowledge. You may have limited withdrawal options. Investment options are limited to the standard options currently offered to employees. Your investments may not be [optimized for taxes](https://independentadvisorsnw.com/homepage/education/tax-optimization-strategies-for-high-earners/) or your overall financial goals.
**How to Execute:** Contact your previous plan administrator and ask to leave the plan in place.
**Option 2:** Move it to Your New Employer If you’re still working, a new employer might allow you to simply transfer your old account balance to the plan they offer their employees. Not all employers allow you to do it, but it’s worth asking about.
**PROS:** You’ll have your employer plans in one place. You won’t pay taxes on the distribution if you transfer directly. You’ll have the protections and benefits of the current plan.
**CONS:** Your new employer may not allow you to transfer your old account. You’ll be limited to the investment options offered by the new plan. Many employers will require you to wait to become eligible to enroll in the new plan.
**How to Execute:** Contact the HR department at your new employer and ask them to put you in touch with the plan administrator. If the transfer is possible, they’ll give you instructions on how to complete the move.
**Option 3:** Raid the Piggy Bank (Cash It Out) You have the right to cash out your old employer plan and take a check. This is probably your worst move because the financial repercussions are serious (and permanent).
**PROS:** You’ll get immediate cash.
**CONS:** You’ll owe income taxes on the account value. Your employer may automatically withhold 20% for taxes. You’ll owe penalties if you’re under age 591/2 (unless you qualify for an exemption). You’ll do permanent damage to your long-term goals.
**How to Execute:** Contact your previous plan administrator and ask them to liquidate the account and send you a check.
# “Moving your old plan into an IRA gives you the most control over your money (including advanced ways to optimize your taxes), but there are two basic ways to do it.”
**Option 4:** The Not-So-Simple Indirect IRA Rollover You have the option to take a check from your old plan and roll it over into an IRA within 60 days. Some people like the idea of having a free 60-day loan, but indirect rollovers are fraught with potential (and expensive) mistakes.
**PROS:** You’ll get immediate access to the cash for 60 days. When the rollover is completed, you’ll get the benefits of an IRA, including:
• Access to many investment options
• Tax [optimization strategies](https://independentadvisorsnw.com/homepage/education/tax-optimization-strategies-for-high-earners/) (including Roth conversions, backdoor Roth IRAs, etc.)
• Investment optimization for your overall financial picture
**CONS:** You have to manually take the check and remember to deposit it into your IRA. Indirect rollovers get reported to the IRS. If you fail to roll the funds over within 60 days, you may owe taxes and potential penalties. You risk making your retirement funds fully taxable forever. You risk losing out on any market gains that happen within your rollover window. Your employer may automatically withhold 20% for taxes (and you’ll have to make up the amount from other funds). Your new IRA might have higher fees than the old plan (we can help you evaluate them). While you may be allowed to take penalty-free withdrawals from an employer plan after age 55, you typically can’t withdraw penalty-free from an IRA until age 591/2. Typically, assets in an employer retirement plan have greater protection from creditors than assets held in an IRA. Once you reach age 72, you’ll need to take Required Minimum Distributions (RMDs) from both employer plans and IRAs. However, if you continue to work past age 72, you generally aren’t required to take RMDs from your current employer’s plan.
**How to Execute:** Contact your previous plan administrator and ask them to liquidate the account and send you a check. You’ll have to send the check to your new IRA custodian (and have it deposited) within 60 days, unless you qualify for a limited exemption to the 60-day rule.
**Option 5:** Direct Rollover to an IRA Directly rolling over your account assets to an IRA is a seamless process that avoids all the limits placed on rollovers by the IRS. It gives you all the benefits of your own, personalized IRA without the pitfalls of an indirect rollover.
**PROS:** You’ll get the benefits of an IRA, including:
• Access to many investment options
• Tax [optimization strategies](https://independentadvisorsnw.com/homepage/education/tax-optimization-strategies-for-high-earners/) (including Roth conversions, backdoor Roth IRAs, etc.)
• Investment optimization for your overall financial picture You’ll avoid all potential IRS penalties by never taking “custody” of the money. You won’t owe taxes on the transfer. Your employer won’t withhold any amount from the balance for taxes.
**CONS:** You’ll have to do some paperwork (we can help). Your new IRA might have higher fees than the old plan (we can help you evaluate them). While you may be allowed to take penalty-free withdrawals from an employer plan after age 55, you typically can’t withdraw penalty-free from an IRA until age 591/2. Typically, assets in an employer retirement plan have greater protection from creditors than assets held in an IRA. Once you reach age 72, you’ll need to take Required Minimum Distributions (RMDs) from both employer plans and IRAs. However, if you continue to work past age 72, you generally aren’t required to take RMDs from your current employer’s plan.
**How to Execute:** Contact your previous plan administrator and ask them for a “direct rollover” to your IRA. They’ll give you the next steps they need you to take (such as giving them the name of your new IRA company)
---
### [Cryptocurrency Explained](https://independentadvisorsnw.com/homepage/education/cryptocurrency-explained/)
**Published:** June 25, 2021
**Author:** Investment Advisor
**Content:**
[< back to Investor Education Center](https://independentadvisorsnw.com/homepage/education/)
# CRYPTOCURRENCY EXPLAINED:
## IS IT SIMPLY FooL’s Gold OR ACTUALLY THE REAL DEAL?
Cryptocurrency isn’t the black sheep it once was. It’s hit the mainstream, and it’s grabbing up more headlines and investors than ever before.
These days, about 1 in 7 Americans own some type of cryptocurrency. And a little more than half of them bought it for the first time in 2020.1
Those numbers are likely to climb this year. That’s because more than a quarter of folks say they plan to buy cryptocurrency in the next 12 months.2
With all the headlines, it’s hard to ignore all of the excitement.
And, yet, many also admit they still don’t know all that much about cryptocurrency.3
Do you know the basics?
How much do you really know about cryptocurrency?
Test your knowledge and check out the facts below to see if the cryptocraze lives up to all of the hype — and if it really makes sense for you to jump on the bandwagon.
6 Things Most People Don’t Know About Cryptocurrency
### 1 WHAT IS CRYPTOCURRENCY?
It’s digital or virtual currency created by encoding strings of data (crypto) into units of currency. The feds define it as “a medium of exchange that operates like a currency in some environments but does not have all the attributes of real currency.”4
That means that, unlike the U.S. dollar, cryptocurrencies are not issued by the government. They aren’t regulated by any central authority, and they don’t have a physical form. They are digital, decentralized, and encrypted.
Think of them like virtual tokens or “credits” that you can only use in certain places — and that you can’t necessarily cash out when you want to.
### 2 TOP 3 TYPES OF CRYPTOCURRENCY
Bitcoin (BTC), the first and biggest name in crypto, has dominated the market since its introduction in 2009. It’s prized for its relative resilience and widespread acceptance in the crypto space. That’s why some say it’s the closest option investors have to getting a “blue-chip” cryptocurrency.5
Ethereum (ETH), second only to Bitcoin in market share, is distinctive in that it’s a software platform where users can exchange a cryptocurrency known as “ether.” Although many use the terms “Ethereum” and “ether” interchangeably, Ethereum can be used as a host for other cryptocurrencies. That means investors in Ethereum can benefit from wider uses of the platform, not just ether exchanges.5
Litecoin (LTC), created in 2011, was developed to be the “silver to Bitcoin’s gold.” Using some of Bitcoin’s best features, Litecoin is a less complex cryptocurrency, meaning much shorter transaction confirmation times.
These popular options are just some of the 7,000+ cryptocurrencies that currently exist. Every week new cryptocurrencies are created, and they all have different use cases and goals.5,6
### 3 SHOULD YOU INVEST IN CRYPTOCURRENCY?
That depends. Cryptocurrencies are attractive to folks who like to be on the cutting edge of technology. Certain ones are designed for fast, low-cost, confidential transactions with anyone who has internet access. And their limited supply and freedom from government control gives them hedge-like qualities against inflation and unstable governments. For some, that can make cryptocurrencies a worthwhile option. That doesn’t mean it’s right for you or that you should rush in, however. If you’re considering jumping into cryptocurrency, you need to be aware of its volatility and risks.
### 4 BUYER BEWARE
Cryptocurrencies exist in a “Wild West”–type space. They aren’t regulated, and they aren’t protected by the FDIC or any government body. That makes them ripe for hackers and scammers, who have stolen at least $11 billion in cryptocurrencies since 2011.7 And over half of that has been taken since 2019.8
Sophisticated hackers can hijack accounts, fake new currency offerings, and use other schemes to defraud.9,10 But even simple scams can work with naïve investors or insecure accounts. When they do work, accounts can be drained in minutes, and that cryptocurrency will be lost forever.
### 5 WHAT IS BLOCKCHAIN?
Blockchain is the technology behind cryptocurrency. It’s a network that chains chunks of data (blocks) together to create permanent, time-stamped records of every transaction. This database is stored in a decentralized cryptocurrency network, with peers verifying and recording each transaction. The public record of those transactions is called the blockchain.
This setup provides transparency and traceability. In fact, even though cryptocurrency owners can be anonymous, their digital currency is not. Any time it’s exchanged, it can be tracked, and every historical transaction for cryptocurrency is on record.
Beyond that, the peer verification in blockchain makes reliable transactions possible without a financial institution as a middleman — and outside of government authority and oversight.
These distinctive features of blockchain may not just change the way some industries do business. Some experts say blockchain has the potential to create new economic and social foundations.11
### 6 INDUSTRIES RIPE FOR BLOCKCHAIN DISRUPTION
Art & Collectibles
Blockchain has paved the way for collectible digital assets. Known as non-fungible tokens (NFTs), these virtual tokens can represent anything from sports cards and clips of games to digital artwork, video game memorabilia, and other rarities. Because each NFT is unique, they aren’t interchangeable like other cryptocurrencies. Still, they are a blossoming space where multi-million-dollar transactions are already happening.12
Financial Services
Borders and banks don’t matter for financial transactions that happen through blockchain technology. That’s a game changer in developing countries where billions of people lack access to traditional banks. It also means faster, more transparent, and more efficient money transfers anywhere. Plus, blockchain has the potential to make bank records more secure while creating a real-time ledger and reducing operational costs.13
All of that is why some say that blockchain is poised to revolutionize the financial services industry in the same way the internet fundamentally changed media.14
Health Care
Patient records can be stored more securely, while remaining immediately accessible, through blockchain technology. That alone could save lives in an emergency. Beyond patient data, however, blockchain could solve other big problems in the health care industry, like managing drug supply chains, health care claims, data from research and clinical trials, and much more.15
Without any intrinsic value, digital currency is incredibly vulnerable to huge price swings. That means a sudden boom — or bust — could take any investor for a wild ride.
## Financial Lesson:
CRYPTOCURRENCY IS STILL A GAMBLE IN THE DIGITAL GOLD RUSH AGE
Cryptocurrency fever has ignited a digital gold rush.
More people than ever are excited about digital currency, and they’re diving into the crypto space for all sorts of reasons.3 Excitement, speculation, and the desire to be part of a new technology are just some reasons for the frenzy around cryptocurrency.
And it’s not just the little guys who want to stake their claims in the crypto space.
Publicly traded companies see digital currency as a way to hedge against inflation. That’s why some own billions in cryptocurrency.16
All of this has given digital currency strong staying power.
But it doesn’t change the risks or make this new asset class any less volatile. And it doesn’t mean it’s right for you.
Cryptocurrency is still highly speculative.
Without any intrinsic value, digital currency is incredibly vulnerable to huge price swings. That means a sudden boom — or bust — could take any investor for a wild ride.
Before jumping in, think about your objectives and your reasons for wanting to invest in cryptocurrency.
Are you afraid of missing out?
Are you prepared to withstand some big swings? Are you willing to lose it all?
These are just some of the questions you need to ask yourself to figure out if crypto truly makes sense for you.
The bottom line?
Cryptocurrency’s growing popularity and flashy headlines play to our emotions. The excitement and promises of big gains can push us to dive in before we really know the risks we’re taking on.
If you understand the basics, though, you can resist the temptation that comes with crypto fever, and you can set more realistic expectations when it comes to digital currency. You’ll also be setting yourself up to make better, more rational decisions in the face of any new “hot” financial trend.
Goran Ognjenovic
Independent Investment Advisors
P.S. Sign up for my emails to continue the conversation. My subscribers get my best insights!
SOURCES & DISCLOSURES
1 – [https://blog.chainalysis.com/reports/banks-cryptocurrency-exposure-risk-fincen](https://www.chainalysis.com/blog/banks-cryptocurrency-exposure-risk-fincen/)
2 – [https://www.coindesk.com/retail-investors-own-crypto-survey](https://www.coindesk.com/markets/2021/02/21/a-quarter-of-us-investors-own-crypto-survey/)
3 – [https://think.ing.com/uploads/reports/IIS\_New\_Tech\_Cryptocurrencies\_report\_18092019.pdf](https://think.ing.com/uploads/reports/IIS_New_Tech_Cryptocurrencies_report_18092019.pdf)
4 –
5 –
6 – [https://www.researchandmarkets.com/reports/5012722/cryptocurrency-market-growth-trends-and?utm\_source=GNOM&utm\_medium=PressRelease&utm\_code=ksfvr6&utm\_campaign=1465891+-+Global+Cryptocurrency+Market+(2020+to+2025)+-+Growth%2c+Trends%2c+and+Forecasts&utm\_exec=jamu273prd](https://www.researchandmarkets.com/reports/5012722/cryptocurrency-market-growth-trends-and?utm_source=GNOM&utm_medium=PressRelease&utm_code=ksfvr6&utm_campaign=1465891+-+Global+Cryptocurrency+Market+(2020+to+2025)+-+Growth%2c+Trends%2c+and+Forecasts&utm_exec=jamu273prd)
7 –
8 –
9 – [https://www.consumer.ftc.gov/articles/what-know-about-cryptocurrency](https://consumer.ftc.gov/node/77130)
10 – [https://www.consumer.ftc.gov/blog/2020/07/avoiding-cryptocurrency-scam](https://consumer.ftc.gov/consumer-alerts/2020/07/avoiding-cryptocurrency-scam)
11 –
12 –
13 –
14 –
15 –
16 –
The following posts and commentary are to be used solely as educational tools and do not contain investment advice. Investment advice must be tailored to a particular investor’s specific needs. None of the information contained should be construed to be investment advice. Individuals wishing to tailor a plan to their own needs should seek the help of a Registered Investment Advisor.
There is a high degree of risk in investing and trading. Independent Investment Advisors assumes no responsibility. Principles of Independent Investment Advisors may, at times, maintain directly or indirectly, positions in securities or derivatives mentioned in these comments.
Risk Disclosure: Investing involves risk including the potential loss of principal. No investment strategy can guarantee a profit or protect against loss in periods of declining values. Past performance does not guarantee future results.
This material is for information purposes only and is not intended as an offer or solicitation with respect to the purchase or sale of any security. The content is developed from sources believed to be providing accurate information; no warranty, expressed or implied, is made regarding accuracy, adequacy, completeness, legality, reliability, or usefulness of any information. Consult your financial professional before making any investment decision. For illustrative use only.
Opinions expressed are subject to change without notice and are not intended as investment advice or to predict future performance. These are the views of Finance Insights and not necessarily those of the named representative or firm, and should not be construed as investment advice.
This information is not intended to be a substitute for specific individualized tax advice. We suggest that you discuss your specific situation with a qualified tax professional.
---
### [How Far Could $1 Million Go in Retirement](https://independentadvisorsnw.com/homepage/education/how-far-could-1-million-go-in-retirement/)
**Published:** April 12, 2021
**Author:** Financial Planner
**Content:**
[< back to Investor Education Center](https://independentadvisorsnw.com/homepage/education/)
# How Far Could a Cool $1 Million Go in Retirement?
A million dollars used to be the ultimate target for retirement portfolios. Retiring as a millionaire brought status and confidence that you could live comfortably during your golden years. If you retired with $1 million in 1970, you probably didn’t have to worry about your nest egg running out, even with a lavish lifestyle. It would be like retiring with $6.9 million today.
Retire with $1 million in the ’80s, and it would have been like retiring with $3.35 million in 2021.
And in 1990? A cool $1 million would have gone twice as far as it does these days. Clearly, $1 million doesn’t go as far as it used to.
Just how far could it go these days? In retirement, as in real estate, location is everything (or, at least, it’s a lot). The map below shows how long $1 million could last in each state. This state-by-state breakdown features a few different hypothetical growth scenarios and the results of our calculations. The answer depends on how and where you live.
Let’s see how long a $1 million nest egg could last where you want to retire — or wherever you’ve already retired.
[](https://independentadvisorsnw.com/)Cost of Living in Retirement Map
## What’s missing from this picture?
The estimates in the map above cover the basics and paint a potentially realistic picture. They don’t fill in every piece of the puzzle, though. In fact, some key aspects of life in retirement aren’t included in the hypothetical scenarios shown in our $1 million retirement map. Here are a few of them.
### HIGHER-THAN-AVERAGE EXPENSES
The averages used to calculate expenses in retirement may not fit how you actually live. If you’re spending more or less than the average for your area, your expenses could drain your savings faster or make them last longer. That’s why you can’t fully rely on averages to anticipate how long a nest egg could last.
### THE FUN STUFF!
Retirement isn’t just about covering the basics to get by. You retired because you want to enjoy your time and do fun things, maybe even things you had put off while working or raising a family. Whatever that fun looks like for you, our estimates don’t capture these costs.
### PERFORMANCE REALITIES
Our calculations assumed stable annual growth for retirement portfolios. Of course, that’s not realistic or reliable. Investment performance can vary drastically from year to year. A personal retirement income plan should account for these types of ups and downs. It should also build in some flexibility for responding to performance changes while keeping you on track to hit your goals.
### HEALTH CARE
Health care is a significant expense for most retirees. In fact, a healthy couple retiring at age 65 in 2021 could need $662,156 or more to cover their health care costs for the rest of their lives.2 Perhaps ironically, those of us fortunate enough to retire in good health could end up paying more in health care costs than retirees with health problems. Why? Because, when we live longer, we’ll be paying for health care costs longer.
### LONG-TERM CARE
About 70% of retirees who are age 65 or older will need long-term care at some point in their lives.3 These costs vary by location and length of stay. Still, nearly 50% of retirees will need about a year of long-term care. Depending on where you live and whether you have LTC coverage, that could run anywhere from $54,000 to more than $105,000 in out-of-pocket costs every year. And those costs are only getting more expensive. By 2030, expect those costs to be at least 35% higher.
### TAXES
Many folks are surprised by the taxes they owe after they stop working. Tax laws are ever-changing and can have a significant impact on how much you owe in taxes during retirement. Fortunately, proactive planning may help mitigate the impact of taxes on your expenses.
### LIFESTYLE
What do you want to do in retirement? What kind of extras do you want to enjoy and share with your loved ones? What does your dream lifestyle in retirement look like? The price tag associated with those dreams is a big variable in your personal retirement calculations.
## Financial Lesson
How Do You Want to Live in Retirement?
A cool million just doesn’t go as far as it used to.
Were you shocked by how little $1 million could last in some places? Or how long in others?
It certainly illustrates what a difference cost of living can make to your finances.
And it also shows that averages leave out a lot of important detail.
While benchmarking your likely expenses is a good starting point, tweaking them for your personal situation is critical. As is remembering that your expenses will change as you journey through your retirement. In my experience, folks typically spend more on lifestyle, family, and fun at the beginning of their retirement. They may see their medical and long-term care expenses increase as they age.
---
### [6 Small Business Retirement Plans](https://independentadvisorsnw.com/homepage/education/6-small-business-retirement-plans/)
**Published:** January 21, 2021
**Author:** Investment Advisor
**Content:**
[](https://independentadvisorsnw.com/homepage/education/)[< back to Investor Education Center](https://independentadvisorsnw.com/homepage/education/)
## 6 Small Business Retirement Plans
Like almost everything else, setting up a retirement savings plan falls on the shoulders of a small business owner. The plan you chose depends on your business’s size, how it’s structured, and how much money you think you can afford to put aside. Self-employed individuals can take advantage of the fact that they are considered both employer and the employee. Here are six basic types of small business retirement plans:
### 1. MyRA
Roth IRA that invests in government bonds.
- Contribution limits: $5,500.
- No-hassle plan for employers.
Like almost everything else setting up a retirement savings plan falls on the shoulders of a small business owner
The MyRA is as simple as it gets. The minimum deposit is $25 per employee, and you or your employees can contribute as little as $5 per pay period. There is no cost to employers. They don’t administer employee accounts, nor do they contribute to them or match employee contributions. The government provides all the materials you need to explain how it works to employees.
The accounts are Roth IRA’s, which means contributions are made with after-tax dollars. The money earns a guaranteed return equal to that of the “G” fund in the government’s Thrift Savings Plan. Savers can contribute up to $5,500 per year or $6,500 if they are age 50 or older. Money contributed can be withdrawn at any point without taxes or penalties. Participants can accumulate no more than $15,000. After that, the money must be rolled over into a privately held Roth IRA.
### 2. SEP-IRA’s
Simplified Employee Pension Plan.
- No government filings.
- Contributions only from employer.
- For sole proprietors, partnerships, corporations
The employer makes all contributions for Simplified Employee Pension plans or SEPs. The maximum contribution can’t exceed the lesser of $53,000 for the 2015 and 2016 tax years or 25% of the employee’s net compensation.
For self-employed individuals, the IRS defines compensation as your net earnings from self-employment, reduced by one-half of your self-employment tax and by your entire SEP-IRA contribution.
Besides the employer employees’ SEP-IRA contribution, they can save in their IRAs up to $5,500 for the 2015 and 2016 tax years, or $6,500 if age 50 or older. If you are an owner-only business, you can save both ways – a great way to maximize your retirement savings while lowering your taxes.
Sole proprietors, partnerships, and corporations, including S corporations, can set up SEP-IRAs. A small company may be eligible for a $500 tax credit for three years to offset the startup costs. You don’t have to contribute every year.
### 3. SIMPLE IRA
Savings Incentive Match Plan for Employees.
- Employers must contribute annually
- Employees can contribute $12,500
- $3,000 catch-up contributions allowed
- For small companies
The Savings Incentive Match Plan for Employees of Small Employers, or SIMPLE IRA, could be a great choice if you want to contribute to a retirement plan and you have a small company – fewer than 100 employees.
- An employee may choose to contribute, but an employer must contribute annually.
- An employee can contribute up to $12,500 in 2015 and 2016. Those 50 and over can make a catch-up contribution of $3,000 in 2015 and 2016.
The employer can participate in one of two ways. He or she can choose to match each employees’ contributions dollar-for-dollar, up to 3% of the employee’s compensation. If the employer has a lousy year, the matching contributions can be reduced to less than 3%, but the contribution must be at least 1%, and this haircut is only allowed in two out of five years.
Alternatively, an employer can make a 2% contribution of total compensation for each eligible employee up to a cap in 2015 and 2016 of $265,000. Under this option, employees don’t have to contribute anything, but they can – up to employee contribution limits stated above.
### 4. SIMPLE 401(k)
Savings Incentive Match Plan for Employees.
- Similar setup as SIMPLE IRA
- Can allow loans from the plan
The SIMPLE IRA has a first cousin, the SIMPLE 401(k). The contribution rules are similar. In both cases, the plans aren’t subject to non-discrimination income tests that apply to regular 401(k) plans, and employees are fully vested immediately for all contributions.
The most significant difference is that SIMPLE 401(k) can allow loans from the plan, an option some small business owners may find attractive.
### 5. Solo 401(k) Plans
- Contributions can’t exceed $53,000
- For self-employed, owner-only businesses and partnerships
- Must file paperwork once assets reach $250,000
The best thing about one-participant or Solo 401(k) is that you can maximize contributions if your income is too low to allow you to get most of the SEP-IRA plan. For example, you have to earn a lot to contribute the maximum $53,000 to a SEP-IRA; conversely, you can earn less and still contribute more to a 401(k) plan.
The Solo 401(k) works like this:
As both employer and employee, a business owner can contribute both:
- Elective deferrals up to 100% of the “earned income” up to the annual contribution limit or for those over 50 up to $24,000.
- 25% of compensation, which the IRS defines as net earnings from self-employment minus one-half of your self-employment tax, minus the contributions you make to your retirement plan.
Self-employed individuals and owner-only businesses and partnerships are eligible. Owner’s spouses also may participate.
### 6. Defined Benefit Plans
Fixed benefits tied to tenure and salary.
- Generous contribution limits
- Enrolled actuary determines funding levels
- Must file annually with government
- Employer assumes all investment risk
Of all the small business retirement plans available, the old-fashioned defined benefit retirement plan may be the best for ensuring a comfortable old age.
Defined benefit plans provide a fixed benefit generally tied to tenure and salary for an employee’s retirement. The employer bears all investment risk. These plans are especially advantageous for high-income professionals who can afford the costs to both set up and administer them.
The most likely participants are doctors, dentists, lawyers, accountants, and consultants in partnerships, family businesses, or other small entities. It can also be an attractive option for a couple when one is a high earner with a good corporate retirement plan, and the other is self-employed and makes an income that the couple doesn’t need. Retired professionals earning money as consultants also find them an attractive way to shelter income or as part of an estate-planning strategy.
---
### [Opportunities Opened Up by New Tax Rules](https://independentadvisorsnw.com/homepage/education/opportunities-opened-up-by-new-tax-rules/)
**Published:** February 18, 2021
**Author:** Financial Planner
**Content:**
[](https://independentadvisorsnw.com/homepage/education/)[< back to Investor Education Center](https://independentadvisorsnw.com/homepage/education/)
Tax Cut and Jobs Act TCJA passed at the end of 2017 SECURE Setting Every Community Up for Retirement Enhancement Act radically changed your tax picture
The Tax Cut and Jobs Act (TCJA), passed at the end of 2017, and SECURE (Setting Every Community Up for Retirement Enhancement) Act, passed at the end of 2019, radically changed your tax picture.1 Most Americans are going to pay less in taxes under the new tax brackets, and a few are going to use this great opportunity to permanently lower the taxes they pay. The COVID-19 pandemic and relief acts also spurred new tax wrinkles you should know about.
**I want to emphasize that this is a limited opportunity to leverage current laws.** The 2017 rules are scheduled to expire in 2025 (if they don’t disappear sooner under the new administration), and most taxpayers will see a tax hike.2
However, this sneaky IRS move means you’ll probably pay more in taxes even before they expire. To reduce the impact of the new tax laws on government revenue, the IRS changed how it increases things like thresholds, deductions, and credits for inflation.3 It sounds like a minor procedural move, but it’s actually a big deal. In plain English, this change means that many taxpayers will “creep” into higher tax brackets as their incomes grow because the tax brackets themselves won’t increase as much as they used to for inflation. Bottom line: many taxpayers will pay more in taxes over the next few years due to this hidden tax increase. It might be only a few hundred dollars every year, but over time, even small tax increases add up! Unless you take steps now to reduce your taxable income. The current tax rates might be the lowest you’ll see for the rest of your life, and I want you to make the most of them. All 6 opportunities in this guide are actions you can take right now to potentially lower your taxes this year and in the years to come. I strongly recommend that you take this list, along with your tax return, to your CPA and financial professional to see which tax reduction opportunities have opened up for you.
**Take the Standard Deduction Later**
The new tax rules nearly doubled the standard deduction and did away with many write-offs, removing the tax benefit of itemizing deductions for most taxpayers.4 However, an old accounting trick means you can still optimize your deductions under the new rules by “bunching” itemized deductions in a single year to get over the standard deduction threshold and then taking the standard deduction the following year—potentially maximizing your tax savings multiple years in a row. For example, if your property taxes for 2022 are assessed in 2021, you can pay them in 2021 and take the deduction in 2021. Or you can make several years of charitable contributions in 2021 instead of making your usual annual contributions.
**Pre-Pay Your Medical Expenses**
Have major medical-related expenses coming up? You can potentially maximize the tax deduction by prepaying your out-of-pocket medical expenses for the year to get above the standard deduction amount and meet the 7.5% AGI threshold (and maybe even get a discount for paying up front). What kind of medical expenses qualify? A surprising number, including unreimbursed doctor fees, long-term care premiums, certain Medicare plans, and some home modifications.5
**Give Money to Your Favorite Charity Right from Your IRA (New SECURE Act Opportunity)**
Even though the SECURE Act changed the age at which your RMDs must start from 70½ to 72, you still have the right to make Qualified Charitable Distributions directly from your IRA to a qualifying charity once you’re 70½, allowing you to exclude up to $100,000 from your gross income (with certain restrictions).6
**Lower Your Taxable Income with a Roth Conversion (But Do-Overs Are Done)**
A Roth conversion is a great way to permanently lower your taxable income in retirement by converting tax-deferred assets into tax-free assets and paying taxes on the conversion in an optimal tax year (like under today’s favorable tax brackets or if your retirement assets lost value this year). For example, if you’re a married couple filing jointly and your household earned $250,000 in 2020, your effective tax rate is about 16.9%, while it was 23.09% under the old rules.7 Unless you expect your taxes to be lower in future years, now may be an ideal opportunity for a Roth conversion. Under the old rules, you could choose to reverse a Roth conversion (called re characterization) and eliminate the tax bill. That loophole is gone, meaning once you convert that Traditional IRA to a Roth, you don’t get a do-over.8 So you really have to look at all the variables and pick the right time for the move. We can review your options together and choose the optimal strategy for you.
**Review How You’re Paying Your Investment Fees**
Prior to the TCJA, you could write off some of the fees you pay for investment management. The TCJA did away with that deduction, but there are still ways to pay fees with pre-tax dollars, if they make sense in light of your overall financial goals and investment performance.9 That’s why we run the numbers with clients to potentially maximize the after-tax return on their investments—not just the market return.
Optimize Your Retirement Contributions
The TCJA and SECURE Act introduced many changes to tax rules. The 2020 CARES Act also temporarily changed certain tax requirements, making tax planning even more critical this year. The most important step you can take right now to reduce your taxes this year may be to review how and where you’re making retirement contributions. Why? Because you may be missing out on critical tax savings (and investment growth) if you’re not optimizing your contributions. Depending on how close you are to retirement and your overall financial picture, you might be better off splitting contributions between retirement accounts or even diverting your contributions elsewhere to reduce debt (such as mortgage interest that is no longer deductible if you claim the standard deduction). We can run the numbers together, if you’d like a professional opinion.
## Special COVID-19 Considerations That Could Affect You
**ECONOMIC STIMULUS CHECK**
If you didn’t get a check from the IRS yet and think you’re owed, don’t worry. Since it’s technically an advance refund of a 2020 tax credit, if eligible, you’ll receive it after filing your 2020 taxes. Important! You do not owe income taxes on your stimulus payment, nor must you pay it back.10
**WORKING REMOTELY**
If you left your home state and worked remotely in another during 2020, you could owe taxes to the second state. Each state has different tax reporting requirements for remote workers, so it’s critical to gather records and file accurately.11 The TCJA and SECURE Act introduced many changes to tax rules. The 2020 CARES Act also temporarily changed certain tax requirements, making tax planning even more critical this year. I’m a financial professional who helps clients use the new tax rules to uncover opportunities, identify risks, and keep more of their money working for them. I also help my clients plan for future taxes and create a retirement income plan to help minimize the taxes they will pay.
Sources & Disclosures
1 – [https://taxfoundation.org/final-tax-cuts-and-jobs-act-details-analysis/](https://taxfoundation.org/research/all/federal/final-tax-cuts-and-jobs-act-details-analysis/)
2 – [https://taxfoundation.org/look-ahead-expiring-tax-provisions/](https://taxfoundation.org/blog/look-ahead-expiring-tax-provisions/)
3 –
4 – [https://taxfoundation.org/90-percent-taxpayers-projected-tcja-expanded-standard-deduction/](https://taxfoundation.org/data/all/federal/90-percent-taxpayers-projected-tcja-expanded-standard-deduction/)
5 – [https://www.aarp.org/money/taxes/info-2018/medical-deductions-irs-fd.html](https://www.aarp.org/money/taxes/info-2020/medical-expenses-tax-deduction-rules.html)
6 –
7 –
[https://www.irs.gov/pub/irs-prior/i1040tt–2017.pdf](https://www.irs.gov/pub/irs-prior/i1040tt--2017.pdf)
8 –
9 –
10 –
11 –
Risk Disclosure: Investing involves risk including the potential loss of principal. No investment strategy can guarantee a profit or protect
against loss in periods of declining values. Past performance does not guarantee future results.
Neither the named representative nor the named firm gives tax, accounting, or legal advice. This material is for information purposes only
and is not intended as an offer or solicitation with respect to the purchase or sale of any security. The content is developed from sources
believed to be providing accurate information; no warranty, expressed or implied, is made regarding accuracy, adequacy, completeness,
legality, reliability or usefulness of any information. Consult your financial professional before making any investment decision. For
illustrative use only.
---
### [End of Year Financial Checkup](https://independentadvisorsnw.com/homepage/education/end-of-year-financial-checkup/)
**Published:** December 16, 2020
**Author:** Financial Planner
**Content:**
[< back to Investor Education Center](https://independentadvisorsnw.com/homepage/education/)
End of Year Financial Checkup
# End of Year Financial Checkup
The end of a fiscal year brings many opportunities to reflect on our financial objectives, our financial blunders, and our financial accomplishments for the year. Think back to the goals you set for yourself at the beginning of the year. Did you get where you wanted to? If not, why? If so, congratulations! Let’s rinse and repeat!
There are lessons to be gleaned from both our failures and our achievements. Nowhere is this truer than in the economic arena. A thorough financial checkup during this introspective time of the year will help you establish a more straightforward financial plan for next year and beyond!
Begin at the end. Take an honest look at where you’ve ended up financially this year. Perhaps you had a particular financial goal in mind, like paying off a credit card or boosting your credit score, or putting more toward retirement. If you didn’t quite get there, ask yourself how far you got and what prevented you from hitting your target. Was it unrealistic? Maybe you had a significant life event that derailed you (such as divorce, new baby, job change). Consider whether you anticipate any such events in the coming year so that you can adjust your goals accordingly.
Once you have done some reflecting on whether your financial goals were met and what you should do differently next year, dive into some forward-looking practices to help you get a clearer picture of your current financial health. Start with your budget. Is the budget you established for yourself at the beginning of the year still adequate? Did you consistently go over or under in any areas? Adjust as needed for the next year. And if you’ve stuck to your budget, you hopefully have a surplus that can be used to pay down debt, get invested, or put aside for emergency funds.
Speaking of emergency funds, you should have at least six months’ worth of expenses saved up in the event of an emergency such as job loss or health crisis. If you don’t, try to start putting away a little each month toward this goal. It’s also an excellent time to double-check that you max out your 401(k) contributions. If it is not within your reach right now, strive to contribute at least as much as your employer will match.
Other financial well-being areas to look into include credit card interest rates, stocks, and insurance policies. Many people don’t know you can call your credit card company and negotiate a better interest rate, especially if you have been faithfully paying down your debt over the last 12 months. You might also use this time to study your stock portfolio. Are there adjustments that need to be made based on the economic outlook for the next year? Finally, review your insurance policies to ensure your coverages are still relevant. You may also qualify for new discounts, and you may need to add significant purchases made over the last year to your policy.
During this festive time of year, sitting down to examine your finances may sound like an ultimate killjoy. But as you turn your thoughts towards resolutions for your physical, mental, and spiritual health, don’t neglect your financial health.
---
### [Financial Calculators](https://independentadvisorsnw.com/homepage/financial-calculators/)
**Published:** October 29, 2020
**Author:** Financial Planner
**Content:**
[< back to Investor Education Center](https://independentadvisorsnw.com/homepage/education/)
# Financial Calculators
A critical component of any financial plan and ongoing wealth management process is modeling through various what if scenarios We use these financial calculators to do just that Creating a best case and a worst case makes up an investment planning framework we use to manage our clients wealth over the years to come
Here are some fundamental financial calculators our clients and we regularly use to build and maintain financial and investment plans. Working together we model through various what-if scenarios such as best-case and worst-case and then based on the outcome, we create contingency plans and adjustments clients need to make to stay on top of their investment goals.
[Retirement Savings Calculator:](https://independentadvisorsnw.com/homepage/financial-calculators/retirement-savings-calculator/) Answer the question, “Given the value of my current investments how much do I need to save each month to reach my retirement goal?”
[Retirement Nest Egg Calculator:](https://independentadvisorsnw.com/homepage/financial-calculators/retirement-nest-egg-calculator/) Answer the question, “Given the value of my current investments and assuming future monthly investments of “X”, what will be the value of my retirement nest egg?”
[Retirement Age Calculator:](https://independentadvisorsnw.com/homepage/financial-calculators/retirement-age-calculator/) Answer the question, “Given the value of my current investments and assuming future monthly investments of “X”, at what age will I reach my retirement goal?”
[Savings & Investment Calculator:](https://independentadvisorsnw.com/homepage/financial-calculators/savings-investment-calculator/) This calculator easily answers the question “If I save ‘X’ amount for ‘Y’ months what will the value be at the end?”
[Mortgage Calculator:](https://independentadvisorsnw.com/homepage/financial-calculators/mortgage-calculator/) You can calculate the mortgage loan amount from the real estate price by providing the down payment percentage. If you know the mortgage amount you can afford and the cash down payment percentage required, you can calculate the affordable real estate price.
[Loan Calculator: ](https://independentadvisorsnw.com/homepage/financial-calculators/loan-calculator/)Enter a “loan amount,” “number of months,” “annual interest rate.” The calculator calculates the number of monthly payments.
---
### [What Should You Do With An Old 401k](https://independentadvisorsnw.com/homepage/education/what-should-you-do-with-an-old-401k/)
**Published:** November 3, 2020
**Author:** Financial Planner
**Content:**
[< back to Investor Education Center](https://independentadvisorsnw.com/homepage/education/)
# What Should You Do With An Old 401(k)?
If you are considering a job change in the future or have already made the transition you may be wondering What should I do with my old 401k You have several options to consider cash it out let it be or roll it over into your new plan or an IRA There are benefits and drawbacks of each to consider
If you are considering a job change in the future or have already made the transition, you may be wondering, “What should I do with my old 401k”? You have several options to consider – cash it out, let it be, or roll it over into your new plan or an IRA. There are benefits and drawbacks of each to consider.
**Cash It Out**
If you are looking to receive a lump sum of money from your old 401k, you should also be ready to fork over a chunk of money to Uncle Sam. Another drawback to this approach, you may have to pay penalties if you were under the age of 55 when you left your former employer. If these circumstances apply, you may want to consider another option for your old 401k.
**Let It Be**
You could choose to let your old 401k stay in place. However, your account may need to be active with various rules to follow. Be sure to check your plan policy. Also, consider that you will no longer be able to contribute to it. However, if your 401k is less than $5,000.00, you might have to move it, or it could be distributed to you.
**Roll It Over**
Consider rolling over your 401k to your new plan if this is an option. It might be easier to manage than having two accounts. However, make sure you consider the investment options with the new plan and any applicable fees. Another option that will provide you with much more flexibility and lower fees is to roll your old 401k into an IRA.
Before deciding, make sure you evaluate your options and talk to a financial adviser if necessary. After all, you have worked hard for your 401k. Do not let the penny of it go to waste!
---
### [Annual and Lifetime Gift Tax Exclusions Primer](https://independentadvisorsnw.com/homepage/education/annual-and-lifetime-gift-tax-exclusions-primer/)
**Published:** October 22, 2020
**Author:** Financial Planner
**Content:**
[< back to Investor Education Center](https://independentadvisorsnw.com/homepage/education/)
As the year end approaches its essential to start tax and gift planning efforts There are several nuances to current federal rules when it comes to gift tax exclusions Here are some of the most notable details you everyone needs to know
# Annual and Lifetime Gift Tax Exclusions Primer
As the year-end approaches, it’s essential to start tax and gift planning efforts. There are several nuances to current federal rules when it comes to gift tax exclusions. Here are some of the most notable details you everyone needs to know:
For 2020 the annual federal gift tax exclusion per individual is $15,000. The annual federal gift tax exclusion allows individuals to give away up to $15,000 to other people without those gifts counting against the lifetime exemption.
Under the most recent rules, the annual gift tax exclusion is indexed for inflation. Which means fixed increments of $1,000 can adjust the exclusion.
The Tax Cuts and Jobs Act established exemption thresholds for the federal lifetime estate and gift tax exemption. For 2020, the lifetime gift tax exclusion per individual is $11.58 million. It means that people can give up to $11.58 million in gifts throughout their lifetime without ever having to pay gift tax on it. For married couples, both spouses get an $11.58 million exemption. It means that married couples can give away a total of $23.16 million before paying the gift tax.
An example, a married couple wants to make a gift to their son, who is also married. They can each give $15,000 to their son and the son’s spouse (so $60,000 in total) without triggering any estate tax.
Another example, if an individual has an estate with a market value of $30 million when they pass. If their spouse is a sole inheritor, the spouse is covered by unlimited marital deduction, and the estate tax doesn’t apply to inherited assets. However, this doesn’t translate to other beneficiaries after the spouse passes. So, their children, for example, would eventually owe estate tax if the estate exceeds the exclusion limit.
Unfortunately, gifts to trusts are generally not eligible for the annual exclusion. However, gifts to a 529 plan are excluded. The IRS also allows taxpayers to front-load several years of 529 plan donations into a single year. A donor can front-load five years’ worth of annual exclusion gifts into a single year’s contribution to a 529 plan.
For example, a parent or a grandparent could contribute up to $75,000 in one year to their child/grandchild without using any of the lifetime exemptions. Their spouse can do the same to superfund the 529 account.
In addition to federal estate taxes, 13 other jurisdictions in the United States impose estate taxes. They are Connecticut, DC, Hawaii, Illinois, Main, Massachusetts, Maryland, New York, Oregon, Minnesota, Rhode Island, Vermont, and Washington.
---
### [Is it time to see a Financial Advisor?](https://independentadvisorsnw.com/homepage/education/is-it-time-to-see-a-finanacial-advisor/)
**Published:** September 4, 2020
**Author:** Financial Planner
**Content:**
[< back to Investor Education Center](https://independentadvisorsnw.com/homepage/education/)
*Are you managing your money by yourself or preparing for retirement? How do you know when its time to consult a financial or investment advisor? Here are a few tips on when to seek the counsel of a financial adviser:*
## Define, Track and Achieve Financial Goals
Are you looking to save for your children’s college fund? Or prepare for retirement? Or maybe you need to diversify your investment portfolio properly, but don’t know how to go about it. An experienced financial advisor can help you create and implement a strategy to help achieve your financial goals.
Are you managing your money by yourself or preparing for retirement? How do you know when its time to consult a financial or investment advisor? Here are a few tips on when to seek the counsel of a financial adviser:
## Prepare for Major Life Events
Do you have a significant life event in your future? Perhaps you are getting married, preparing for the birth of a child, or eagerly awaiting retirement. These life changes can create stress on financial plans. Fortunately, an adviser can help clients embrace upcoming changes in their lives. By receiving, the appropriate and realistic advice, clients can develop a solid plan, maximize returns on their investments, and secure wealth for the future.
## Leave a Legacy
Preparing for the unexpected can safeguard finances in a time of uncertainty. Make sure your spouse, children, and grandchildren are taken care of in the event of an untimely passing. A financial adviser can point you in the right direction to help you protect your assets. Leave things in the right hands for the next generation.
---
### [Top Ten Financial Planning Tips for Business Owners](https://independentadvisorsnw.com/homepage/education/top-ten-financial-planning-tips-for-business-owners/)
**Published:** September 10, 2020
**Author:** Financial Planner
**Content:**
[< back to Investor Education Center](https://independentadvisorsnw.com/homepage/education/)
# Top Ten Financial Planning Tips for Business Owners
### Managing Cash and Debt Levels
External demands on business owner’s financing situation are endless, so it’s critical to monitor expenses and conserve dollars to finance the operations.
### Paying Yourself
Business owners often pay themselves very little in the way of salary. Partially due to the need to minimize personal payroll and income taxes. While these actions can be a big help at tax time, they can be roadblocks to helping business owners accumulate savings for retirement or other goals.
Choosing a Financial Advisor or Financial Planner### Choosing a Financial Advisor or Financial Planner
Most business owners would benefit from the guidance and assistance of an appropriate advisor. However, it’s important to ask the following questions:
- Is he or she an expert in wealth management, as it relates to business owners?
- Does the advisor have a fiduciary responsibility to put their clients first, with no compensatory conflicts?
Registered Investment Advisors (RIAs) comply with the standards listed above and are regulated by the Securities and Exchange Commission (SEC) or their state.
### Personal Goals
As a business owner, you should make an effort to establish your personal goals in the same way you put together multi-year business plans. Starting a conversation with family members or advisors is a great start. A critical step is to determine what is “reasonably possible” for you to achieve, given your financial circumstances.
### Planning for Retirement
Take some time to determine how much money it will take to fund your retirement or second-career dreams. Tracking or paying close attention to “personal” expenses, as opposed to business expenses, can be accomplished with online tools or a good old-fashioned spreadsheet.
### Saving for Retirement
Similar to a 401(k) plan, set up regular automatic payments to your savings to accumulate enough money to fund your personal hopes and dreams. Of course, many [business owners’ hopes and plans](https://independentadvisorsnw.com/homepage/education/business-owner-exit-planning/) include the potential of selling their business to support their relaxation and recreation during retirement. However, this is a massive unknown for most companies, and dreaming of a big payoff from a business’s sale may not be realistic for everyone.
### Diversifying Your Assets
As you save and invest money for the future, ensure that it is properly diversified and compatible with the amount of risk you are willing to bear. Don’t fall prey to “market timing.” Determine an investment policy and execute it in a disciplined way; then spend most of your time managing your business.
### Managing Risk
Beyond their monetary investments, it’s essential for business owners to establish protection for their families. Life insurance and buy-sell agreements, which deal with the buyout of a deceased partner or the business, can safeguard your survivors in the event of your death.
### Planning for Succession
It’s essential to keep the issue of succession planning in mind. Getting the most of your business or real estate investment, later on, can help guide your personal wealth management decisions after you’ve left the helm.
### Arranging Your Estate
Regardless of age, business owners should meet with a qualified attorney and estate-planning specialist to ensure that their goals and wishes are properly accounted for, including business assets plans. At a minimum, business owners should have an updated will that contains instructions on how their assets should be distributed, which may or may not include business assets.
---
### [Invest with Your Head, Not with Your Heart](https://independentadvisorsnw.com/homepage/education/invest-with-your-head-not-with-your-heart/)
**Published:** September 29, 2020
**Author:** Investment Advisor
**Content:**
[< back to Investor Education Center](https://independentadvisorsnw.com/homepage/education/)
Invest with Your Head Not with Your Heart
# Invest with Your Head, Not with Your Heart
Are you moved by the swings in the stock market, ready to trade at a moments notice? Or are you looking for the hottest stock that will undoubtedly make you thousands of dollars? Resist the urge to give in to the temptation of emotional investing. Invest with your head and not with your heart. Here are a few tips to avoid the pitfalls of emotional investing:
## Don’t Overreact in Market Volatility
Being glued to every peak and valley of the stock market can pave the way to making risky decisions. Avoid hasty decisions in a time of market volatility. Do not make decisions based on outdated advice or be subject to the latest headlines. Think twice before selling off stocks. Not sure what to do? Consult a seasoned financial professional who has weathered market volatility.
## Slow and Steady Wins the Race
Don’t make decisions that you will regret in the long run. As the saying goes, slow and steady wins the race. Be sure you are cutting your losses and maximizing gains. However, do make sound decisions to meet your financial goals. Consider investment goals and timing before making decisions. Aim for a diversified portfolio and proper allocation for your assets to create a solid financial footing for your future.
## Learn from the Past
Everyone had learned from the trying times of 2008 when the U.S. entered the Great Recession. While that time may have appeared catastrophic a the moment, people survived. Not reacting in fear and making strategic decisions (not emotional ones) was the key to success. Weathering the storm let to brighter days ahead.
Although the future is uncertain, investors can control their reaction to market volatility. Selling at a moment’s notice and acting in fear is not wise. Investing with your head – not with your heart – will help you stay the course.
---
### [Prospects for Investing in the 2020s](https://independentadvisorsnw.com/homepage/education/prospects-for-investing-in-the-2020s/)
**Published:** September 29, 2020
**Author:** Investment Advisor
**Content:**
[< back to Investor Education Center](https://independentadvisorsnw.com/homepage/education/)
# Prospects for Investing in the 2020s
The third decade of the 21st century started with a strong economy, record low unemployment levels, and benign inflation. But late in the first quarter over the span of two weeks, investors faced the fastest stock market correction in history.
With an unpredictable assailant like a global virus, Congress and the Federal Reserve’s short-term actions will need time to see if they are effective. Ultimately, the fate of the U.S. and global economies, which in turn will impact the investment markets, are dependent on how long the COVID-19 outbreak continues and if there is a second wave. Both supply and demand have been dramatically reduced, with a ripple effect on companies, workers, consumers, and investors. Once the crisis has passed, we will learn which sectors, industries, and individual companies remain financially viable with a business model built to sustain this unprecedented economic fallout.
The third decade of the 21st century started with a strong economy record low unemployment levels and benign inflation But late in the first quarter over the span of two weeks investors faced the fastest stock market correction in history
Amid this backdrop, wealth managers must read the tea leaves to anticipate what the investment markets will look like post-coronavirus. The challenge is how to best position assets to take advantage of future gains without giving up ground and turning paper losses into permanent shortfalls.
For individual investors, it comes down to what you want to accomplish in the next decade – or what your money can achieve for you. Are you nearing retirement? Will you remain in the accumulation phase, wherein you can afford to take on market risk? Are you just starting, and are you risk-averse due to the two significant economic declines experienced in your relatively short life, or are you prepared to invest in prospects – wherever they may lie?
Anyone already in or nearing retirement would do well to invest for a steady stream of income. While the DJIA initially took a beating, many blue-chip stalwarts continue to grow and payout dividends as they have long term, through thick and thin. However, pay attention here, as some long-standing dividend paying companies are starting to suspend or substantially cut dividend payments.
Growth-oriented investors would do well to look at companies that are well-positioned to survive the pandemic, because they may well represent commerce of the future. This includes the well-established FAANG stocks (Facebook, Apple, Amazon, Netflix, and Google), which have become masters of fast and reliable delivery of online content and physical delivery of essential and discretionary products. Unfortunately, these companies’ stock prices have soared in recent years, so it’s time to consider what the “next big thing” in this arena will look like and who are the frontrunners.
With that in mind, take a look at 2020 demographics. Millennials recently surpassed Baby Boomers as the largest generation in the United States, but they aren’t expected to hold this mantle for long. Generation Z/Centennials are on track to enter the workforce in higher numbers during the next decade. This is a generation that has never known life without cell phones and the internet, so expect the technology sector to ramp up not just with consumer innovations, but with ways to help other industries enhance data management, blockchain supply chains and artificial intelligence – which might become as omnipresent as retail strip malls.
In a post-pandemic world, employers seeking to strengthen their business models might come to embrace the idea of foregoing healthcare and other expensive benefits offered to employees. A subsequent world of higher pay and more public options could spur entrepreneurship and new small businesses. By taking advantage of remote employees, low overhead expenses, and emerging technologies, smaller companies or conglomerates might be able to compete with the likes of Amazon in both domestic and global markets.
As a short-term precaution, consider how you might defend your portfolio against the possibility of inflation as we stumble out of the pandemic economy. The federal government’s generous stimulus packages combined with continued easing of monetary policy by the Federal Reserve could lead the United States to higher inflation. This could be exacerbated by the recent shutdown of production in many industries; the initial low supply of products also might contribute to price escalation. Investors may want to consider investing in commodities and Treasury Inflation-Protected Securities for inflation protection during this interim.
As always, it’s best to seek the advice of a professional in this ever-changing environment.
---
### [Gross Domestic Product: A Primer](https://independentadvisorsnw.com/homepage/education/gross-domestic-product-a-primer/)
**Published:** September 30, 2020
**Author:** Investment Advisor
**Content:**
[< back to Investor Education Center](https://independentadvisorsnw.com/homepage/education/)
# Gross Domestic Product: A Primer
The economic indicator known as Gross Domestic Product (GDP) represents the dollar value of all purchased goods and services over one year. It is comprised of purchases from all private and public consumption, including for-profit, nonprofit, and government sectors. Four components are added to calculate the GDP:
- Consumer spending
- Government spending
- Investment spending (this includes business, inventory, residential construction, and public investment), net exports, meaning the value of goods exported minus the cost of goods imported
The government calculates and publishes the GDP rate quarterly and for the entire year.
The economic indicator known as Gross Domestic Product GDP represents the dollar value of all purchased goods and services over one year
## What Affects GDP?
There are different ways GDP is measured. For example, nominal GDP refers to a straight calculation of raw data, while real GDP adjusts the analysis to include the impact of inflation.
When inflation increases, the GDP tends to rise; when prices drop, so does the GDP. Be aware that this adjustment can happen even when there is no change in the quantity of goods and services produced in the United States during that time frame.
A vital component of the GDP calculation is net exports. This number rises when the country sells more goods and services to foreign nations than it buys. A trade surplus means the United States sells more than it purchases, which is a vital contributor to GDP. When the United States buys more foreign goods than it sells, this creates a trade deficit, a negative weight in the GDP calculation.
GDP also reflects demand. The dollar output of specific sectors and industries rises and falls based on their popularity and products and services. For example, when a new product is well received, then those sales increase that sector’s contribution to the GDP. This is a useful measure because it enables companies to make better research and development decisions based on recent success. The same is true when a new product, or even an upgrade to a new product, does not increase sales.
## What Does GDP Indicate?
The GDP is the most common, broad-based measure used to monitor the country’s economic progress. When it is on the rise, the economy is considered to be growing. When the GDP rate drops – even if it remains in positive territory – the economy is viewed as contracting. Suppose it continues to slip quarter after quarter. In that case, it is an indicator that the economy might be in trouble, and the Federal Reserve or Congress could consider altering monetary (interest rates) or fiscal (taxes and government spending) policy to inject cash into the nation’s financial system.
Technically, economists define a recession as a prolonged period of economic decline, often precipitated by two consecutive quarters of negative GDP growth.
This economic yardstick also is used to indicate a country’s general standard of living. The better a country can produce the goods and services that its residents and businesses use, the more capital is infused back into the country. Therefore, higher GDP levels indicate a more prosperous nation and a relatively higher standard of living among its residents.
The GDP doesn’t just gauge domestic economic health. It serves as a comparison measure to other countries. This is particularly important during periods of growth and decline when the United States can track how well it responds to global economic factors relative to other countries.
## Current Trendline
According to the Bureau of Economic Analysis, first-quarter real GDP closed at 3.1 percent. In the second quarter, real GDP fell to 2.0 percent. The advanced assessment for the third quarter of 2019 is 1.9 percent.
---
### [Creative Alternatives to Traditional Retirement](https://independentadvisorsnw.com/homepage/education/creative-alternatives-to-traditional-retirement/)
**Published:** September 20, 2021
**Author:** Investment Advisor
**Content:**
Carve Your Own Path & Create Your Dream Retirement Goran Ognjenovic // Independent Investment Advisors
[CONTACT ME](#contact-section)
# **Carve Your Own Path** & Create Your Dream Retirement
## *How often do you think about retirement?*
Most of us think about it a lot — at least four times a week.1
We think about when we'll retire and how we'll spend our time in retirement.2,3
As exciting as that can be, it can also be nerve-racking to think about trying to fill up all of that free time.
And no matter what we dream of, the reality of retirement doesn't always match our expectations.1
In fact, nearly half of us miss the mark on when we expect to retire. Most folks who get it wrong [end up retiring years](https://independentadvisorsnw.com/homepage/education/end-of-year-financial-checkup/) earlier than they expected.2
And that's just one miscalculation...
We also tend to underestimate our psychological needs and our options for enjoying our retirement.4
That can make it more difficult to adjust to retirement. It can also leave us feeling unhappy and dissatisfied with the retired life we worked so hard for.
So, how can we make better plans and enjoy a truly rewarding retirement?
We can start by stepping outside of the box of convention and considering some alternatives to traditional retirement.
These novel approaches can open up new paths to growth, happiness, and deeper satisfaction in our next phase of life.
*Not receiving our newsletter?
Get insightful info on finances and more in your inbox every month with the*
### VISUAL INSIGHTS NEWSLETTER
Contact me by FAX only?
## 6 Creative Paths to Retiring on Your Own Terms
### Phased Retirement
Ease into life as a retiree instead of abruptly ending your career. With phased retirement, you can scale back your hours, limit your work to certain projects, or work as a consultant. You can also become a mentor and pass on your knowledge to the next generation.5 Not all employers offer phased retirement options. However, more and more are considering it because they're enjoying benefits such as lower training costs.6
#### Is it right for me?
Phased retirement can be ideal if you are passionate about your career and you want to stay connected to an industry or business. You may also want to consider this alternative if you want to keep earning some income or retain certain benefits from an employer while transitioning into retirement.

### Part-Time or Seasonal Work in Retirement
Pick up a part-time job to explore new interests and learn new skills. Like phased retirement, part-time retirement gives you the chance to continue earning while releasing you from the stress of the 9-to-5 grind. It can involve gig work, seasonal jobs, and even consulting work. Part-time retirement is popular these days, and there are plenty of opportunities for older workers to pick up part-time jobs.7 In fact, more than 2 in 5 folks say they plan to work part-time when they retire.8
#### Is it right for me?
If you want to get out of the house or earn a little money doing something you enjoy, part-time retirement could be a good fit for you. This is also a nice alternative when an employer doesn't offer phased retirement, but you still want to work a bit while easing into full retirement.

### Sabbaticals & Mini-Retirements
Take a sabbatical from your career to test out retirement. Give yourself a few months or even a few years to step away from your job and totally immerse yourself in something new and exciting. Whether you try it once or several times during your career, a sabbatical can give you the chance to get some healthy distance from the day-to-day of your job while nourishing other interests.
#### Is it right for me?
If you're looking for new adventures and opportunities in retirement, a sabbatical can give you a taste of what's to come. In fact, this route can offer a preview of what a new career, business, or educational experience could be like when you retire.

### Passion Projects in Retirement
Embrace the pursuits you deeply [care about by taking up passion projects in retirement](https://independentadvisorsnw.com/borrowing-from-your-retirement-plan-new-cares-act-rules/). You can volunteer to support causes or organizations. You can also learn new skills or join social groups related to the things you care most about. With this alternative, your personal interests replace your career, and they can keep your time filled with purpose. Most retirees can start a passion project as soon as they know what they want to do or turn a hobby into a full-time activity. There aren't any rules here, and you may only be limited by your imagination.
#### Is it right for me?
Any retiree can focus some of their time on activities or projects they're passionate about. The great thing about passion projects is that they can be as active, social, or personal as you want.

### Encore Career in Retirement
Not ready to leave full-time work? Stage the next act of your career by leaving your old job behind for something totally new. With an encore career, you can focus on work that gives you a true sense of purpose, instead of just a paycheck. You may also want to work for yourself and start your own business. Some fields are better suited for encore careers than others. In fact, it's usually easier to start a new career when you choose something related to your skill set or you find an option with a fast-tracked training program.
#### Is it right for me?
An encore career can be a smart choice if you love to learn or if there's something you've always wanted to do but never had the chance. This route may also be good for folks who want to keep working but not necessarily in the same way or in the same industry as they did previously.

### School Dreams in Retirement
Enroll in college, a university, or a trade school and start taking classes that excite you. You can go the traditional education route, but there are also programs fully dedicated to learners over 50.9 Plus, you can explore in-person and online courses, and you don't have to commit to semester- or year-long options. Going to seminars and taking fast-track courses can be other options for living out your school dreams in retirement.
#### Is it right for me?
You may want to live out your school dreams in your golden years if you love to learn, you want to earn a new degree, or you want to take a step towards an encore career. This is also a good option for folks who never got the chance to experience or finish college.

"Retirement isn't about crossing some imaginary finish line. It's about carving your own path for the future."
FINANCIAL LESSON
## Tailor Your Retirement to Fit Your Needs & Live Out Your Dreams
Retiring is a goal most folks share.1 It’s baked into the American dream, and most of us dream about it for years, maybe even decades.1,10
As common as that goal is, it doesn’t necessarily mean we have to share the same vision for retirement.
The truth is retirement isn’t about crossing some imaginary finish line or closing the door on work for the rest of your life.
It doesn’t have to be an all-or-nothing venture. And it doesn’t have to follow the same path as anyone else. In fact, you don’t even have to go with the same program year after year.
It can be easy to forget all that and get tunnel vision with conventional thinking about retirement.
But that just offers one option, and it’s not always the ideal path to fulfillment.
When we’re able to look past convention, we can start to see some better alternatives. They could help us transition into retirement more easily and adjust to it better.11
And may even help us discover more meaningful ways to invest our time and stay connected to the things we love when we retire. If we can do that, our next phase can be deeply enriching and far more satisfying than we may have ever imagined.12
Sincerely,
**Goran Ognjenovic**
Independent Investment Advisors
https://independentadvisorsnw.com
(971) 350-8068
P.S. Sign up for my emails. My subscribers get my best insights.


Goran Ognjenovic
Independent Investment Advisors
[## \#
### (971) 350-8068
]() [## @
### Email Me
](mailto:info@independentadvisorsnw.com) [## w
### Visit Website
](https://independentadvisorsnw.com)
*Not receiving our newsletter?
Get insightful info on finances and more in your inbox every month with the*
### VISUAL INSIGHTS NEWSLETTER
Contact me by FAX only?

Goran Ognjenovic
Independent Investment Advisors
https://independentadvisorsnw.com
(971) 350-8068
1 -
2 - [https://www.ebri.org/docs/default-source/rcs/2020-rcs/rcs\_20-fs-2.pdf?sfvrsn=ffbc3d2f\_8](https://www.ebri.org/docs/default-source/rcs/2020-rcs/rcs_20-fs-2.pdf?sfvrsn=ffbc3d2f_8)
3 -
4 -
5 -
6 -
7 - [https://www.aarp.org/work/job-search/info-2020/part-time-jobs-for-retirees.html](https://www.aarp.org/work/job-search/part-time-jobs-for-retirees/)
8 - [https://www.transamericacenter.org/docs/default-source/retirement-survey-of-workers/tcrs2019\_sr\_19th-annual\_worker\_compendium.pdf](https://www.transamericacenter.org/docs/default-source/retirement-survey-of-workers/tcrs2019_sr_19th-annual_worker_compendium.pdf)
9 -
10 -
11 - [https://academic.oup.com/workar/article/4/4/352/4563363#121756125](https://academic.oup.com/workar/article/4/4/352/4563363?login=false#121756125)
12 -
Risk Disclosure: Investing involves risk including the potential loss of principal. No investment strategy can guarantee a profit or protect against loss in periods of declining values. Past performance does not guarantee future results.
This material is for information purposes only and is not intended as an offer or solicitation with respect to the purchase or sale of any security. The content is developed from sources believed to be providing accurate information; no warranty, expressed or implied, is made regarding accuracy, adequacy, completeness, legality, reliability, or usefulness of any information. Consult your [financial professional before making any investment](https://independentadvisorsnw.com/solutions/financial-investment-solutions-for-small-business-owners/) decision. For illustrative use only.
The following posts and commentary are to be used solely as educational tools and do not contain investment advice. Investment advice must be tailored to a particular investor’s specific needs. None of the information contained should be construed to be investment advice. Individuals wishing to tailor a plan to their own needs should seek the help of a Registered Investment Advisor.
There is a high degree of risk in investing and trading. Independent Investment Advisors assumes no responsibility. Principles of Independent Investment Advisors may, at times, maintain directly or indirectly, positions in securities or derivatives mentioned in these comments.
## Become a Market Insider!
##### Get insightful updates on markets and the world delivered straight to your inbox every month.
Contact me by FAX only?
[No thanks](#)
## You're Signed Up!

Goran Ognjenovic
Independent Investment Advisors
Stay tuned—an email from me is on its way to your inbox right now.
[CLOSE](#)
[## \#
### (971) 350-8068
]() [## @
### Email Me
](mailto:info@independentadvisorsnw.com) [## w
### Visit Website
](https://independentadvisorsnw.com)
---
### [Financial Literacy Quiz?](https://independentadvisorsnw.com/homepage/education/financial-literacy-quiz/)
**Published:** December 10, 2021
**Author:** Investment Advisor
**Content:**
Can You Beat 93% of Americans on a Financial Literacy Quiz? **Goran Ognjenovic** | Independent Investment Advisors
[**CONTACT ME**](https://independentadvisorsnw.com/homepage/education/financial-literacy-quiz/#contact-section)
 ## Can You Beat 93% of Americans on a
# Financial Literacy Quiz?

What do you really know about finance?
How would you rate your financial literacy?
Most folks say they're very knowledgeable about financial matters.1
***But guess what?***
Only about 1 in 3 folks can score 80% on a simple financial literacy quiz.2
And only 7% answer every question right.2
So, how will you measure up?
Can you beat 93% of your fellow Americans?
***Let's find out and take the financial literacy quiz.3***
*Not receiving our newsletter?*
*Get insightful info on finances and more in your inbox every month with the*
### VISUAL INSIGHTS NEWSLETTER
Contact me by FAX only?
# Test Your Money Smarts with
## 6 Basic Questions About Finance
### QUESTION 1
#### Suppose you have $100 in a savings account earning 2% interest per year. After five years, how much would you have?
1. More than $102
2. Exactly $102
3. Less than $102
4. Don't know
### ANSWER 1: **A**
#### It's **more than $102** due to compounding interest.3
#### The Math: A savings account with $100 and a 2% annual interest rate would earn $2 the first year (an ending balance of $102). Year 2, the $102 would earn $2.04 (an ending balance of $104.04). By year 5, the savings account would grow to $110.41.
How many folks answered:1
Correct: 43%
Incorrect: 11%
Don't know: 45%
### QUESTION 2
#### Imagine that the interest rate on your savings account is 1% per year and inflation is 2% per year. After one year, would the money in the account buy more than it does today, exactly the same, or less than today?
1. More
2. Same
3. Less
4. Don't know
### ANSWER 2: **C**
#### You have **less** due to inflation, the rate at which the prices rise.3 If the inflation rate is greater than the savings interest rate, your buying power will not keep up with inflation.
How many folks answered:1
Correct: 55%
Incorrect: 22%
Don't know: 21%
### QUESTION 3
#### If interest rates rise, what will typically happen to bond prices? Rise, fall, stay the same, or is there no relationship?
1. Rise
2. Fall
3. Stay the same
4. No relationship
5. Don't know
### ANSWER 3: **B**
#### When interest rates rise, bond prices **fall** (and vice versa).3 This is because rising interest rates bring newer bonds to market. The newer bonds pay higher interest yields than older bonds, making those older bonds worth less.
How many folks answered:1
Correct: 26%
Incorrect: 37%
Don't know: 36%
### QUESTION 4
#### True or false: A 15-year mortgage typically requires higher monthly payments than a 30-year mortgage but the total interest over the life of the loan will be less.
1. True
2. False
3. Don't know
### ANSWER 4: **A**
#### Assuming the same interest rate for both, **you pay less in interest** for a 15-year loan because you repay the principal faster.3 That's also why the **monthly payment for a 15-year loan is higher.**
#### The Math: With a 30-year mortgage at 6% on a $150,000 home, you pay $899/month in principal and interest charges. Over 30 years, that's $173,757 in interest alone. A 15-year mortgage will cost you nearly $100,000 less — $1,266/month but only $77,841 in total interest.
How many folks answered:1
Correct: 73%
Incorrect: 9%
Don't know: 17%
### QUESTION 5
#### True or false: Buying a single company's stock usually provides a safer return than a stock mutual fund.
1. True
2. False
3. Don't know
### ANSWER 5: **B**
#### A stock mutual fund lets you diversify\*.3 **In general, that makes a stock mutual fund less risky** than a single stock because you can spread your risk by spreading your investments. With a single stock, all your eggs are in one basket.
How many folks answered:1
Correct: 43%
Incorrect: 11%
Don't know: 45%
### QUESTION 6
#### Suppose you owe $1,000 on a loan and the interest rate you are charged is 20% per year compounded annually. If you didn't pay anything off, at this interest rate, how many years would it take for the amount you owe to double?
1. <2 years
2. 2 to 4 years
3. 5 to 9 years
4. 10+ years
5. Don't know
### ANSWER 6: **B**
#### Compound interest would double the debt in **less than five years.**3
#### The rule of 72: In finance, this rule is a way to estimate an investment's doubling time. Divide the rule number (i.e., 72) by the interest percentage per period (usually years) to obtain the approximate number of periods for doubling. Using the rule, it would be about 3.6 years, which makes the correct answer **"2 to 4 years."**
How many folks answered:1
Correct: 30%
Incorrect: 42%
Don't know: 26%
[ Previous ](https://independentadvisorsnw.com/homepage/education/financial-literacy-quiz/#questions-carousel)1.
2.
3.
4.
5.
6.
[ Next ](https://independentadvisorsnw.com/homepage/education/financial-literacy-quiz/#questions-carousel)
*How'd you do? It's never too late to learn and level up your money smarts.*
 #### FINANCIAL LESSON
## Your Quiz Score Doesn't Matter as Much as Your Willingness to Learn

How did you do on the quiz?
Were you surprised by any of the questions — or answers?
It's OK if you couldn't get every question right. You don't have to know everything – few people do.
In fact, these days, more folks are missing more questions on this quiz than they did about 10 years ago.1
And that's not because they're dumb.
Actually, there are a couple of good reasons why many don't do so hot on this quiz.
One is that times have changed. In the 80s, inflation was rampant, and interest rates exploded. So, more folks back then were more familiar with these concepts.1
Two, most folks (more than 4 in 5) never get a formal education on finances.1
They learn from family, experience, and trial and error.
The good news?
It's never too late to learn and level up your money smarts.
Goran Ognjenovic
Independent Investment Advisors
https://independentadvisorsnw.com
(971) 350-8068
P.S. Sign up for my emails. My subscribers get my best insights.

Goran Ognjenovic
Independent Investment Advisors
[## 
### (971) 350-8068
]() [## 
### Email Me
](mailto:info@independentadvisorsnw.com) [## 
### Visit Website
](https://independentadvisorsnw.com)
*Not receiving our newsletter?*
*Get insightful info on finances and more in your inbox every month with the*
### VISUAL INSIGHTS NEWSLETTER
Contact me by FAX only?

Goran Ognjenovic
Independent Investment Advisors
https://independentadvisorsnw.com
(971) 350-8068
---
Sources:
1 - [https://www.usfinancialcapability.org/downloads/NFCS\_2018\_Report\_Natl\_Findings.pdf](https://finrafoundation.org/knowledge-we-gain-share/nfcs)
2 - [https://www.usfinancialcapability.org/results.php?region=US](https://finrafoundation.org/knowledge-we-gain-share/nfcs)
3 - [https://www.usfinancialcapability.org/quiz.php](https://finrafoundation.org/knowledge-we-gain-share/nfcs)
\*Diversification cannot guarantee a profit or protect against loss in periods of declining values. No investment strategy can guarantee success in all market conditions.
Risk Disclosure: Investing involves risk including the potential loss of principal. No investment strategy can guarantee a profit or protect against loss in periods of declining values. Past performance does not guarantee future results.
This material is for information purposes only and is not intended as an offer or solicitation with respect to the purchase or sale of any security. The content is developed from sources believed to be providing accurate information; no warranty, expressed or implied, is made regarding accuracy, adequacy, completeness, legality, reliability, or usefulness of any information. Consult your financial professional before making any investment decision. For illustrative use only.
The following posts and commentary are to be used solely as educational tools and do not contain investment advice. Investment advice must be tailored to a particular investor’s specific needs. None of the information contained should be construed to be investment advice. Individuals wishing to tailor a plan to their own needs should seek the help of a Registered Investment Advisor.
There is a high degree of risk in investing and trading. Independent Investment Advisors assumes no responsibility. Principles of Independent Investment Advisors may, at times, maintain directly or indirectly, positions in securities or derivatives mentioned in these comments.
## Become a Market Insider!
##### Get insightful updates on markets and the world delivered straight to your inbox every month.
Contact me by FAX only?
[No thanks](https://independentadvisorsnw.com/homepage/education/financial-literacy-quiz/#)
## You're Signed Up!

Goran Ognjenovic
Independent Investment Advisors
Stay tuned—an email from me is on its way to your inbox right now.
[CLOSE](https://independentadvisorsnw.com/homepage/education/financial-literacy-quiz/#)
[## 
### (971) 350-8068
]() [## 
### Email Me
](mailto:info@independentadvisorsnw.com) [## 
### Visit Website
](https://independentadvisorsnw.com)
---
### [Give Smarter & Make a Greater Impact with Philanthropy](https://independentadvisorsnw.com/homepage/education/give-smarter-make-a-greater-impact-with-philanthropy/)
**Published:** January 7, 2022
**Author:** Financial Planner
**Content:**
---
Give Smarter & Make a Greater Impact with Philanthropy **Goran Ognjenovic** • Independent Investment Advisors
[**CONTACT ME**](https://independentadvisorsnw.com/homepage/education/give-smarter-make-a-greater-impact-with-philanthropy/#contact-section)

# Give Smarter & Make a Greater Impact with Philanthropy
What inspires you to give?
Most of us give for the same basic reasons.
We want to help others, make a positive difference in the world—and giving feels good. It makes us happy, and it connects us to the causes we care about.1
Studies show that most charitable folks give according to their values or to support causes they care about.2
But they don’t always have a strategy around giving. Or a way to monitor for impact.
How do you make the greatest impact with your giving?
If you’re not sure, you’re not alone. Many folks are passionate about giving but don’t have a defined strategy.
Even though strategic giving can pave the way for thoughtful donations of money, time, and resources. And that can help you figure out how to do the most good for the causes that matter most to you.
Want to create your own charitable strategy?
Check out the questions below to help create your own giving roadmap.
*Not receiving our newsletter?*
*Get insightful info on finances and more in your inbox every month with the*
### VISUAL INSIGHTS NEWSLETTER
Contact me by FAX only?
# 5 Questions to Focus Your Giving & Make an Even Greater Impact
###### •1•
## What Values Are Most Important to Me?
**What am I deeply passionate about? What motivates me day to day?**
Family, faith, or social causes may come to mind. Your life experiences may also drive your values and motivations. Think about how to align them with your philanthropy.
###### •2•
## Where Can I Do the Most Good?
**What causes don't get enough support? Where could my gifts make a bigger splash?**
Get specific. Think about narrower aspects of a bigger cause or issue. You can also think more locally, finding smaller organizations that support those issues in your community.
###### •3•
## Which Organizations Address the Issue(s) I Want to Support?
**Which organizations are most effective at solving the problem(s) you want to address? How transparent are they?**
Do your due diligence before giving. Whether you go with a new or established organization, focus on groups that know what they're doing — and that clearly tell you how your philanthropy will make a difference. Independent organizations such as Charity Navigator and GuideStar can help you identify organizations that use donations wisely.
###### •4•
## What Exactly Do I Want to Donate?
**How much money can I afford to give? What else could I give to support a cause or organization?**
Beyond cash and your budget for philanthropy, consider other ways to donate. Appreciated assets, time, and your distinctive skills could all be valuable and impactful to the causes you care about.
###### •5•
## What Does Success Look Like?
**What changes do I want to see? What impact do I expect from my donations? How do I evaluate success?**
Supporting a cause isn't always enough to make a real change in the world. You also need a clear vision of what success looks like to you. If you know what outcome you want to achieve, you can support an organization that approaches a cause in ways that mirrors your vision of success.

Giving for impact is a practice that can help change the world.
#### FINANCIAL LESSON
## How to Refine Your Giving Strategy for Higher-Impact Philanthropy
I’ve seen first-hand how the joy of giving and making an impact through philanthropy can change your life.
When we give, we activate our brain’s pleasure centers. That’s one reason why philanthropy can feel so great.
Creating a values-based strategy can not only increase the satisfaction of giving, but also help create greater change in the world.
When we look inward and think carefully about why we want to give and what we really want to achieve, we can get a clear idea of our motivations and goals for philanthropy.
And, we can start harnessing the financial and tax benefits of giving.
Want help incorporating more philanthropy into your financial life? I’m here to help.
Goran Ognjenovic
Independent Investment Advisors
https://iiaproduction.wpengine.com
(971) 350-8068
P.S. Sign up for my emails. My subscribers get my best insights.

Goran Ognjenovic
Independent Investment Advisors
[## 
### (971) 350-8068
]() [## 
### Email Me
](mailto:info@independentadvisorsnw.com) [## 
### Visit Website
](https://independentadvisorsnw.com)
*Not receiving our newsletter?*
*Get insightful info on finances and more in your inbox every month with the*
### VISUAL INSIGHTS NEWSLETTER
Contact me by FAX only?

Goran Ognjenovic
Independent Investment Advisors
(971) 350-8068
https://iiaproduction.wpengine.com
---
Sources:
[https://scholarworks.iupui.edu/bitstream/handle/1805/26654/bank-america-sept21.pdf?sequence=1&isAllowed=y](https://scholarworks.iupui.edu/server/api/core/bitstreams/ff2ebcdc-fe48-41fe-baf9-6437b62f8bfa/content)
Risk Disclosure: Investing involves risk including the potential loss of principal. No investment strategy can guarantee a profit or protect against loss in periods of declining values. Past performance does not guarantee future results.
This material is for information purposes only and is not intended as an offer or solicitation with respect to the purchase or sale of any security. The content is developed from sources believed to be providing accurate information; no warranty, expressed or implied, is made regarding accuracy, adequacy, completeness, legality, reliability, or usefulness of any information. Consult your financial professional before making any investment decision. For illustrative use only.
This information is not intended to be a substitute for specific individualized tax advice. We suggest that you discuss your specific tax issues with a qualified tax professional.
The following posts and commentary are to be used solely as educational tools and do not contain investment advice. Investment advice must be tailored to a particular investor’s specific needs. None of the information contained should be construed to be investment advice. Individuals wishing to tailor a plan to their own needs should seek the help of a Registered Investment Advisor.
There is a high degree of risk in investing and trading. Independent Investment Advisors assumes no responsibility. Principles of Independent Investment Advisors may, at times, maintain directly or indirectly, positions in securities or derivatives mentioned in these comments.
## Become a Market Insider!
##### Get insightful updates on markets and the world delivered straight to your inbox every month.
Contact me by FAX only?
[No thanks](#)
## You're Signed Up!

Goran Ognjenovic
Independent Investment Advisors
Stay tuned—an email from me is on its way to your inbox right now.
[CLOSE](#)
[## 
### (971) 350-8068
]() [## 
### Email Me
](mailto:info@independentadvisorsnw.com) [## 
### Visit Website
](https://independentadvisorsnw.com)
---
### [Future and Now Costs](https://independentadvisorsnw.com/homepage/education/future-and-now-costs/)
**Published:** November 19, 2021
**Author:** Financial Planner
**Content:**
Inflation: What Your Bills Could Look Like in 2030 **Goran Ognjenovic** // Independent Investment Advisors
[**CONTACT ME**](https://independentadvisorsnw.com/homepage/education/future-and-now-costs/#contact-section)
# What Your Bills Could Look Like in
## 2030

Sticker shock at the grocery store? Price hikes at the pumps?
Prices are going up and spending more for basics can be startling.
Do you remember the first time you noticed prices increasing? It often happens so gradually that we don’t even notice.
Inflation is often more complicated than we realize and it’ll be with us for the rest of our lives.
So, what could prices look like in 2030?
Let's find out by looking at some historical data, and projecting how prices for things like food and housing could go up.
*Not receiving our newsletter?*
*Get insightful info on finances and more in your inbox every month with the*
### VISUAL INSIGHTS NEWSLETTER
Contact me by FAX only?
# Sticker Shock?
## How your bills will be higher in 2030...

### What Is Inflation?
Inflation is a measurement of how fast the prices of goods and services increase. As inflation rises, prices do too because it takes more dollars to buy the same things. Deflation is the opposite — it brings lower prices and more buying power.
Both inflation and deflation are tied to a complex web of economic factors — such as supply and demand, wages, government spending, taxes, and more.
The Consumer Price Index (CPI) is a useful indicator of inflation or deflation. It's sort of a cost-of-living index, looking at price changes, over time, for the goods and services used by households.
The prices and predictions that follow are based on historical averages going back to 2000 for different areas of spending.

### Housing
**Average annual inflation rate: 2.39%**1
Housing could be almost 27% more expensive by 2030.1 That means a house that costs $400,000 today could run you $506,388 in 10 years.
Depending on where you're buying in the future, you could be paying much more than that. In fact, by 2030, the average home in Washington state will probably run you $782,708.2
If you prefer the Aloha state, expect to fork over $889,627 for an average home. And topping the list for the fastest rising housing prices is California, where the average home will likely cost more than $1 million by 2030.2

### Food & Beverage
**Average annual inflation rate: 2.33%**3
Food and drinks may be about 26% more expensive by 2030.3 That means a trip to the grocery store that costs you $250 now could set you back more than $314.3
If you like fresh fruit, your grocery bills could climb higher even sooner. That's because prices for fresh fruit have been rising at about twice the pace of meat, poultry, and fish.4
As food costs across the board continue to rise, they may not be the only thing about your food purchases that change by 2030. Your diet could, too. In fact, by 2030, more folks may give up red meat, replacing it with poultry and dairy products.5

### Health Care
**Average annual inflation rate: 1.83%**6
Health care could be 20% more expensive by 2030.6 That means care costing you $5,000 today could cost you ~$6,000 in 10 years.6
In 2021, a retired couple was projected to need $300,000 in savings to cover health care in retirement. In 2030, those costs could rise to over $350,000.7

### Gas & Transportation
**Average annual inflation rate: 1.38%**8
Fuel and transportation are likely to be nearly 15% more expensive by 2030.8 That means a car that costs $40,000 now could run you $45,858 in 10 years.8
However, electric vehicles (EVs) could act as a price disruptor. There could be as many as 145 million EVs on the road by 2030.9
Plus, some carmakers are working to cut the cost of batteries for EVs in half by 2030.10 Paired with self-driving technology, the transportation industry could look completely different in the next 10 years.

### College
**Average annual inflation rate: 4.93%**11
A public four-year university may be about 62% more expensive by 2030.11 Annual tuition and fees of $4,000 today for a two-year college could cost $6,324 by 2030.11
For a four-year public university that runs you $20,000 today, you're looking at $32,376 within 10 years.5 And a private four-year university cost of $44,000 could increase to $68,022 by 2030.11
However, the higher education industry is being massively disrupted by virtual learning and changing educational preferences. Within 10 years, these and other factors are bound to change, making higher education costs challenging to predict.
*"Like many things in life and money, inflation isn't always bad."*
#### FINANCIAL LESSON
## Inflation Is Inevitable, So Figure Out How to Take Advantage of It
Inflation affects far more than upfront prices. It shakes up the costs of doing business and borrowing money. And it can affect savings, bonds, and plans for the future.
We often don’t notice these changes year to year, though.
That’s because inflation comes in small doses. A few bucks more here, a couple hundred more there — it creeps up over time.
And it’s the reason why inflation has a well-deserved reputation as a “silent killer.”
Still, like many things in life and finance, inflation isn’t all bad.
When steady and predictable, a moderate amount can be good as it can signal a healthy, growing economy.
Inflation causes problems when it increases suddenly and rapidly. Or when folks haven’t planned for future price increases.
Have questions about how inflation works or what it means for you? I’m here to help.
Goran Ognjenovic
Independent Investment Advisors
https://independentadvisorsnw.com
(971) 350-8068
P.S. Sign up for my emails. My subscribers get my best insights.

Goran Ognjenovic
Independent Investment Advisors
[## 
### (971) 350-8068
]() [## 
### Email Me
](mailto:info@independentadvisorsnw.com) [## 
### Visit Website
](https://independentadvisorsnw.com)
*Not receiving our newsletter?*
*Get insightful info on finances and more in your inbox every month with the*
### VISUAL INSIGHTS NEWSLETTER
Contact me by FAX only?

Goran Ognjenovic
Independent Investment Advisors
https://independentadvisorsnw.com
(971) 350-8068
Sources:
1 - (Annual average)
2 - [https://magazine.realtor/daily-news/2020/10/27/what-will-homes-be-worth-in-10-years](https://www.nar.realtor/magazine/real-estate-news/economy/what-will-homes-be-worth-in-10-years)
3 - (Annual average)
4 -
5 - [https://www.bloomberg.com/news/articles/2021-07-05/consumers-to-get-relief-from-surging-food-costs-in-coming-years](https://www.bloomberg.com/tosv2.html?vid=&uuid=aa977079-8ce7-11ee-96a6-7972733bb8e8&url=L25ld3MvYXJ0aWNsZXMvMjAyMS0wNy0wNS9jb25zdW1lcnMtdG8tZ2V0LXJlbGllZi1mcm9tLXN1cmdpbmctZm9vZC1jb3N0cy1pbi1jb21pbmcteWVhcnM=)
6 - [https://fred.stlouisfed.org/series/WPU51 ](https://fred.stlouisfed.org/series/WPU51)(Annual average)
7 -
8 - (Annual average)
9 -
10 - [https://www.greencarreports.com/news/1131589\_vw-targets-50-cut-in-battery-costs-by-2030-transition-to-solid-state-tech](https://www.greencarreports.com/news/1131589_vw-targets-50-cut-in-battery-costs-by-2030-transition-to-solid-state-tech)
11 - (Current Dollars Public Two-Year Tuition and Fees, Public Four-Year Tuition and Fees and Room and Board, Private Nonprofit Four-Year Tuition and Fees and Room and Board)
These hypothetical examples are for informational use only and are based on historical data. Past performance is no indication of future results. Projected future prices are derived by calculating the compound annual growth rate of average annual prices between 2000 and 2020 (2010 and 2020 for health care) and applying it to a 10-year future period.
Risk Disclosure: Investing involves risk including the potential loss of principal. No investment strategy can guarantee a profit or protect against loss in periods of declining values. Past performance does not guarantee future results.
This material is for information purposes only and is not intended as an offer or solicitation with respect to the purchase or sale of any security. The content is developed from sources believed to be providing accurate information; no warranty, expressed or implied, is made regarding accuracy, adequacy, completeness, legality, reliability, or usefulness of any information. Consult your financial professional before making any investment decision. For illustrative use only.
This information is not intended to be a substitute for specific individualized tax advice. We suggest that you discuss your specific situation with a qualified tax professional.
The following posts and commentary are to be used solely as educational tools and do not contain investment advice. Investment advice must be tailored to a particular investor’s specific needs. None of the information contained should be construed to be investment advice. Individuals wishing to tailor a plan to their own needs should seek the help of a Registered Investment Advisor.
There is a high degree of risk in investing and trading. Independent Investment Advisors assumes no responsibility. Principles of Independent Investment Advisors may, at times, maintain directly or indirectly, positions in securities or derivatives mentioned in these comments.
## Become a Market Insider!
##### Get insightful updates on markets and the world delivered straight to your inbox every month.
Contact me by FAX only?
[No thanks](https://independentadvisorsnw.com/homepage/education/future-and-now-costs/#)
## You're Signed Up!

Goran Ognjenovic
Independent Investment Advisors
Stay tuned—an email from me is on its way to your inbox right now.
[CLOSE](https://independentadvisorsnw.com/homepage/education/future-and-now-costs/#)
[## 
### (971) 350-8068
]() [## 
### Email Me
](mailto:info@independentadvisorsnw.com) [## 
### Visit Website
](https://independentadvisorsnw.com)
---
### [Business Owner Exit Planning](https://independentadvisorsnw.com/homepage/education/business-owner-exit-planning/)
**Published:** October 8, 2021
**Author:** Investment Advisor
**Content:**
---
Business Escape Plan? 3 Steps to Your Dream Exit WITHOUT Compromising Your Life’s Work Would you like help creating your dream exit? [Book a **FREE 1-on-1 Business Escape Planning Session**](https://independentadvisorsnw.com/homepage/education/business-owner-exit-planning/#scroll-reference) ## BUSINESS
ESCAPE
PLAN?
### 3 STEPS TO YOUR DREAM EXIT **WITHOUT** COMPROMISING YOUR LIFE’S WORK
You’ve got that little voice in the back of your mind telling you it’s time for the next adventure.
You’ve put in thousands upon thousands of hours of your blood, sweat, and tears to build your business into something incredible. You’ve carefully crafted your business into what you wanted it to be. It’s been like raising a child. Years later, you’re proud of it because you’ve “raised” it right.
But there’s one BIG problem.
You’re wondering, what’s next? Although you might be experiencing mixed emotions about moving on, breaking free of your work is starting to sound more and more enticing. All the trips you haven’t been able to take and the family time sacrificed to the business are beginning to weigh on you.
**Of course, you’ve got concerns about leaving your life’s work behind.** Can you make sure that the values you worked so hard to instill don’t get lost in the transition? What about your employees and your clients? While you want to make sure that they’re taken care of, at the same time, you can’t cut yourself loose with nothing to show for it. **You expect your business to fund your future.**
**Just as you planned meticulously for a variety of situations as you built your business, you need to approach your exit in a methodical way.** Although it sounds easy, it seems to be stressful, and even painful, for many business owners. In a recent survey, only about one-third of family-owned businesses had a succession plan in place.1 Whether you’re selling to family or not, you ***need*** a plan of action to ensure that you make the right decisions and have thought through the consequences.
You may have already been thinking about how to make the transition. Or maybe recent events have changed your perspective on how much time you want to spend on your work. Either way, you’re looking for a win-win strategy that balances your need for financial freedom and your company’s need for new growth and stability.
**If you’re dreaming about passing your enterprise on to others and enjoying a new life outside your business, you’ve come to the right place.**
This pivotal guide was ***designed specifically for accomplished business owners like you,*** who are searching for a way to reap some of the rewards from their life’s work. At the same time, you want to ensure the values, mission, and procedures are in place so your clients and staff aren’t left hanging when you’re gone.
**As a successful business owner contemplating your ideal exit, you’re likely asking yourself questions such as:**
- *How much is my business worth?*
- *How do I ensure that my clients and staff will be taken care of?*
- *Am I aware of all the options available to me when it comes to profiting from my business?*
- *What are the consequences, financial and otherwise, of my choices?*
- *Who do I trust to help me plan my exit?*
**If these questions resonated with you, keep reading…**
Would you like help creating your dream exit?
[Book a **FREE 1-on-1 Business Escape Planning Session**](https://independentadvisorsnw.com/homepage/education/business-owner-exit-planning/#scroll-reference)
###### STEP 1
# Define Your Dream Exit

While there are plenty of resources that provide an overview on business succession planning in general, it’s not as easy to find information that applies specifically to you and your needs, as well as your firm’s requirements. **When it comes to the ideal exit, there’s no such thing as “one size fits all.”**
When you were building your company, you probably didn’t just throw tactics at the market to see what worked! Otherwise you wouldn’t have been so successful. Instead, you first determined what it was that you wanted to achieve. Then you put together a blueprint to put all the pieces in place, along with a timeline for each phase.
In the beginning, your main goal may have just been to bring in enough income to stay afloat. As your business began to grow, your blueprint changed. You’re now at the point where it needs to change again. **Your first step is to decide what that new goal is.**
You probably want your existing customers to be well taken care of, whatever that means to you. In addition, you would probably like to reward the workers who’ve been by your side during the difficult times, or keep everyone employed.
**Of course, you need to make sure that you and your family are financially taken care of.** Maybe you’d like to take some profit off the top in order to pay off debt or put kids through college. On the other hand, maybe you’re finished working and want to spend all your time with friends, family, and hobbies you enjoy.
The way you grew your company was specific to your own values and how you wanted your company to thrive. Now, it’s time for the business to recede into the background, but your strategy still must be customized to your own values and vision.
**Key questions to ask about your dream exit:**
- What does taking care of my clients and staff mean to me?
- What do I need to secure my financial freedom?
- Are there any steps I need to take before beginning the transition?
- Do I have clarity around what I want to achieve with my departure?
- Have I discussed my goal with a trusted and knowledgeable professional?
Would you like help creating your dream exit?
[Book a **FREE 1-on-1 Business Escape Planning Session**](https://independentadvisorsnw.com/homepage/education/business-owner-exit-planning/#scroll-reference)
###### STEP 2
# Choose the Right Escape Hatch

Now that you’ve determined your goals, you can plan your strategy. Your plan must accommodate more than “just” the financials. Maybe you have friends or family who’ve been through a similar transition. **However, that doesn’t mean their arrangement will work for you.**
You may know someone who passed their business on to their children. If your kids aren’t willing and able to take over your company, that’s not an option for you. Even if you really wish it were.
Fortunately, you have other options. You might have a second-in-command that is poised to take over. Maybe you’re considering selling to your employees. Or you’re willing to find a third-party buyer instead.
Consider how your exit fits into your personal financial plan. If your future rests on your income until you stop working at a certain age, how will you manage if you stop working now? **Is there enough value in the company to support your lifestyle?**
**Another aspect of your strategy to consider is how much of an exit you’re planning.** Will you completely close the door behind you? Or would you prefer to leave the door open, which permits you to take out some equity and potentially reduce your responsibilities?
**As you probably expect, different approaches result in different tax consequences.** Selling a firm means selling all its assets, not just one business entity. Some company components enjoy capital gains treatment upon sale, while others are taxed as ordinary income.2 Depending on how the deal is structured, you may enjoy greater tax savings with one strategy over another.
Relationships are a factor that often complicates planning. Are there dynamics within the family that must be considered? Even if you’re the only one involved in the company, your exit could still stir up some emotions.
**Key questions to ask about your escape hatch:**
- Is there a person or group who’s ready, willing, and able to take over when I leave?
- How involved do I want to be in the business moving forward?
- Am I aware of the tax consequences of my options?
- Have I considered the family or relationship dynamics that could affect my plan?
- Is there anything I’m missing that a knowledgeable professional could discuss with me?
Would you like help creating your dream exit?
[Book a **FREE 1-on-1 Business Escape Planning Session**](https://independentadvisorsnw.com/homepage/education/business-owner-exit-planning/#scroll-reference)
###### STEP 3
# Determine When To Pop The Hatch

It takes some time to do the prep work before you break out of your business, even before you start looking for a buyer or engage in serious conversations. On the other hand, you want to be ready to exit on a (financially) high note.
**Developing your strategy and timeline now is critical.** Having everything in place makes it more likely that you’ll be able to take advantage of a favorable market. If you own a seasonal business, you probably don’t want to search for a buyer in the offseason when profits are low or nonexistent. Bear in mind that the actual sale of the company (not including all of your prepping) often takes almost a year.3
**Another advantage to solidifying your approach early is to avoid giving your competitors an advantage.** Otherwise they may swoop in and take clients and/or staff while you’re still figuring out your tactics.
Your timeframe should match your strategy as well. Want to take off in the next couple of years? Avoid strategies that will take you five years to implement.
**Key questions to ask about the timing of your escape:**
- When do I want to stop working full-time at my company?
- Does my strategy match my timeline?
- When is the best time to leave?
- Have I discussed my decision with a knowledgeable professional?
Would you like help creating your dream exit?
[Book a **FREE 1-on-1 Business Escape Planning Session**](https://independentadvisorsnw.com/homepage/education/business-owner-exit-planning/#scroll-reference)
# Envision and Execute Your Exit
As a successful business owner, you put key elements in place in a timely fashion so you could leverage any opportunities you found along the way. When it comes to your business, this may be your last campaign. **Treat it with the same thoughtfulness you brought to growing your company.**
The good news is, it’s entirely possible to retire, partially or fully, from your business and leave it in good hands. At the same time, the value from what you built can provide you with the financial freedom you deserve. **No dream exit is the result of sheer luck.**
**Making the right choices could result in the smooth transition you’re looking for.** Not only does your ideal exit positively affect your finances, but your firm and your family relationships, too. That’s why it’s so critical to understand all the possible outcomes of your options.
**The sooner you develop your strategy, the better.** Once you have it in place, you can take advantage of opportunities that come your way. Otherwise you’re at risk of losing out because you weren’t prepared.
We have the experience and know-how to help you develop your dream exit in a reasonable amount of time. Our solutions are tailored to your specific circumstances. Book your personalized, free **Business Escape Planning Session** today to start building your “escape hatch” blueprint.
**We’ll help you determine what tools you need, and how to create a step-by-step action list that results in a win-win outcome. You’ll understand the tax and other financial consequences of your choices, so you choose the one that works best for you and your business. We’re professionals that help business owners like you develop positive strategies when it’s time for new ownership at the company they’ve founded.**
You’ve already made the wise decision to read through this guide. The next right step is to call or email us now to set up your free Business Escape Planning Session.
#### Would you like help creating your dream exit?
## BOOK A **FREE 1-ON-1 BUSINESS ESCAPE PLANNING SESSION**
Best time to call No Preference Morning Afternoon
Contact me by FAX only?

Goran Ognjenovic
Independent Investment Advisors
(971) 350-8068
info@independentadvisorsnw.com
https://iiaproduction.wpengine.com
Sources:
1 - [https://www.pwc.com/us/en/industries/private-company-services/library/family-business-survey.html](https://www.pwc.com/us/en/services/trust-solutions/private-company-services/library/family-business-survey.html)
2 -
3 -
Risk Disclosure: Investing involves risk including the potential loss of principal. No investment strategy can guarantee a profit or protect against loss in periods of declining values. Past performance does not guarantee future results.
This material is for information purposes only and is not intended as an offer or solicitation with respect to the purchase or sale of any security. The content is developed from sources believed to be providing accurate information; no warranty, expressed or implied, is made regarding accuracy, adequacy, completeness, legality, reliability, or usefulness of any information. Consult your financial professional before making any investment decision. For illustrative use only.
This information is not intended to be a substitute for specific individualized tax advice. We suggest that you discuss your specific tax issues with a qualified tax professional.
The following posts and commentary are to be used solely as educational tools and do not contain investment advice. Investment advice must be tailored to a particular investor’s specific needs. None of the information contained should be construed to be investment advice. Individuals wishing to tailor a plan to their own needs should seek the help of a Registered Investment Advisor.
There is a high degree of risk in investing and trading. Independent Investment Advisors assumes no responsibility. Principles of Independent Investment Advisors may, at times, maintain directly or indirectly, positions in securities or derivatives mentioned in these comments.
---
### [The 3 Pillars of Successful Retirement Plans](https://independentadvisorsnw.com/homepage/education/the-3-pillars-of-successful-retirement-plans/)
**Published:** September 3, 2021
**Author:** Financial Planner
**Content:**
[< back to Investor Education Center](https://independentadvisorsnw.com/homepage/education/)
# The 3 Pillars of Successful Retirement Plans
## A Simple Checklist to Kick-Start Your New Work-Free Life
If you’re within 5 years of retirement, you’re in a critical period – if you take action now, you may still be able to make up for past mistakes and have a successful retirement. The decisions you make now will define your retirement lifestyle and your ability to retire successfully. This checklist is designed to highlight your strengths and weaknesses for retirement preparation.
Go through each step of this checklist and take action. As you go, jot down any questions or concerns you may have and send them to me here. If you’re feeling overwhelmed and want some pro guidance, give my office a call to schedule a chat at the number below.
“A dream doesn’t become reality through magic; it takes sweat, determination, and hard work.” —Colin Powell
### Pillar #1 – A Holistic Income Strategy of Successful Retirement Plans
- I know how much I will need to cover my expenses each month in retirement (~80% of your current monthly budget is a solid estimate).
- I have estimates for how much extra I will spend each year on travel, home improvements, gifts, medical care, and other one-off expenses.
- I have a clear understanding of the guaranteed income I will receive from sources such as Social Security, pensions, annuities, veteran’s benefits, etc.
- I understand that a retired couple could need $300,000+ to cover healthcare expenses after age 65, and my income plan accounts for those expenses.1
- My income strategies account for inflation (if I need $100,000 this year, I will need ~$186,000 in 20 years to have the same quality of life at 3% inflation).
- I understand all my Social Security options and how to maximize my guaranteed lifetime income.
- My spouse and I have coordinated our claiming strategies to help maximize our income.
- Our income strategy helps protect a surviving spouse from loss of income.
- I have adequate liquid cash on hand for emergencies and unexpected expenses so that I’m not forced to liquidate investments.
- A financial professional has looked over my income strategy to identify any problems or mistakes.
### Pillar #2 – A Market Readiness Strategy of Successful Retirement Plans
“Optimism is the faith that leads to achievement. Nothing can be done without hope and confidence.” —Helen Keller
- I have completed a risk questionnaire and understand all the risks I’m taking with my retirement savings.
- I understand that my investing strategy will need to change in retirement so I don’t run out of money later in life.
- My income strategy includes guaranteed income to help protect my lifestyle from market volatility.
- I understand “sequence-of-returns” risk and that withdrawing too much when my portfolio has lost value can have a lasting negative effect on my retirement.
- I have run multiple portfolio scenarios with different growth and inflation assumptions and am confident that my withdrawal needs are “safe.”
- My income plan is flexible, and I’ve planned for the inevitable ups and downs of the stock market.
- A financial professional has reviewed my market plan and assumptions to identify any problems.
### Pillar #3 – A Forward-Thinking Tax Strategy of Successful Retirement Plans
“Nothing in life is to be feared, it is only to be understood. Now is the time to understand more, so that we may fear less.” —Marie Curie
- I have reviewed my strategies in light of recent changes in tax legislation to make sure I’m using every opportunity to potentially lower my taxes now and in the future.
- I understand how Taxable, Tax-Deferred, and Tax-Free wealth buckets work, and my drawdown strategy helps maximize my after-tax income.
- I understand that Medicare and Social Security depend on the future fiscal stability of the U.S.
- I understand that the debt held by the U.S. is expected to break historical records by the 2030s (surpass 100% of GDP) and that my future tax rates are likely to increase.2
- I am staying abreast of changing tax rules and working with a financial professional to proactively plan for future taxes.
Sources & Disclosures
1
2 [https://thehill.com/policy/finance/541675-debt-to-break-wwii-record-by-2031](https://thehill.com/policy/finance/541675-debt-to-break-wwii-record-by-2031/)
Risk Disclosure: Investing involves risk including the potential loss of principal. No investment strategy can guarantee a profit or protect against loss in periods of declining values. Past performance does not guarantee future results.
This material is for information purposes only and is not intended as an offer or solicitation with respect to the purchase or sale of any security. The content is developed from sources believed to be providing accurate information; no warranty, expressed or implied, is made regarding accuracy, adequacy, completeness, legality, reliability, or usefulness of any information. Consult your financial professional before making any investment decision. For illustrative use only.
This information is not intended to be a substitute for specific individualized tax advice. We suggest that you discuss your specific tax issues with a qualified tax professional.
The following posts and commentary are to be used solely as educational tools and do not contain investment advice. Investment advice must be tailored to a particular investor’s specific needs. None of the information contained should be construed to be investment advice. Individuals wishing to tailor a plan to their own needs should seek the help of a Registered Investment Advisor.
There is a high degree of risk in investing and trading. Independent Investment Advisors assumes no responsibility. Principles of Independent Investment Advisors may, at times, maintain directly or indirectly, positions in securities or derivatives mentioned in these comments.
---
### [Overview](https://independentadvisorsnw.com/homepage/overview/)
**Published:** September 18, 2019
**Author:** Investment Advisor
**Content:**
## **What does “Independently Different Wealth Management” mean:**
It means we focus exclusively on a small number of mutually selected, deeply compatible clients. We don’t believe that current industry ratios set by large asset management companies are efficient.
### **Being Independent:**
Being independent means, we are unrestricted in finding the best possible strategies and assets for our clients’ portfolios. There are no corporate influences, incentives, commissions, or kickbacks. Just pure focus on our client’s investment goals and objectives!
It also means we are not a broker-dealer. We are not sellers of financial instruments to our clients that reward any kind of incentives, commissions, or kickbacks. We grow when our client’s portfolios grow!
### **Being Fiduciary:**
Being Fiduciary is very simple to explain. Our clients’ interests come first. Period!
### **Being Non-Custodial:**
Being non-custodial means, we can handpick the best and the most financially reliable prime brokerages and technology providers to safeguard our client’s assets. It also means our clients can have access to an incredible variety of global investments. At the same time, our overhead and therefore our management fees stay conservative.
## Want to learn more about our choice of investment management platforms?
[why interactive brokers](https://www.interactivebrokers.com/en/index.php?f=1338)
[why the fly](https://theflyonthewall.com/)
[why ss&c Realtick](https://www.ezesoft.com/solutions/eze-investment-suite-overview/execution-management-system)
---
### [Sudden Wealth Inheritance](https://independentadvisorsnw.com/homepage/education/sudden-wealth-inheritance/)
**Published:** December 2, 2021
**Author:** Investment Advisor
**Content:**
Coming Into Money? 2 Crippling Risks and 3 Things You MUST Know Would you like help managing the risks and must-dos? [Book a **FREE Sudden Wealth Session**](https://independentadvisorsnw.com/homepage/education/sudden-wealth-inheritance/#inquiry) # Coming Into Money?
## 2 Crippling Risks and 3 Things You MUST Know
You've recently discovered that a significant amount of money is on its way to you, or might even be sitting right now in your bank account. Maybe it's coming from an inheritance, or else it could be something like a lottery win or insurance payout.
Most people might think it's exciting, but you're realizing you've got some mixed feelings about it. It's pretty common to be happy and relieved that you now have more money, and to be stressed out or worried about how you're going to handle it, too.
**You've got choices that you probably didn't have before to make positive changes to your finances.** If you're like many Americans, you've got debt of some kind. Should you pay off all or a portion of it? If you have kids, should all or a portion be set aside for college in some way?
Or instead, maybe this is the time to buy the larger house you've always wanted. Launch your own business and stop working for “the man." Travel the world. Take a work break for a little while.
**Money that comes in suddenly is often spent, seemingly, just as suddenly.** But you don't want to lose all the money you've just come into. Fortunately, you can plan how to work with your windfall without spending it all right away. By avoiding the mistakes that others make and choosing the right options, you have the chance to make dreams come true.
But what are those options and what are the mistakes that lead to all that money slipping right through your fingers? The challenge you're now struggling with is that you don't know what you don't know. The causes of sudden wealth are generally pretty similar. **But the right way to handle it varies from recipient to recipient, according to your own circumstances, desires, and needs.**
Although there is plenty of DIY (do it yourself) money management advice available, protecting and preserving sudden wealth is often more complex. How to invest the money depends on your particular circumstances, the goals you want to fund, and your tolerance for risk.
**One size does not fit all when it comes to managing a windfall!** Asking people who don't have experience with this kind of money management could lead to disaster. In addition to money management, you need to manage expectations, including your own.
**Taking all the obvious (and not so obvious) factors into consideration is the key to developing a strong strategy.** Without knowing all the factors in play, you could end up making the wrong (and potentially expensive) decision.
**If you're trying to figure out how to handle your sudden wealth wisely, then you've come to the right place.**
This guide is created ***especially for people like you who have recently come into significant funds***, to help you determine what the right questions are, so that you can find the right answers for your specific lifestyle and ambitions.
It will help you highlight the risks that could bankrupt your future, and develop a strategy to enjoy your newfound wealth as well.
---
**As the recent recipient of a sudden windfall, you may be asking yourself questions such as:**
- What choices are available to me, and what are their consequences?
- How do I prevent the money from damaging my future and my relationships?
- Will there be enough left after taxes to fully fund my dreams?
- What should I invest the money in?
- Who can I trust to help me manage this money?
***If any of these questions seem familiar, keep reading…***
Would you like help managing the risks and must-dos?
[Book a **FREE Sudden Wealth Session**](https://independentadvisorsnw.com/homepage/education/sudden-wealth-inheritance/#inquiry)
## Crippling Risks
### Crippling Risk #1
#### Unexpectedly High Taxes

To paraphrase George Carlin, Uncle Sam loves you, and he needs money! Taxes are often confusing enough, never mind adding a significant amount of money into the mix. **You're probably already aware that you'll need to pay taxes, but how much should you plan for?**
Federal income taxes are usually not an issue for someone who inherits money.1 However, some states do levy taxes on inheritances, so it depends on where you live. Similarly, some states will withhold state tax on lottery winnings and others don't. However, you usually need to report it as income on your federal income tax return.2 Insurance payouts depend on the type of insurance. Settlements from a lawsuit are often taxable income, though it depends on the type of lawsuit and your personal situation.3
**Not only do your taxes depend on what type of windfall you're benefiting from, they may also depend on when you take the distribution.** In some cases, you may not have a choice in how the money is distributed to you; you will receive a lump sum or regular payouts over a period of time. But in other cases, you may have options in how you take the funds.
**Think objectively about what the personal results are of taking a lump sum versus a structured payout. If you have a spendthrift in your family, will the lump sum be too tempting to spend?** Or will you be able to invest it wisely without taking money out periodically to allow for potential growth?
Your tax issues also depend on where the money is coming from. As you can see, the tax ramifications of your sudden wealth can be more complex than you might originally have thought.
**Critical questions to help you manage your risk include:**
- Can I choose how the money is distributed to me (to reduce the tax consequences)?
- How much should I expect to pay in taxes right away, all-in between federal, state, and local if applicable?
- Will I owe taxes later on, down the line?
- Have I considered the effects on my family of the different payout options?
- What is my strategy to preserve the money that remains after taxes and expenses?
- Do I have a financial professional who can guide me on navigating the effects of my decisions?
Would you like help managing the risks and must-dos?
[Book a **FREE Sudden Wealth Session**](https://independentadvisorsnw.com/homepage/education/sudden-wealth-inheritance/#inquiry)
### Crippling Risk #2
#### Damaging Family Relationships

Sometimes when a family member comes into money, other members of the family start lining up with their hands out. Or they resent the newly wealthy person. **You may even know someone whose money caused a big rift in their relationships, and you don't want the same thing to happen to you and your loved ones.**
You may be thinking about spreading the joy around, but what happens if you give to some people and others get none? What if you'd rather keep it all for the benefit of you and your immediate household, will other family members resent it?
People who suddenly receive significant amounts of money don't always know where and when the ground will shift under their feet when it comes to family. You may believe that everyone will be happy for you, and later find out that's not the case. **There may be fault lines in your relationships that could crack under the pressure of your newfound wealth, if you don't handle them in the right way.**
**Critical questions to help you manage your risk include:**
- Am I aware of the financial consequences, including gift taxes, if I give to others?
- How will this money affect my relationships?
- Do I have a financial professional who understands my circumstances, who can help me make good decisions that help me maintain my relationships?
Would you like help managing the risks and must-dos?
[Book a **FREE Sudden Wealth Session**](https://independentadvisorsnw.com/homepage/education/sudden-wealth-inheritance/#inquiry)
## "Must-Knows"
### MUST-KNOW #1
#### Money Can Be a Double-Edged Sword

A significant amount of money has the power to allow you to live your dreams. It could be the seed money you need to leave your corporate job and ride out on your own. Or you may finally have the money you need to enjoy an interest that you couldn't indulge while you worked full-time.
By creating a wise strategy and making smart choices, a future that you've always wanted — but never thought you could live — could be within your reach.
**On the other hand, you could very well end up worse off than before.** So many sudden money lottery winners go bankrupt after receiving their windfall.4 Sometimes the urge to buy things you couldn't afford before takes over, and as a result, there's not much left for investing or for the future. It's easy to think the money will last forever, but if you don't take care of it, it won't.
Your newfound wealth might be the opportunity of a lifetime. But you'll need to learn how to manage it. Otherwise, it could slip through your fingers.
**Critical questions whose answers you must know include:**
- What dreams does this money put within my reach?
- Am I being realistic about how much I can spend without running out of money?
- Do I know what the financial effects of my dream might be?
- Do I have a financial professional who can show me the financial consequences of changing my life?
Would you like help managing the risks and must-dos?
[Book a **FREE Sudden Wealth Session**](https://independentadvisorsnw.com/homepage/education/sudden-wealth-inheritance/#inquiry)
### MUST-KNOW #2
#### A Lasting Legacy Can Be Yours…
If the Strategy Is Right

You may prefer to make a positive impact on the world with a portion (or all) of your newfound wealth. Charities, successive generations, educational institutions, and other groups can benefit from significant donations. **You may also feel compelled to be a good steward of the money for a variety of reasons, and that's another way to leave your mark.**
**Most importantly, you want to use the funds as tax-efficiently as possible.** That way there's more left for your legacy. The right techniques depend on several factors, including how you want to be remembered and whether you'll want to have access to the money during your lifetime.
**Critical questions whose answers you must know include:**
- What do I want my legacy to be?
- Who and what do I want to benefit with this money?
- Am I aware of the most tax-efficient method for achieving my legacy goal?
- Is there a financial professional I know who can guide me through these options and maximize the value of my gifts?
Would you like help managing the risks and must-dos?
[Book a **FREE Sudden Wealth Session**](https://independentadvisorsnw.com/homepage/education/sudden-wealth-inheritance/#inquiry)
### MUST-KNOW #3
#### New-To-You Asset Protection Strategies

Your sudden windfall can potentially help you protect your other assets and your family as well. There are a number of asset protection strategies for the wealthy that you may not have had access to before. They require a certain level of investment that you may now have.
Simply having your assets in your own name may no longer be a good solution. Smart estate planning is critical, and just like investments, cookie-cutter solutions will not work. **Estate plans and other asset preservation techniques are very specific to your circumstances and desires.**
**Critical questions whose answers you must know include:**
- How can I preserve and help protect all my assets, including this more recent wealth?
- What options are available to me at my new, advanced financial level?
- Do I have a trusted professional who understands my needs and how to protect my family and my assets?
Would you like help managing the risks and must-dos?
[Book a **FREE Sudden Wealth Session**](https://independentadvisorsnw.com/homepage/education/sudden-wealth-inheritance/#inquiry)
## You Don't Have To Make These Critical Choices Alone
Suddenly coming into a sizable amount of money has the potential to change your life. Whether the impact is positive or negative is mostly the result of the choices you make. However, there is a way to use this money to help you build a lasting and solid financial foundation for you and your family.
**You may be able to fund dreams or goals that you previously thought were too far away to reach.** The options you choose in taking the payout and planning your investment strategies determine whether you make your dreams come true. Poor choices can deplete your funds before you even have a chance to enjoy them.
**Understanding the risks and effects of all the moves you make with your newfound money is critical.** Not only does this money have the potential to change your life, but potentially that of your family and later generations, too. That's why it's so important to develop a strategy and understand all the possible outcomes of your plan.
The sooner you shore up your strategy, the better. Some aspects of implementing your choices are time-sensitive, and taking action can help prevent the money from being squandered. Unfortunately, these things aren't taught in high school or college!
Our trained professionals have the specific education and experience to know what you don't. Rather than provide a cookie-cutter solution, we tailor your strategy to your own specific circumstances. Book your customized and free [Sudden Wealth Session](https://independentadvisorsnw.com/homepage/education/sudden-wealth-inheritance/#inquiry) today so you can start moving toward your dreams.
**We'll help you sort through the complexities of sudden wealth, and help you avoid the mistakes that have resulted in others in similar situations losing too much money.** You'll discover tax-efficient ways to preserve your wealth and potentially leave a legacy. We're professionals who understand how fault lines can suddenly appear in relationships, and help you prevent them from cracking.
You've already made the first smart decision to read through this guide. The next wise step is to contact us to book your free [Sudden Wealth Session.](https://independentadvisorsnw.com/homepage/education/sudden-wealth-inheritance/#inquiry)
## Would you like help managing the risks and must-dos? **Book a FREE SUDDEN WEALTH Session**
First Name
Last Name
Email
Phone
Best time to call No Preference Morning Afternoon
What should I know about you to prepare for our call?
Contact me by FAX only?

Goran Ognjenovic
Independent Investment Advisors
(971) 350-8068
info@independentadvisorsnw.com
https://iiaproduction.wpengine.com
Sources:
1 -
2 -
3 -
4 -
This information is not intended to be a substitute for specific individualized tax advice. We suggest that you discuss your specific tax issues with a qualified tax professional.
Risk Disclosure: Investing involves risk including the potential loss of principal. No investment strategy can guarantee a profit or protect against loss in periods of declining values. Past performance does not guarantee future results. This material is for information purposes only and is not intended as an offer or solicitation with respect to the purchase or sale of any security. The content is developed from sources believed to be providing accurate information; no warranty, expressed or implied, is made regarding accuracy, adequacy, completeness, legality, reliability or usefulness of any information. Consult your financial professional before making any investment decision. For illustrative use only.
The following posts and commentary are to be used solely as educational tools and do not contain investment advice. Investment advice must be tailored to a particular investor’s specific needs. None of the information contained should be construed to be investment advice. Individuals wishing to tailor a plan to their own needs should seek the help of a Registered Investment Advisor.
There is a high degree of risk in investing and trading. Independent Investment Advisors assumes no responsibility. Principles of Independent Investment Advisors may, at times, maintain directly or indirectly, positions in securities or derivatives mentioned in these comments.
---
### [Portfolio of $500,000 - $2 million?](https://independentadvisorsnw.com/homepage/education/portfolio-of-500000-2-million/)
**Published:** September 20, 2021
**Author:** Investment Advisor
**Content:**
Discover the “Perfect Cocktail” Strategy Used by Wealthy Investors Reveal the portfolio "ingredients" you may be missing [Book your "Perfect Cocktail" Strategy Session today](https://independentadvisorsnw.com/homepage/education/portfolio-of-500000-2-million/#inquiry) ## Portfolio of $500,000-$2 million? Discover the “Perfect Cocktail” Strategy Used by Wealthy Investors

What is it about your favorite cocktail that makes it perfect for you?
You could sit down at the bar and order the same thing as the person sitting next to you.
But you don’t.
You order the drink that fits your specific taste. Your mood.
The distinct aromas, perfect temperature, and hand-selected ingredients have been meticulously engineered to please your taste buds.
And you’ve likely tweaked it here and there over the course of your life as your tastes have changed.
You can certainly find plenty of financial information online, but how much of it applies to your particular situation?
Plain vanilla solutions might work for those with less complex needs. **However, you’re at the point where you need more advanced strategies.**
And you’re pretty sure that professionals working with immensely wealthy investors aren’t telling them to skip avocado toast and coffee shop lattes just to save a few pennies.
**Now is the time to discover the ingredients you’ll need and the tools that will allow you to craft a personalized strategy to manage your wealth as effectively as possible.**
If you’re not sure where to find the right techniques for your bespoke portfolio, you’re in the right place.
**This pivotal guide is your ticket to the financial strategy that serves your needs now and in the future, by providing you with the same tools that ultra-high-net-worth (UHNW) investors know and use.**
Discover the required ingredients and how to mix them for the optimal result for you and your family.
**Right now, you may be asking yourself questions like these:**
- Is my current strategy missing anything that would help me optimize what I’ve already accumulated?
- What opportunities are right around the corner?
- Am I protecting against the most likely risks?
- What happens if I don’t make the right decisions in time?
- Do I have a trusted resource to review all I’ve done so far and give me constructive feedback?
If any of these questions resonate with you, keep reading...

## INGREDIENT #1 Minimizing Taxes (As Much As Possible)
While it’s true that paying taxes is one of the two sure things in this world, the amount that you’re legally required to send to Uncle Sam isn’t set in stone. Taking steps to potentially lower your exposure to high marginal tax rates is key to keeping more of your money working for you.
**Maximizing your tax-deferred savings is one technique to potentially help reduce your taxable income now.** Your retirement plan is fundamental to your financial success, especially an employer-sponsored plan that allows you to sock away tax-deferred savings.
**Another strategy used by savvy investors is changing the nature of their income to capital gains wherever possible.** Long-term capital gains tax rates have historically been lower than income tax rates.1
**Investors with complex compensation arrangements can also potentially benefit from deferring compensation to future years, allowing them to control the tax consequences.**
Tax-smart asset allocation can also help reduce your tax liability by putting the right investments in the right taxable, tax-deferred, and tax-free “buckets”.
**Fundamental tax minimization questions to ask include:**
- Does my compensation package provide more benefits that could help me lower my taxes?
- Have I explored all the options available to me for reducing my tax exposure?
- Am I aware of all the tax consequences of the investment choices I make?
- **Have I asked for an objective view of my total tax picture from a professional?**
Reveal the portfolio "ingredients" you may be missing
[Book your "Perfect Cocktail" Strategy Session today](https://independentadvisorsnw.com/homepage/education/portfolio-of-500000-2-million/#inquiry)

## INGREDIENT #2 Crafting Your Health Care Elixir
One of the most expensive puzzles in retirement is paying for health care. Unfortunately these costs have been on the rise faster than average inflation for years.2
**Ensuring that unexpected health issues don’t undermine your financial strategy is another key ingredient to a successful financial strategy.**
It’s important to understand what Medicare pays for once you’re 65, and how it coordinates with your current employer’s coverage. Assuming, of course, that you still have access to that coverage at retirement.
How will you pay for the things that Medicare doesn’t cover, such as long-term care, dental, and vision? Will you self-insure or seek out supplemental coverage?
However, when it comes to long-term care when you can’t feed or dress yourself, you’re on your own to fund it under current laws. Advanced health care strategies such as long-term care insurance could help cover costs if you have a family history of needing care or you’re concerned about out-of-pocket costs.
**Fundamental questions to ask about your health care needs include:**
- What kind of health care coverage will I have in my senior years?
- Do I understand all the options for funding my health care needs in retirement?
- Am I likely to need long-term care in the future, and if so, how will I pay for it?
- **Have I discussed the rising costs of health care and how to account for them with a professional?**
Reveal the portfolio "ingredients" you may be missing
[Book your "Perfect Cocktail" Strategy Session today](https://independentadvisorsnw.com/homepage/education/portfolio-of-500000-2-million/#inquiry)

## INGREDIENT #3 Properly Positioning Your Portfolio
In the old days, investors could rely on interest income in retirement. The old adage that retirees lived by was **“Never touch the principal.”**
Unfortunately, while double-digit interest rates provide a healthy income, today’s lower rates may not. Especially when combined with longer, healthier lifespans.
**That makes a modern portfolio strategy that’s allocated the right way more important than ever. It needs to give you enough growth to fight back against inflation while not taking on too much risk in uncertain markets.**
**If your net worth is at least $1 million (not including the value of your home), you may be missing out on more advanced strategies available to you.** The details of your personal situation make a big difference, so asking the right questions and getting professional advice is critical to making the most of potential opportunities.
**Fundamental questions to ask about my portfolio include:**
- Do I understand the risks my portfolio faces now and in the near term?
- Have I found a balance between my needs now and in the future?
- Am I keeping an eye on the serious risks that could hurt my portfolio?
- Am I taking advantage of all the opportunities available to me as an investor?
- **Have I consulted a financial professional on whether my portfolio has the right mix of assets?**
Reveal the portfolio "ingredients" you may be missing
[Book your "Perfect Cocktail" Strategy Session today](https://independentadvisorsnw.com/homepage/education/portfolio-of-500000-2-million/#inquiry)

## INGREDIENT #4 Objectively Handling Your Whole Portfolio
Once you start amassing significant assets, the money is often held by more than one manager. If you have a 401(k) or similar retirement account, it’s typically managed alongside everyone else in the company, regardless of your personal needs.
In addition, you might have retirement plans from previous employers and individual retirement accounts, plus a taxable investment account or two.
Spreading your investments across a variety of managers and institutions doesn’t always benefit you as an investor. Each professional sees only their piece of the pie.
Without that global view, conflicting strategies could detract from portfolio value instead of enhancing it. Even if you’re managing your investments yourself.
Are you missing some key strategies or assets that might benefit you? Are you too concentrated in other areas?
A complete and objective perspective tells you when your portfolio is out of balance.
**We know that too much ice waters down a cocktail, and investing too much in one asset can dilute the performance of the whole portfolio.**
**Fundamental questions about my overall strategy include:**
- Do I have the right balance of assets to maximize the return for the amount of risk I’m willing to take?
- Do I know how much risk I can take?
- Am I able to view the whole portfolio objectively and determine whether I need to make adjustments?
- **Have I talked to a financial professional about whether my portfolio is greater than the sum of its parts, or something less?**
Reveal the portfolio "ingredients" you may be missing
[Book your "Perfect Cocktail" Strategy Session today](https://independentadvisorsnw.com/homepage/education/portfolio-of-500000-2-million/#inquiry)
## Mixing the Right Blend of Ingredients
For Your Personal Portfolio
When your perfect cocktail isn’t mixed correctly, you find the flavor’s off.
**Paying attention to the right ingredients in the right quantities is even more important when it comes to your financial future.**
If your portfolio isn’t as tax-efficient as it could be, you could be looking at higher taxes now. Even worse, they could be even higher than expected later in life.
**Opportunities to potentially reduce taxes may be available to you right now. Missing out on these types of strategies could mean leaving money on the table.**
With the current size of your portfolio, cookie-cutter solutions just don’t cut it. You need a personalized strategy that considers all the facts of your particular financial situation and blends it with the tools that will help you secure your financial future.
**The sooner you dig into these ingredients and techniques, the sooner you’ll be able to create a strategy that’s just right for you and your family. Making smart decisions before it’s too late is critical.**
We have the experience to help you craft the ultimate strategy. Book your complimentary “Personal Cocktail” Strategy Session now and begin crafting the sustainable portfolio you need.
We’ll identify any gaps you might have in your strategy, as well as leverage potentially uncovered opportunities. We are professionals in personalizing solutions for accomplished people like you. **We’ll take your unknowns and help you hedge against the risks you face, whether they’re obvious to you right now or not.**
You’ve already taken a smart step by reading through this guide. [Take the next one and schedule your private “Perfect Cocktail” Strategy Session with us today.](https://independentadvisorsnw.com/homepage/education/portfolio-of-500000-2-million/#inquiry)
Goran Ognjenovic
Independent Investment Advisors
(971) 350-8068
info@independentadvisorsnw.com
https://iiaproduction.wpengine.com
## Reveal the portfolio "ingredients" you may be missing?
Book your "Perfect Cocktail" Strategy Session today
First Name
Last Name
Email
Phone
Best Time to Reach You
Preferred Call Window No Preference Morning Afternoon
What should I know about you to prepare for our call?
Contact me by FAX only?
Sources:
1 -
2 -
Risk Disclosure: Investing involves risk including the potential loss of principal. No investment strategy can guarantee a profit or protect against loss in periods of declining values. Past performance does not guarantee future results.
This material is for information purposes only and is not intended as an offer or solicitation with respect to the purchase or sale of any security. The content is developed from sources believed to be providing accurate information; no warranty, expressed or implied, is made regarding accuracy, adequacy, completeness, legality, reliability, or usefulness of any information. Consult your financial professional before making any investment decision. For illustrative use only.
This information is not intended to be a substitute for specific individualized tax advice. We suggest that you discuss your specific tax issues with a qualified tax professional.
The following posts and commentary are to be used solely as educational tools and do not contain investment advice. Investment advice must be tailored to a particular investor’s specific needs. None of the information contained should be construed to be investment advice. Individuals wishing to tailor a plan to their own needs should seek the help of a Registered Investment Advisor.
There is a high degree of risk in investing and trading. Independent Investment Advisors assumes no responsibility. Principles of Independent Investment Advisors may, at times, maintain directly or indirectly, positions in securities or derivatives mentioned in these comments.
---
### [Outearned Your Financial Strategy?](https://independentadvisorsnw.com/homepage/education/outearned-your-financial-strategy/)
**Published:** September 24, 2021
**Author:** Investment Advisor
**Content:**
---
[< back to Investor Education Center](https://independentadvisorsnw.com/homepage/education/)
Outearned Your Financial Strategy? Searching for the optimal way to profit from your new wages and benefits package?
[Book your FREE customized Compensation Opportunities Session today.](#lm-inquiry)
# Outearned Your Financial Strategy?
## 3 NEW Opportunities & 2 Expensive Time Bombs
Has your income suddenly become more complex? Gone are the days of a straightforward salary, plus bonuses and maybe commissions.
To get where you are, you’ve taken on more responsibility and achieved higher-level decision-making abilities. **And now you need to do the same when it comes to your earnings.**
Feel like you’re cautiously walking through a minefield of acronyms when you’re reviewing your options?
ISOs, ESOPs, RSUs, NQSOs, SERPs, plus deferred comp, vesting, perquisites, 10b5-1 plans… the list goes on.
You may or may not be familiar with everything in your compensation package. Either way, you know you need to capitalize on it.
Right now, you’re not entirely sure what the ideal strategy is.
If your relationship with your benefits package was a social media status, it would say "it's complicated.” Sure, you have the smarts to figure it out yourself. But you’ve got more urgent tasks to deal with, and you really don’t think you have that kind of time anymore.
**In terms of money and career, you’re on a more advanced level now. Before you leveled-up, your financial life might have been simple enough that you didn’t need advice.** Or maybe you relied on your friend from college who now works in finance to give you some ideas or look over your choices. You might have even asked for guidance from another colleague who seemed pretty savvy about the company benefits.
When it comes to complex compensation, what’s right for someone else isn’t necessarily right for you. You want to know that you’re making wise decisions with your money. **You’ve outgrown your prior title and compensation structure, and in the process, you may have outgrown your money mavens, too.**
You potentially have the ability to stash away serious cash for your family and your retirement. But what are the hot opportunities that come with your new benefits, and how do you develop a solid strategy for your own personal situation?
If you’re not sure how to capitalize on your new capital complexity, you're in the right place.
**This quick read is designed to help you uncover the benefits of your executive compensation, and what potential landmines may be lurking below the surface.** Find out what you need to know and the questions you need to ask to prevent the unexpected from blowing up in your face.
Right now, you may be asking yourself questions like these:
- How do I maximize the promise of the benefits I now have access to?
- What are the tax advantages and disadvantages of all my choices?
- What don’t I know about my package?
- What happens if I don’t make the right decisions in time?
- Do I have a compensation professional already in my corner?
If these questions resonated with you, keep reading...
Searching for the optimal way to profit from your new wages and benefits package?
[Book your FREE customized Compensation Opportunities Session today.](#lm-inquiry)

## Red Hot Opportunity #1:
# Tax Deferral
To paraphrase George Carlin, Uncle Sam loves you, and he needs your money. High earnings tend to come with higher tax brackets and higher tax payments.
You’re probably already stashing as much as you can in tax-deferred retirement accounts. However, some of your new benefits may provide you with some additional tax deferral on top of the standard retirement plan.
**When it comes to stock options and Restricted Stock Units (RSUs), the key benefit is that your compensation can be shifted into long-term capital gains once you sell the stock you’ve acquired through the plan, as long as you meet certain requirements.**
Instead of earnings from W-2 or 1099 income that’s taxed at your marginal rate in the year you receive it, this portion of your compensation may be taxed at the much lower capital gains rate, as long as you satisfy the conditions.
The specifics of taxation depend on whether you’re granted Incentive Stock Options (ISOs) or Non-Qualified Stock Options (NQSOs) or RSUs.1 Note that depending on which you receive, there may be an income element when your options or RSUs vest.
Deferred compensation allows you to defer a portion (or all) of your earned income in retirement, when your tax bracket is lower.
**Critical questions to ask about tax deferral include:**
- What are the tax implications of all the steps involved with stock options and RSUs?
- Do I understand the risk in setting aside a portion of my income in a plan that’s not protected by regulations?
- Is there any benefit to incurring a small level of tax now?
- Have I asked a financial professional what the most tax-efficient choice is for me?


## Red Hot Opportunity #2:
# Distinctive Exits: Retirement Plans Beyond the 401(k)
At your rung on the company ladder, you've likely been contributing the maximum to your employer's retirement plan. Maybe you've been trying to find additional ways to build up your nest egg for your later years.
**When appropriate, deferred compensation and SERPs (Supplemental Employee Retirement Plans) can offer advantages.** However, there are many details to get right and potential risks to consider. For example, unlike your 401(k) plan, they're not protected by ERISA or other governmental regulations.
**Critical questions to ask about additional retirement possibilities include:**
- Can I go beyond my 401(k)?
- Do I understand the risk in setting aside a portion of my income in a plan that’s not protected by regulations?
- What is the effect on my current financial situation if I choose to defer more money from my paycheck?
- What happens if my company goes through an acquisition or liquidity event?
- Have I discussed with a financial professional the risk/reward tradeoff for these advanced exit plans?

## Red Hot Opportunity #3:
# Controlling Your Cash Flow
By shifting some of your compensation to stock shares and for later in retirement, you determine how much income you bring in at your marginal tax rate each year. **If there’s a year in which you expect a significant cash event (house sale, inheritance, etc.), you may elect to defer more compensation to later years, or take more equity options instead of salary.**
Your employer might also offer some executive perquisites, in addition to the formal alphabet soup arrangements. These fringe benefits, such as company-issued vehicles, insurance offerings, club memberships, and educational reimbursement, can lower your cost of living while you’re working for the company.
**Critical questions to ask about your income include:**
- Are the fringe benefits fully paid for by my employer?
- What perks do I have access to at my current level, and will that change if I continue with the company?
- Are there any tax issues that I need to be aware of?
- Have I discussed how an adjustable income flow could affect my financial strategy with a financial professional?


Searching for the optimal way to profit from your new wages and benefits package?
[Book your FREE customized Compensation Opportunities Session today.](#lm-inquiry)

## Time Bomb #1:
# Tax Analysis Paralysis
The tax aspects of executive compensation can be tricky, especially if you’re not used to dealing with them. **Unfortunately, getting them wrong could explode in an expensive tax bill.**
**When done right, company shares can be turned into income that’s taxed at the lower long-term capital gains rate.** But when not done right, you could end up being taxed at your marginal income rate instead. Incentive Stock Options (ISOs) and Non-Qualified Stock Options (NQSOs) operate differently and require separate strategies to make sure that you ultimately achieve your goal of long-term capital gains taxes.
**Also make sure you understand what perks are taxable in any given year (and what other factors you need to consider).** When it comes to income tax, surprises are usually a bad thing! Especially when you’re in a high tax bracket.
**Critical questions to ask about the timing of taxes include:**
- Do I understand the tax timing of each part of my compensation?
- Is it better to exercise some choices now, rather than wait until later?
- Have I properly assessed the relative importance of all the factors I need to consider?
- Have I talked about the impact of timing with a financial professional?

 
## Time Bomb #2:
# Missing Out
What happens if you don’t take advantage of the perks that you’ve been given? **Most of these benefits have very specific dates for when you have access to the privileges (vesting) and how long you have until they expire.**
Equity plans often issue new grants every year, which makes it easy for recipients to lose track of what’s available and when. **You don’t want to lose out on a profitable opportunity because some of your benefits have expired.**
On the other hand, if you stay on top of your grants, you’ll be accumulating shares. At some point you may even need to sell some equity just to diversify your portfolio.
But if you’re considered an insider, a Rule 10b5-1 plan may be necessary. **If you don’t already have one in place, you might not be able to sell your company shares.**
**Critical questions to ask about potential omissions include:**
- Do I have anything with a timeline I need to keep track of?
- If so, what is my strategy to avoid allowing any benefits to expire worthless?
- Do I need a Rule 10b5-1 plan, and if I don’t need one now, will I in the future?
- Have I discussed my strategy with a financial professional to avoid missing out on benefits?
## Contact me using the form below
Please do not enter sensitive information in this box.
Preferred Call Window Morning Afternoon
Contact me by FAX only?
# Find the Highest and Best Use of Your Complex Compensation (And Time)
At work, you prioritize your activities to get the most important tasks done first. You fill up your jar with the big, important rocks first and worry about the pebbles later. Why wouldn’t you want to do the same for your finances?
Making the wrong choices with your new pay package could result in higher taxes than necessary, and a smaller nest egg than you would have had otherwise. It’s critical to make smart decisions in a timely manner so you don’t end up leaving any money on the table.
**Once you start playing in the big league, matters get very complicated, very fast.** Strategies and teammates that worked in smaller arenas may no longer be a good fit. You need experienced coaches who can give you good advice on the transition. The solution you seek is specific to your personal circumstances.
The sooner you get clarity on exactly which benefits are available and the relevant timelines, the faster you can build a solid strategy for your personal situation. We have the experience to help guide you through the complex landmines. Book your FREE customized **Compensation Opportunities Session** today so you can get started on maximizing your income.
**We’ll help you determine if there are things you don’t know, and clarify the consequences of taking one action as opposed to another. We’re professionals in helping high earners like you uncover and leverage the benefits that fit their personal scenarios.**
You’ve already made a smart investment by taking the time to read through the guide. Make the next wise move by calling or emailing us now to set up your complimentary **Compensation Opportunities Session.**
Goran Ognjenovic
Independent Investment Advisors
(971) 350-8068
info@independentadvisorsnw.com
https://independentadvisorsnw.com
1
Risk Disclosure: Investing involves risk including the potential loss of principal. No investment strategy can guarantee a profit or protect against loss in periods of declining values. Past performance does not guarantee future results.
This material is for information purposes only and is not intended as an offer or solicitation with respect to the purchase or sale of any security. The content is developed from sources believed to be providing accurate information; no warranty, expressed or implied, is made regarding accuracy, adequacy, completeness, legality, reliability, or usefulness of any information. Consult your financial professional before making any investment decision. For illustrative use only.
This information is not intended to be a substitute for specific individualized tax advice. We suggest that you discuss your specific tax issues with a qualified tax professional.
The following posts and commentary are to be used solely as educational tools and do not contain investment advice. Investment advice must be tailored to a particular investor’s specific needs. None of the information contained should be construed to be investment advice. Individuals wishing to tailor a plan to their own needs should seek the help of a Registered Investment Advisor.
There is a high degree of risk in investing and trading. Independent Investment Advisors assumes no responsibility. Principles of Independent Investment Advisors may, at times, maintain directly or indirectly, positions in securities or derivatives mentioned in these comments.
---
### [Do you know what constitutes your Credit Score?](https://independentadvisorsnw.com/homepage/education/do-you-know-what-constitutes-your-credit-score/)
**Published:** September 4, 2020
**Author:** Financial Planner
**Content:**
[< back to Investor Education Center](https://independentadvisorsnw.com/homepage/education/)
# Do you know what constitutes your Credit Score?
Are you bewildered by your credit score? Are you wondering how to increase your score or why your score has taken a nosedive? Do you want to learn what makes up your credit score to make better financial decisions?
## Payment History
When it comes to your reliability with credit, your past payment history counts for a whopping 35 percent. If you are late paying bills, installment loans, or mortgage loans, you might want to reconsider your ways. Missing payments, better known as delinquencies, can also lower your score.
## Credit Utilization
Resist the urge to max out your credit cards. Credit card utilization – the ratio between your credit card balance to the available credit – constitutes 30 percent of your credit score. The smaller that percentage is, the higher your credit score will be. Aim to be at least 30 percent below your credit limit for a higher credit score. Better yet, keep your balance close to zero.
## Length of Credit History
The length of credit history makes up 15 percent of most credit scores. Not closing old accounts is essential in trying to boost your score. The more years of credit history you have, the higher your credit score will be.
## Mix of Accounts
When it comes to credit accounts, diversity is best. Having a mix of accounts constitutes 10 percent of your credit score. A combination of accounts (which can include credit cards, student loans, automobile loans, and mortgages) is superior to one type of account, such as credit cards. Ideally, lenders like to see timely payments of each account.
---
### [The Simple 3 Step Medicare Guide](https://independentadvisorsnw.com/homepage/education/the-simple-3-step-medicare-guide/)
**Published:** October 15, 2021
**Author:** Financial Planner
**Content:**
The Simple 3-Step Medicare Guide Would you like help comparing plans and prices? [Book a **FREE Medicare Optimization Session**](#inquiry) 


# The Simple
3-Step
Medicare
Guide
## **When, Why, and How To Choose A Plan That’s Right For You**
(especially if you’re already enrolled)
Whether you’re looking into Medicare for the first time, or taking advantage of annual enrollment to update your strategy, we’ve broken down the critical choices you must make into a simple decision-making tool (including the easy-to-understand questions you MUST ask yourself before choosing a plan).
Getting the answers wrong can cost you big-time! Not only is health care likely to be your largest expense in your retirement (potentially $300,000 or more), but nearly every American over age 65 must eventually enroll in Medicare.1
Making the wrong choices could cost you thousands in permanent penalties, leave you facing high medical bills without coverage, or force you into a too-expensive plan.
In the following pages, I’ll walk you step-by-step through a shockingly simple set of questions to help you choose a Medicare plan. By virtue of its simplicity, this decision-making tool leaves out most of the nitty gritty.
Have any questions along the way? Just click the button to book a 100% free, 1-on-1 consultation to get help making these critical (and time-sensitive) decisions.
Let’s get started…

Would you like help comparing plans and prices?
[Book a **FREE Medicare Optimization Session**](#inquiry)

## When To Enroll
### **Do I need to enroll in Medicare?** Key questions to help guide your decision:
**Are you at least 65?** Unless you qualify for disability, you typically don’t qualify for Medicare until age 65. There are some exceptions to that rule, so if you have questions about your eligibility, book a free chat with me to discuss. We’ll help you determine exactly when you need to enroll in Medicare.
**Are you covered by employer-sponsored or retiree health insurance?** If so, and your employer has at least 20 employees, you may not need to enroll in Medicare yet.
**Do you qualify for VA benefits or TriCare?** If so, you may still need to enroll in Medicare Part B because VA and Medicare benefits do not overlap.
**Warning!** If you are eligible for Medicare coverage and are not covered by qualifying insurance, you should consider enrolling in Medicare ASAP to avoid late enrollment penalties and higher premium costs.
Now, let’s talk about which Medicare strategy might be right for you…
Would you like help comparing plans and prices?
[Book a **FREE Medicare Optimization Session**](#inquiry)

## Why Choose a
Medicare Plan?
### What Medicare plan is right for me?
Choosing a Medicare plan means balancing priorities and knowing what’s most important to you. Remember — there are no right or wrong answers to these questions.
Feeling overwhelmed? My team and I are here to help you understand your options and make the right decision. [Just click here to book a complimentary 1-on-1 session to get your questions answered.](#inquiry)
#### Choosing between
**Original Medicare (Parts A + B)** and a **Medicare Advantage Plan (Part C)**.
##### Which sounds like you?
- I already have doctors and specialists, and don't want to switch.
- I travel away from home and want coverage that spans the entire United States.
- I value the freedom to visit almost any doctor, hospital, and medical provider that accepts Medicare…
**You Should Consider Original Medicare Part A (Hospital Insurance) + Part B (Medical Insurance)**
- I don't mind going through a primary care physician to see specialists…
- I stay close to home and can find a doctor within my network…
- I value simplicity and don't want to manage multiple insurance plans…
**You Should Consider a Medicare Advantage Plan (Part C)**

Part A covers hospitals, rehab, and hospice care, whereas Part B covers doctor visits, lab tests, screenings, and other outpatient services. While Part A is free for most people, you’ll pay monthly premiums for Part B plus deductibles, copays, and coinsurance.
**Pros:** You have the freedom to visit any provider or hospital in the U.S. that participates in Medicare and don’t need to work with a primary care physician to see specialists. This flexibility is ideal if you travel outside of your home network or have existing relationships with doctors you want to keep.
**Cons:** Services have deductibles and copays, which may require you to purchase a Medigap or Medicare Supplement Plan to control your out-of-pocket spending. You will also need to purchase prescription drug coverage (Medicare Part D) separately.

Offered through private insurers, Part C is often structured like an HMO or PPO and provides comprehensive health coverage combining Parts A and B.
**Pros:** Many Part C plans cover extra services like vision, hearing, and dental and may include prescription drug coverage. Plans have an annual limit on your total out-of-pocket costs.
**Cons:** In addition to paying a part B premium, you’ll typically pay an extra monthly premium for the Medicare Advantage plan. Networks change, doctors can leave, and benefits can change over time.
##### Now, let's talk about any prescription drug coverage you may need...
#### **Choosing Original Medicare (Parts A + B)?**
Since it doesn't cover prescription drugs, you automatically need Medicare Part D.

You’ll need to sign up as soon as you become eligible for Medicare, even if you don’t use prescription drugs, to avoid paying late enrollment penalties.
**Pros:** Copays and other plan details vary by state and insurer, but they will cover most of the cost of your prescriptions.
**Cons:** After exceeding coverage limits, you’ll pay the full cost of your medications until a Medicare threshold is reached.
##### Let's see if you need supplemental insurance to lower your out-of-pocket costs.
**Do you have retiree coverage through the military or a private company?** 81% of Original Medicare participants had some type of supplemental coverage.2
If not, you may want to consider a Medicare Supplement Plan or Medigap.
What is it? Private insurance that fills the coverage gaps in Parts A and B of Medicare and helps with deductibles, copays, coinsurance, etc.
**Pros:** It limits your out-of-pocket costs for Original Medicare.
**Cons:** There are many different types of Medigap plans, all with different details.
#### **Choosing a Medicare Advantage Plan (Part C)?**
You'll need to determine whether prescription drug coverage is included. Most Medicare Advantage plans include prescription drug coverage, though not all do. Read your policy documents carefully.
Would you like help comparing plans and prices?
[Book a **FREE Medicare Optimization Session**](#inquiry)

## How To Enroll
### You don’t need to make critical Medicare decisions by yourself
As a taxpayer, you’ve earned the right to your Medicare benefits. If this guide hasn’t given you 100% confidence in your next steps, you don’t need to go it alone. All you need to do is call my office.
Right now, you might be asking yourself questions like:
- How do I enroll?
- When is my next enrollment period?
- Which doctors and hospitals will take my plan?
- How much are my premiums, deductibles, and services going to cost?
- How do I balance coverage with price?
- Do I have to medically qualify?
If you are, [I’d like to invite you to ask me those questions directly in a 1-on-1 meeting.](#inquiry) You’ll walk away with complete clarity about what to do next. We’ll answer your questions, talk about the retirement health care decisions you’ll need to make, and help you choose.
Best of all, we’ll be there afterwards for all follow-up questions and concerns, [just click here to set up an appointment.](#inquiry)
## Would you like help comparing plans and prices? Book a FREE Medicare
Optimization Session
First Name
Last Name
Email
Phone
Preferred Call Window No Preference Morning Afternoon
What should I know about you to prepare for our call?
Contact me by FAX only?

Goran Ognjenovic
Independent Investment Advisors
https://iiaproduction.wpengine.com
(971) 350-8068
Sources:
1 -
2 -
Risk Disclosure: Investing involves risk including the potential loss of principal. No investment strategy can guarantee a profit or protect against loss in periods of declining values. Past performance does not guarantee future results.
This material is for information purposes only and is not intended as an offer or solicitation with respect to the purchase or sale of any security. The content is developed from sources believed to be providing accurate information; no warranty, expressed or implied, is made regarding accuracy, adequacy, completeness, legality, reliability, or usefulness of any information. Consult your financial professional before making any investment decision. For illustrative use only.
The following posts and commentary are to be used solely as educational tools and do not contain investment advice. Investment advice must be tailored to a particular investor’s specific needs. None of the information contained should be construed to be investment advice. Individuals wishing to tailor a plan to their own needs should seek the help of a Registered Investment Advisor.
There is a high degree of risk in investing and trading. Independent Investment Advisors assumes no responsibility. Principles of Independent Investment Advisors may, at times, maintain directly or indirectly, positions in securities or derivatives mentioned in these comments.
---
### [Savings & Investment Calculator](https://independentadvisorsnw.com/homepage/financial-calculators/savings-investment-calculator/)
**Published:** October 29, 2020
**Author:** Financial Planner
**Content:**
[< Financial Calculators](https://independentadvisorsnw.com/homepage/financial-calculators/)
# Savings Calculator
Calculate the future value of your investment or savings account!
This calculator easily answers the question “If I save ‘X’ amount for ‘Y’ months what will the value be at the end?”
The user enters the “Periodic Savings Amount” (amount saved or invested every month); the “Number of Months” and the “Annual Interest Rate” or the annual rate of return one expects to earn on their investments.
The calculator quickly creates a savings schedule and a set of charts that will help the user see the relationship between the amount invested and the return on the investment. The schedule can be copied and pasted to Excel, if desired.
The investment term is always expressed in months.
- 60 months = 5 years
- 120 months = 10 years
- 180 months = 15 years
- 240 months = 20 years
- 360 months = 30 years
### [Independent Investment Advisors
Savings Calculator](https://AccurateCalculators.com/savings-calculator "click for more features")
Periodic Savings Amount?:
Number of Months?:
Annual Interest Rate?:
---
Final Amount (future value):
Interest Earned:
Total Amount Invested:
Last Deposit Date:
Calc
Clear
Print
Help
Savings Schedule
Charts
©2026 [ AccurateCalculators.com
](https://AccurateCalculators.com "(c) AccurateCalculators.com")
$ : mm/dd/yyyy
Original Size
#### Currency and Date Conventions
✕
Albania (Lek) Lek12,345,678.99Algeria (Algerian Dinar) DZD12,345,678.99Argentina (Argentine Peso) $12.345.678,99Armenia (Armenian Dram) AMD12,345,678.99Australia (Australian Dollar) $12,345,678.99Austria (Euro) €12.345.678,99Azerbaijan (Manat) ₼12,345,678.99Bahrain (Bahraini Dinar) BHD12,345,678.994Belarus (Ruble) Br12,345,678.99Belgium (Euro) 12 345 678,99€Belgium (Euro) €12.345.678,99Belize (Belize Dollar) BZ$12,345,678.99Bolivia (Boliviano) $b12.345.678,99 Bosnia/Herzegovina (Mark) 12.345.678,99KMBrazil (Brazilian Real) R$12.345.678,99Brunei (Brunei Dollar) $12,345,678.99Bulgaria (Bulgarian Lev) 12345678,99лвCanada (Canadian Dollar) $12,345,678.99Canada (Canadian Dollar) 12 345 678,99$Chile (Chilean Peso) $12.345.679China (Yuan Renminbi) ¥12,345,678.99Colombia (Colombian Peso) $12.345.678,99Costa Rica (Colon) ₡12 345 678,99Croatia (Kuna) 12.345.678,99knCzechia (Czech Koruna) 12 345 678,99KčDenmark (Danish Krone) 12.345.678,99krDominican Republic (DR Peso) RD$1,234.99Ecuador (US Dollar) $12.345.678,99Egypt (Egyptian Pound) £12,345,678.99El Salvador (El Salvador Colon) $12,345,678.99Estonia (Euro) 12 345 678,99€Faroe Islands (Danish Krone) kr12,345,678.99Finland (Euro) 12 345 678,99€France (Euro) 12 345 678,99€Georgia (Lari) GEL12,345,678.99Germany (Euro) 12.345.678,99€Greece (Euro) 12.345.678,99€Guatemala (Quetzal) Q12,345,678.99Honduras (Lempira) L12,345,678.99Hong Kong (HK Dollar) HK$12,345,678.99Hungary (Forint) 12 345 678,99FtIceland (Iceland Krona) kr12,345,679India (Indian Rupee) ₹1,23,45,678.99Indonesia (Rupiah) Rp12.345.678,99Iran (Iranian Rial) ﷼12,345,678.99Iraq (Iraqi Dinar) IQD12,345,678.994Ireland (Euro) €12,345,678.99Israel (Sheqel) ₪12,345,678.99Italy (Euro) 12.345.678,99€Jamaica (Jamaican Dollar) J$12,345,678.99Japan (Yen) ¥12,345,679Jordan (Jordanian Dinar) JOD12,345,678.994Kazakhstan (Tenge) лв12,345,678.99Kenya (Kenyan Shilling) KES12,345,678.99Korea (South) (Won) ₩12,345,679Kuwait (Kuwaiti Dinar) KWD12,345,678.994Kyrgyzstan (Som) лв12,345,678.99Latvia (Euro) 12 345 678,99€Lebanon (Lebanese Pound) £12,345,678.99Libya (Libyan Dinar) LYD12,345,678.994Liechtenstein (Swiss Franc) CHF12’345’678.99Lithuania (Euro) 12 345 678,99€Luxembourg (Euro) 12.345.678,99€Luxembourg (Euro) 12.345.678,99€Macao (Pataca) MOP12,345,678.99Malaysia (Ringgit) RM12,345,678.99Maldives (Rufiyaa) MVR12,345,678.99Malta (Euro) €12,345,678.99Mexico (Mexican Peso) $12,345,678.99Monaco (Euro) 12 345 678,99€Mongolia (Tugrik) ₮12,345,678.99Morocco (Dirham) MAD12,345,678.99Netherlands (Euro) €12.345.678,99New Zealand (NZ Dollar) $12,345,678.99Nicaragua (Cordoba Oro) C$12,345,678.99Nigeria (Naira) ₦12,345,678.99Norway (Norwegian Krone) kr12 345 678,99Norway (Norwegian Krone) kr12,345,678.99Oman (Rial Omani) ﷼12,345,678.994Pakistan (Pakistan Rupee) ₨12,345,678.99Panama (Balboa) B/.12,345,678.99Paraguay (Guarani) Gs12.345.679Peru (Sol) S/.12,345,678.99Philippines (Philippine Peso) ₱12,345,678.99Poland (Zloty) 12 345 678,99złPortugal (Euro) 12 345 678,99€Qatar (Qatari Rial) ﷼12,345,678.99Romania (Romanian Leu) 12.345.678,99leiRussian Federation (Ruble) 12 345 678,99₽Saudi Arabia (Saudi Riyal) ﷼12,345,678.99Singapore (Singapore Dollar) $12,345,678.99Slovakia (Euro) 12 345 678,99€Slovenia (Euro) 12.345.678,99€South Africa (Rand) R12,345,678.99South Africa (Rand) R12 345 678,99Spain (Euro) 12.345.678,99€Sweden (Swedish Krona) 12 345 678,99krSwitzerland (Swiss Franc) CHF12’345’678.99Switzerland (Swiss Franc) 12 345 678.99CHFSwitzerland (Swiss Franc) CHF12’345’678.99Syrian Arab Republic (SYP) SYP 12,345,679Taiwan (Taiwan Dollar) NT$12,345,678.99Thailand (Baht) ฿12,345,678.99Trinidad & Tobago (T/T Dollar) TT$1,234.99Tunisia (Tunisian Dinar) TND12,345,678.994Turkey (Turkish Lira) ₺12.345.678,99Ukraine (Hryvnia) 12 345 678,99₴United Arab Emirates (UAE Dirham) AED12,345,678.99United Kingdom (GBP) £12,345,678.99United States (US Dollar) $12,345,678.99Uruguay (Peso Uruguayo) $U12.345.678,99Uzbekistan (Uzbekistan Sum) лв12,345,678.99Venezuela (Bolívar Soberano) VES12.345.678,99Viet Nam (Dong) 12.345.679₫Yemen (Yemeni Rial) ﷼12,345,678.99Zimbabwe (ZWL) ZWL12,345,678.99
MM/DD/YYYYDD/MM/YYYYDD-MM-YYYYDD.MM.YYYYYYYY-MM-DDYYYY.MM.DDYYYY/MM/DD
The calculator will remember your choice. You may also change it at any time.
Clicking “Save changes” will cause the calculator to reload. Your edits will be lost.
Cancel
Save changes
#### Cash flow forecast…
✕
Close
#### Charts
✕
Close
#### Help
✕
Close
#### Message
✕
Close
---
### [Mortgage Calculator](https://independentadvisorsnw.com/homepage/financial-calculators/mortgage-calculator/)
**Published:** October 29, 2020
**Author:** Financial Planner
**Content:**
[< Financial Calculators](https://independentadvisorsnw.com/homepage/financial-calculators/)
# Mortgage Calculator
You can calculate the mortgage loan amount from the price of the real estate by providing the down payment percentage.
If you know the mortgage amount you can afford and the cash down payment percentage required, you can calculate the affordable real estate price.
Or if you know the price of the real estate and the loan amount and enter “0” for the down payment percentage, the calculator will calculate the down payment amount and percentage.
Points, Annual Property Taxes, Annual Insurance, and Private Mortgage Ins. (PMI) are all optional. If you enter values, the periodic portion of each will be calculated and shown on the schedule. Property taxes and insurance are combined under escrow.
If a borrower does not have the cash to cover at least 20% of the purchase price, some lenders will require the borrower to purchase private mortgage insurance (PMI) to cover against a possible default. Premiums are typically 0.5% to 2.0% of the original loan amount. The borrower can drop the insurance coverage once the mortgage balance is less than 80% of the original purchase price. The calculator handles this automatically. (There may be other conditions as well under which the lender will no longer require PMI. One such case might be an appreciation of the real estate.)
Points are charges that are normally due at closing. Borrowers (normally only in USA) may select to pay a lender “points” up front in exchange for a lower interest rate. Points are expressed in percent and are calculated on the amount borrowed. 3 points on a $200,000 mortgage equals $6,000. If the user enters points, this calculator includes their value in the summary and as part of the total payment at loan origination on the payment schedule.
The term (duration) of the loan is expressed as a number of months.
- 60 months = 5 years
- 120 months = 10 years
- 180 months = 15 years
- 240 months = 20 years
- 360 months = 30 years
### [Independent Investment Advisors
Mortgage Loan Calculator](https://AccurateCalculators.com/mortgage-calculator "click for more features")
Price of Real Estate?:
Down Payment Percentage?:
Amount of Loan?:
Enter a “0” (zero) for one unknown value above.
Number of Payments? (#):
Annual Interest Rate?:
Points?:
Annual Property Taxes?:
Annual Insurance?:
Private Mortgage Ins. (PMI)?:
Payment Method?:
End-of-PeriodStart-of-Period
---
Monthly Payment Amount:
Down Payment Amount:
Total Interest:
Total Principal & Interest:
Calc
Clear
Print
Help
Payment Schedule
Charts
©2026 [ AccurateCalculators.com
](https://AccurateCalculators.com "(c) AccurateCalculators.com")
$ : mm/dd/yyyy
Original Size
---
### [Retirement Nest Egg Calculator](https://independentadvisorsnw.com/homepage/financial-calculators/retirement-nest-egg-calculator/)
**Published:** October 29, 2020
**Author:** Financial Planner
**Content:**
[< Financial Calculators](https://independentadvisorsnw.com/homepage/financial-calculators/)
# Retirement Nest Egg Calculator
Calculate the future value of your retirement fund!
This calculator easily answers the question “Given the value of my current investments and assuming future monthly investments of “X”, what will be the value of my retirement nest egg?
The user enters their “Current Age”, their expected “Retirement Age”, the “Monthly Amount Invested”, and the “Annual Interest Rate (ROI)” (annualized Return on Investment one expects to earn).
The calculator quickly calculates the expected final value of their investments and creates an investment schedule plus a set of charts that will help the user see the relationship between the amount invested and the return on the investment. The schedule can be copied and pasted to Excel if desired.
### [Independent Investment Advisors
Retirement Calculator](https://AccurateCalculators.com/retirement-calculator "click for more features")
Your Current Age?:
Anticipated Retirement Age?:
Current Retirement Savings?:
Monthly Amount Invested?:
Annual Interest Rate (ROR)?:
---
Available At Retirement:
Number of Contributions:
Total Amount Invested:
Return on Investment:
Last Investment Date:
Calc
Clear
Print
Help
Savings Schedule
Charts
©2026 [ AccurateCalculators.com
](https://AccurateCalculators.com "(c) AccurateCalculators.com")
$ : mm/dd/yyyy
Original Size
---
### [Retirement Age Calculator](https://independentadvisorsnw.com/homepage/financial-calculators/retirement-age-calculator/)
**Published:** October 29, 2020
**Author:** Financial Planner
**Content:**
[< Financial Calculators](https://independentadvisorsnw.com/homepage/financial-calculators/)
# Retirement Age Calculator
Calculate your projected retirement age.
This calculator easily answers the question “Given the value of my current investments and assuming future monthly investments of “X”, at what age will I reach my retirement goal?”
The user enters their “Current Age”, the “Monthly Amount Invested”, the “Annual Interest Rate (ROI)” (annualized Return on Investment one expects to earn), and “Amount Desired At Retirement”.
The calculator quickly calculates the user’s retirement age and creates an investment schedule plus a set of charts that will help the user see the relationship between the amount invested and the return on the investment. The schedule can be copied and pasted to Excel if desired.
### [Independent Investment Advisors
Retirement Age Calculator](https://AccurateCalculators.com/retirement-age-calculator "click for more features")
Your Current Age?:
Current Retirement Savings?:
Monthly Amount Invested?:
Annual Interest Rate (ROR)?:
Amount At Retirement?:
---
Projected Retirement Age:
Number of Contributions (#):
Total Amount Invested:
Investment Gain:
Estimated Final Value:
Last Deposit Date:
Calc
Clear
Print
Help
Savings Schedule
Charts
©2026 [ AccurateCalculators.com
](https://AccurateCalculators.com "(c) AccurateCalculators.com")
$ : mm/dd/yyyy
Original Size
---
### [Loan Calculator](https://independentadvisorsnw.com/homepage/financial-calculators/loan-calculator/)
**Published:** October 29, 2020
**Author:** Financial Planner
**Content:**
[< Financial Calculators](https://independentadvisorsnw.com/homepage/financial-calculators/)
# Loan Calculator
Using the calculator is straightforward. User enters a “loan amount”, “number of months”, “annual interest rate”. The calculator calculates the number of monthly payments.
The “Payment Method” determines when the first payment is due. With the default selection, “End-of-Period”, the first payment will be due one month after the loan is made. If “Start-of-Period” is selected, then the first payment will be due on the loan date.
The term (duration) of the loan is expressed as a number of months.
- 60 months = 5 years
- 120 months = 10 years
- 180 months = 15 years
- 240 months = 20 years
- 360 months = 30 years
### [Independent Investment Advisors
Loan Calculator](https://AccurateCalculators.com/loan-calculator "click for more features")
Loan Amount?:
Number of Months? (#):
Annual Interest Rate?:
Payment Method?:
End-of-PeriodStart-of-Period
---
Monthly Payment:
Total Interest:
Total Principal & Interest:
Calc
Clear
Print
Help
Payment Schedule
Charts
©2026 [ AccurateCalculators.com
](https://AccurateCalculators.com "(c) AccurateCalculators.com")
$ : mm/dd/yyyy
Original Size
---
### [Retirement Savings Calculator](https://independentadvisorsnw.com/homepage/financial-calculators/retirement-savings-calculator/)
**Published:** October 29, 2020
**Author:** Financial Planner
**Content:**
[< Financial Calculators](https://independentadvisorsnw.com/homepage/financial-calculators/)
# Retirement Savings Calculator
Calculate the savings required to reach your retirement goals!
This calculator easily answers the question “Given the value of my current investments how much do I need to save each month to reach my retirement goal?”
The user enters their “Current Age”, their expected “Retirement Age”, the “Annual Interest Rate (ROI)” (annualized Return on Investment one expects to earn), and “Amount Desired At Retirement”.
The calculator quickly calculates the required monthly investment amount and creates an investment schedule plus a set of charts that will help the user see the relationship between the amount invested and the return on the investment. The schedule can be copied and pasted to Excel if desired.
### [Independent Investment Advisors
Retirement Savings Calculator](https://AccurateCalculators.com/retirement-savings-calculator "click for more features")
Your Current Age?:
Anticipated Retirement Age?:
Current Retirement Savings?:
Annual Interest Rate (ROR)?:
Amount At Retirement?:
---
Monthly Investment Required:
Number of Contributions:
Total Amount Invested:
Interest Earned:
Estimated Final Value:
Last Deposit Date:
Calc
Clear
Print
Help
Savings Schedule
Charts
©2026 [ AccurateCalculators.com
](https://AccurateCalculators.com "(c) AccurateCalculators.com")
$ : mm/dd/yyyy
Original Size
---
### [Disclaimer](https://independentadvisorsnw.com/opt-out-preferences-3/)
**Published:** November 8, 2022
**Author:** MMGI Admin
**Content:**
*This page was last changed on August 28, 2026, last checked on August 28, 2026 and applies to citizens and legal permanent residents of the United States.*
## 1. Introduction
Our website, (hereinafter: “the website”) uses cookies and other related technologies (for convenience all technologies are referred to as “cookies”). Cookies are also placed by third parties we have engaged. In the document below we inform you about the use of cookies on our website.
We apply a prior-consent (opt-in) model on this website: non-functional cookies and similar tracking technologies are blocked and are not placed until you actively give your consent. You can grant, withdraw, or change your consent at any time.
We do not sell or share personal information to third parties for monetary consideration; however, we may disclose certain personal information to third parties under circumstances that might be deemed a “sale” or ”Sharing” for residents of Oregon (OCPA), California (CPRA), Colorado (CPA), Montana (MCDPA) and Utah (UCPA). We respect and understand that you may want to be sure that your personal information is not being sold or shared. You may request that we exclude your personal information from such arrangements, or direct us to limit the use and disclosure of possible sensitive personal information, by entering your name and email address below. You may need to provide additional identifying information before we can process your request.
×
Name Name
Email
Global opt-out from selling and sharing my personal information and limiting the use or disclosure of sensitive personal information.
Do not sell my personal information for cross-context behavioral advertising
Limit the use of my sensitive personal information
Request for access
Right to be Forgotten
Right to Data Portability
## 2. Cookies
When you visit our website it can be necessary to store and/or read certain data from your device by using technologies such as cookies.
### 2.1 Technical or functional cookies
Some cookies ensure that certain parts of the website work properly and that your user preferences remain known. By placing functional cookies, we make it easier for you to visit our website. This way, you do not need to repeatedly enter the same information when visiting our website and, for example, the items remain in your shopping cart until you have paid. We may place these cookies without your consent.
### 2.2 Statistics cookies
We use statistics cookies to optimize the website experience for our users. With these statistics cookies we get insights in the usage of our website.
### 2.3 Marketing/Tracking cookies
Marketing/Tracking cookies are cookies or any other form of local storage, used to create user profiles to display advertising or to track the user on this website or across several websites for similar marketing purposes.
### 2.4 Social media
On our website, we have included content from Facebook, X (Formerly Twitter), Instagram and LinkedIn to promote web pages (e.g. “like”, “pin”) or share (e.g. “tweet”) on social networks like Facebook, X (Formerly Twitter), Instagram and LinkedIn. This content is embedded with code derived from Facebook, X (Formerly Twitter), Instagram and LinkedIn and places cookies. This content might store and process certain information for personalized advertising.
Please read the privacy statement of these social networks (which can change regularly) to read what they do with your (personal) data which they process using these cookies. The data that is retrieved is anonymized as much as possible. Facebook, X (Formerly Twitter), Instagram and LinkedIn are located in the United States.
## 3. Placed cookies
Most of these technologies have a function, a purpose, and an expiration period.
1. A function is a particular task a technology has. So a function can be to “store certain data.”
2. Purpose is “the Why” behind the function. Maybe the data is stored because it is needed for statistics.
3. The expiration period shows the length of the period the used technology can “store or read certain data.”
### Tidio Live Chat
Functional
Consent to service tidio-live-chat
#### Usage
We use Tidio Live Chat for chat support. [Read more about Tidio Live Chat](https://cookiedatabase.org/service/tidio-live-chat/)
#### Sharing data
For more information, please read the [Tidio Live Chat Privacy Statement](https://www.tidio.com/privacy-policy/).
#### Functional
##### Name
[tidio\_state\_\*](https://cookiedatabase.org/cookie/tidio-live-chat/tidio_state_/)
##### Expiration
##### Function
### WordPress
Functional
Consent to service wordpress
#### Usage
We use WordPress for website development. [Read more about WordPress](https://cookiedatabase.org/service/wordpress/)
#### Sharing data
This data is not shared with third parties.
#### Functional
##### Name
[wpEmojiSettingsSupports](https://cookiedatabase.org/cookie/wordpress/wpemojisettingssupports/)
##### Expiration
session
##### Function
Store browser details
### Facebook
Marketing, Functional
Consent to service facebook
#### Usage
We use Facebook for display of recent social posts and/or social share buttons. [Read more about Facebook](https://cookiedatabase.org/service/facebook/)
#### Sharing data
For more information, please read the [Facebook Privacy Statement](https://www.facebook.com/policy/cookies).
#### Marketing
##### Name
[\_fbp](https://cookiedatabase.org/cookie/facebook/_fbp/)
##### Expiration
3 months
##### Function
Store and track visits across websites
##### Name
[\_fbc](https://cookiedatabase.org/cookie/facebook/_fbc/)
##### Expiration
2 years
##### Function
Store last visit
##### Name
[fbm\*](https://cookiedatabase.org/cookie/facebook/fbm_/)
##### Expiration
1 year
##### Function
Store account details
##### Name
[xs](https://cookiedatabase.org/cookie/facebook/xs/)
##### Expiration
3 months
##### Function
Store a unique session ID
##### Name
[fr](https://cookiedatabase.org/cookie/facebook/fr/)
##### Expiration
3 months
##### Function
Provide ad delivery or retargeting
##### Name
[act](https://cookiedatabase.org/cookie/facebook/act/)
##### Expiration
90 days
##### Function
Store logged in users
##### Name
[datr](https://cookiedatabase.org/cookie/facebook/datr/)
##### Expiration
2 years
##### Function
Provide fraud prevention
##### Name
[c\_user](https://cookiedatabase.org/cookie/facebook/c_user/)
##### Expiration
30 days
##### Function
Store a unique user ID
##### Name
[sb](https://cookiedatabase.org/cookie/facebook/sb/)
##### Expiration
2 years
##### Function
Store browser details
##### Name
[\*\_fbm\_](https://cookiedatabase.org/cookie/facebook/_fbm_/)
##### Expiration
1 year
##### Function
Store account details
#### Functional
##### Name
[wd](https://cookiedatabase.org/cookie/facebook/wd/)
##### Expiration
1 week
##### Function
Read screen resolution
##### Name
[csm](https://cookiedatabase.org/cookie/facebook/csm/)
##### Expiration
90 days
##### Function
Provide fraud prevention
##### Name
[actppresence](https://cookiedatabase.org/cookie/facebook/actppresence/)
##### Expiration
session
##### Function
Store and track if the browser tab is active
### Complianz
Functional
Consent to service complianz
#### Usage
We use Complianz for cookie consent management. [Read more about Complianz](https://cookiedatabase.org/service/complianz/)
#### Sharing data
This data is not shared with third parties. For more information, please read the [Complianz Privacy Statement](https://complianz.io/legal/privacy-statement/).
#### Functional
##### Name
[cmplz\_policy\_id](https://cookiedatabase.org/cookie/complianz/cmplz_policy_id/)
##### Expiration
365 days
##### Function
Store accepted cookie policy ID
##### Name
[cmplz\_consented\_services](https://cookiedatabase.org/cookie/complianz/cmplz_consented_services/)
##### Expiration
365 days
##### Function
Store cookie consent preferences
##### Name
[cmplz\_marketing](https://cookiedatabase.org/cookie/complianz/cmplz_marketing/)
##### Expiration
365 days
##### Function
Store cookie consent preferences
##### Name
[cmplz\_statistics](https://cookiedatabase.org/cookie/complianz/cmplz_statistics/)
##### Expiration
365 days
##### Function
Store cookie consent preferences
##### Name
[cmplz\_preferences](https://cookiedatabase.org/cookie/complianz/cmplz_preferences/)
##### Expiration
365 days
##### Function
Store cookie consent preferences
##### Name
[cmplz\_functional](https://cookiedatabase.org/cookie/complianz/cmplz_functional/)
##### Expiration
365 days
##### Function
Store cookie consent preferences
##### Name
[cmplz\_banner-status](https://cookiedatabase.org/cookie/complianz/cmplz_banner-status/)
##### Expiration
365 days
##### Function
Store if the cookie banner has been dismissed
##### Name
[cmplz\_id](https://cookiedatabase.org/cookie/complianz/cmplz_id/)
##### Expiration
365 days
##### Function
Store cookie consent preferences
##### Name
[cmplz\_saved\_categories](https://cookiedatabase.org/cookie/complianz/cmplz_saved_categories/)
##### Expiration
365 days
##### Function
Store cookie consent preferences
##### Name
[cmplz\_saved\_services](https://cookiedatabase.org/cookie/complianz/cmplz_saved_services/)
##### Expiration
365 days
##### Function
Store cookie consent preferences
##### Name
[cmplz\_user\_data](https://cookiedatabase.org/cookie/complianz/cmplz_user_data/)
##### Expiration
365 days
##### Function
Read to determine which cookie banner to show
### Google Analytics
Statistics
Consent to service google-analytics
#### Usage
We use Google Analytics for website statistics. [Read more about Google Analytics](https://cookiedatabase.org/service/google-analytics/)
#### Sharing data
For more information, please read the [Google Analytics Privacy Statement](https://business.safety.google/privacy/).
#### Statistics
##### Name
[\_ga\_\*](https://cookiedatabase.org/cookie/google-analytics/_ga_/)
##### Expiration
1 year
##### Function
Store and count pageviews
##### Name
[\_ga](https://cookiedatabase.org/cookie/google-analytics/_ga/)
##### Expiration
2 years
##### Function
Store and count pageviews
##### Name
[\_gid](https://cookiedatabase.org/cookie/google-analytics/_gid/)
##### Expiration
1 day
##### Function
Store and count pageviews
##### Name
[\_gat\_gtag\_UA\_\*](https://cookiedatabase.org/cookie/google-analytics/_gat_gtag_ua_-2/)
##### Expiration
1 minute
##### Function
Store a unique user ID
### Heap Analytics
Statistics
Consent to service heap-analytics
#### Usage
We use Heap Analytics for website statistics. [Read more about Heap Analytics](https://cookiedatabase.org/service/heap-analytics/)
#### Sharing data
For more information, please read the [Heap Analytics Privacy Statement](https://heap.io/privacy).
#### Statistics
##### Name
[\_hp2\_id.\*](https://cookiedatabase.org/cookie/heap-analytics/_hp2_id/)
##### Expiration
14 months
##### Function
Store and track interaction
##### Name
[\_hp2\_id\_\*](https://cookiedatabase.org/cookie/heap-analytics/_hp2_id_/)
##### Expiration
14 months
##### Function
Store a unique user ID
##### Name
[\_hp2\_ses\_props\*](https://cookiedatabase.org/cookie/heap-analytics/_hp2_ses_props/)
##### Expiration
30 minutes
##### Function
Store performed actions on the website
### Nitropack
Functional
Consent to service nitropack
#### Usage
We use Nitropack for page loading speed improvement. [Read more about Nitropack](https://cookiedatabase.org/service/nitropack/)
#### Sharing data
This data is not shared with third parties.
#### Functional
##### Name
[nitropack\_webhook\_sync](https://cookiedatabase.org/cookie/nitropack/nitropack_webhook_sync/)
##### Expiration
##### Function
Provide functions across pages
### CloudFlare
Functional
Consent to service cloudflare
#### Usage
We use CloudFlare for content distribution network (CDN) services. [Read more about CloudFlare](https://cookiedatabase.org/service/cloudflare/)
#### Sharing data
For more information, please read the [CloudFlare Privacy Statement](https://www.cloudflare.com/privacypolicy).
#### Functional
##### Name
[\_\_cf\_bm](https://cookiedatabase.org/cookie/cloudflare/__cf_bm/)
##### Expiration
30 minutes
##### Function
Read and filter requests from bots
### Twitter
Functional, Marketing
Consent to service twitter
#### Usage
We use Twitter for display of recent social posts and/or social share buttons. [Read more about Twitter](https://cookiedatabase.org/service/twitter/)
#### Sharing data
For more information, please read the [Twitter Privacy Statement](https://twitter.com/en/privacy).
#### Functional
##### Name
[local\_storage\_support\_test](https://cookiedatabase.org/cookie/twitter/local_storage_support_test/)
##### Expiration
persistent
##### Function
Provide load balancing functionality
#### Marketing
##### Name
[metrics\_token](https://cookiedatabase.org/cookie/twitter/metrics_token/)
##### Expiration
persistent
##### Function
Store if the user has seen embedded content
### WP Engine
Purpose pending investigation
Consent to service wp-engine
#### Usage
We use WP Engine for website hosting. [Read more about WP Engine](https://cookiedatabase.org/service/wp-engine/)
#### Sharing data
For more information, please read the [WP Engine Privacy Statement](https://wpengine.com/legal/privacy/).
#### Purpose pending investigation
##### Name
[rtk\_gdpr\_c](https://cookiedatabase.org/cookie/wp-engine/rtk_gdpr_c/)
##### Expiration
session
##### Function
##### Name
[rtkuuid](https://cookiedatabase.org/cookie/wp-engine/rtkuuid/)
##### Expiration
session
##### Function
##### Name
[rtk\_gdpr\_a](https://cookiedatabase.org/cookie/wp-engine/rtk_gdpr_a/)
##### Expiration
session
##### Function
##### Name
[rtk\_p](https://cookiedatabase.org/cookie/wp-engine/rtk_p/)
##### Expiration
session
##### Function
##### Name
[rtk\_sid](https://cookiedatabase.org/cookie/wp-engine/rtk_sid/)
##### Expiration
session
##### Function
##### Name
[rtk\_rps](https://cookiedatabase.org/cookie/wp-engine/rtk_rps/)
##### Expiration
session
##### Function
##### Name
[rtk\_sat](https://cookiedatabase.org/cookie/wp-engine/rtk_sat/)
##### Expiration
session
##### Function
### Zendesk
Statistics
Consent to service zendesk
#### Usage
We use Zendesk for Customer Relations Management. [Read more about Zendesk](https://cookiedatabase.org/service/zendesk/)
#### Sharing data
This data is not shared with third parties.
#### Statistics
##### Name
[ZD-buid](https://cookiedatabase.org/cookie/zendesk/zd-buid/)
##### Expiration
persistent
##### Function
Store a unique user ID
##### Name
[ZD-suid](https://cookiedatabase.org/cookie/zendesk/zd-suid/)
##### Expiration
20 minutes
##### Function
Store a unique session ID
### OptinMonster
Marketing
Consent to service optinmonster
#### Usage
We use OptinMonster for mailing list subscriptions. [Read more about OptinMonster](https://cookiedatabase.org/service/optinmonster/)
#### Sharing data
This data is not shared with third parties.
#### Marketing
##### Name
[omWpApi](https://cookiedatabase.org/cookie/optinmonster/omwpapi/)
##### Expiration
##### Function
### Stripe
Functional
Consent to service stripe
#### Usage
We use Stripe for payment processing. [Read more about Stripe](https://cookiedatabase.org/service/stripe/)
#### Sharing data
For more information, please read the [Stripe Privacy Statement](https://stripe.com/privacy/).
#### Functional
##### Name
[\_\_stripe\_mid](https://cookiedatabase.org/cookie/stripe/__stripe_mid/)
##### Expiration
1 year
##### Function
Provide fraud prevention
### Automattic
Statistics
Consent to service automattic
#### Usage
We use Automattic for website development. [Read more about Automattic](https://cookiedatabase.org/service/automattic/)
#### Sharing data
For more information, please read the [Automattic Privacy Statement](https://automattic.com/cookies/).
#### Statistics
##### Name
[tk\_qs](https://cookiedatabase.org/cookie/automattic/tk_qs/)
##### Expiration
30 minutes
##### Function
Provide functions across pages
### Microsoft Clarity
Statistics, Marketing
Consent to service microsoft-clarity
#### Usage
We use Microsoft Clarity for heat maps and screen recordings. [Read more about Microsoft Clarity](https://cookiedatabase.org/service/microsoft/)
#### Sharing data
For more information, please read the [Microsoft Clarity Privacy Statement](https://www.microsoft.com/en-us/privacy/privacystatement).
#### Statistics
##### Name
[\_cltk](https://cookiedatabase.org/cookie/microsoft/_cltk/)
##### Expiration
##### Function
Store and track interaction
##### Name
[\_clsk](https://cookiedatabase.org/cookie/microsoft/_clsk/)
##### Expiration
1 day
##### Function
Store and combine pageviews by a user into a single session recording
#### Marketing
##### Name
[\_clck](https://cookiedatabase.org/cookie/microsoft/_clck/)
##### Expiration
1 year
##### Function
Store a unique user ID
##### Name
[ANONCHK](https://cookiedatabase.org/cookie/microsoft/anonchk/)
##### Expiration
##### Function
##### Name
[MUID](https://cookiedatabase.org/cookie/microsoft/muid/)
##### Expiration
1 year
##### Function
Store and track visits across websites
### Google Adsense
Statistics, Marketing
Consent to service google-adsense
#### Usage
We use Google Adsense for showing advertisements. [Read more about Google Adsense](https://cookiedatabase.org/service/google-adsense/)
#### Sharing data
For more information, please read the [Google Adsense Privacy Statement](https://business.safety.google/privacy/).
#### Statistics
##### Name
[\_gcl\_ls](https://cookiedatabase.org/cookie/google-adsense/auto-draft-23/)
##### Expiration
##### Function
Store and track interaction
#### Marketing
##### Name
[\_gcl\_au](https://cookiedatabase.org/cookie/google-adsense/_gcl_au/)
##### Expiration
persistent
##### Function
Store and track conversions
##### Name
[google\_adsense\_settings](https://cookiedatabase.org/cookie/google-adsense/google_adsense_settings/)
##### Expiration
persistent
##### Function
Provide ad delivery or retargeting
### WP Google Maps
Functional
Consent to service wp-google-maps
#### Usage
We use WP Google Maps for maps display. [Read more about WP Google Maps](https://cookiedatabase.org/service/wp-google-maps/)
#### Sharing data
This data is not shared with third parties.
#### Functional
##### Name
[wpgmza-api-consent-given](https://cookiedatabase.org/cookie/wp-google-maps/wpgmza-api-consent-given/)
##### Expiration
1 year
##### Function
Store cookie consent preferences
### LinkedIn
Functional, Marketing, Statistics, Preferences
Consent to service linkedin
#### Usage
We use LinkedIn for display of recent social posts and/or social share buttons. [Read more about LinkedIn](https://cookiedatabase.org/service/linkedin/)
#### Sharing data
For more information, please read the [LinkedIn Privacy Statement](https://www.linkedin.com/legal/privacy-policy).
#### Functional
##### Name
[sdsc](https://cookiedatabase.org/cookie/linkedin/auto-draft-20/)
##### Expiration
session
##### Function
Provide load balancing functionality
##### Name
[li\_gc](https://cookiedatabase.org/cookie/linkedin/auto-draft-16/)
##### Expiration
6 months
##### Function
Store cookie consent preferences
##### Name
[BizographicsOptOut](https://cookiedatabase.org/cookie/linkedin/bizographicsoptout/)
##### Expiration
10 years
##### Function
Store privacy preferences
#### Marketing
##### Name
[lms\_ads](https://cookiedatabase.org/cookie/linkedin/auto-draft-19/)
##### Expiration
30 days
##### Function
Store and track visits across websites
##### Name
[\_guid](https://cookiedatabase.org/cookie/linkedin/_guid/)
##### Expiration
90 days
##### Function
Store and track a visitor’s identity
##### Name
[li-oatml](https://cookiedatabase.org/cookie/linkedin/li-oatml/)
##### Expiration
1 month
##### Function
Provide ad delivery or retargeting
##### Name
[li\_sugr](https://cookiedatabase.org/cookie/linkedin/li_sugr/)
##### Expiration
90 days
##### Function
Store and track a visitor’s identity
##### Name
[UserMatchHistory](https://cookiedatabase.org/cookie/linkedin/usermatchhistory/)
##### Expiration
30 days
##### Function
Provide ad delivery or retargeting
#### Statistics
##### Name
[lms\_analytics](https://cookiedatabase.org/cookie/linkedin/auto-draft-18/)
##### Expiration
30 days
##### Function
Store and track a visitor’s identity
##### Name
[AnalyticsSyncHistory](https://cookiedatabase.org/cookie/linkedin/analyticssynchistory/)
##### Expiration
30 days
##### Function
Store and track visits across websites
#### Preferences
##### Name
[li\_alerts](https://cookiedatabase.org/cookie/linkedin/li_alerts/)
##### Expiration
1 year
##### Function
Store if a message has been shown
##### Name
[bcookie](https://cookiedatabase.org/cookie/linkedin/bcookie-2/)
##### Expiration
1 year
##### Function
Store browser details
##### Name
[lidc](https://cookiedatabase.org/cookie/linkedin/lidc/)
##### Expiration
1 day
##### Function
Provide load balancing functionality
##### Name
[bscookie](https://cookiedatabase.org/cookie/linkedin/bscookie/)
##### Expiration
1 year
##### Function
Store logged in users
### Miscellaneous
Purpose pending investigation
Consent to service miscellaneous
#### Usage
#### Sharing data
Sharing of data is pending investigation
#### Purpose pending investigation
##### Name
nitroPv
##### Expiration
##### Function
##### Name
nitroVisitor
##### Expiration
##### Function
##### Name
WP_DATA_USER_4
##### Expiration
##### Function
##### Name
lastExternalReferrer
##### Expiration
##### Function
##### Name
lastExternalReferrerTime
##### Expiration
##### Function
##### Name
NPTelemetryMeta:lastpv
##### Expiration
##### Function
##### Name
endpage
##### Expiration
##### Function
##### Name
exitintent_show
##### Expiration
##### Function
##### Name
nitroScrollPos
##### Expiration
##### Function
##### Name
nitro_prefetched_urls
##### Expiration
##### Function
##### Name
nitroTargetUrl
##### Expiration
##### Function
##### Name
nitroNavStartTime
##### Expiration
##### Function
##### Name
predictStrategy
##### Expiration
##### Function
##### Name
[\*.appUserId](https://cookiedatabase.org/cookie/unknown-service/appuserid/)
##### Expiration
##### Function
##### Name
[\*.clientId](https://cookiedatabase.org/cookie/unknown-service/clientid/)
##### Expiration
##### Function
##### Name
monsterinsights_sitespeed_current_device
##### Expiration
##### Function
##### Name
[autotrack:\*:session](https://cookiedatabase.org/cookie/unknown-service/autotracksession/)
##### Expiration
##### Function
##### Name
activated_addons
##### Expiration
##### Function
##### Name
jetpack-ai-jwt-token
##### Expiration
##### Function
##### Name
AMP-CONSENT
##### Expiration
##### Function
##### Name
nitroDeviceSpeed
##### Expiration
##### Function
##### Name
predictStrategyOnPrevPage
##### Expiration
##### Function
##### Name
NitroUX:Aggregated:1710191674283h50osexp1t
##### Expiration
##### Function
##### Name
nitroVisitorJourney
##### Expiration
##### Function
##### Name
NitroUX:Aggregated:1711922806992c32ghg9gbq
##### Expiration
##### Function
##### Name
nitroVisitorId
##### Expiration
##### Function
##### Name
NitroPack:visitorJourney
##### Expiration
##### Function
##### Name
NitroPack:pv
##### Expiration
##### Function
##### Name
NitroPack:NPTelemetryMeta:lastpv
##### Expiration
##### Function
##### Name
NitroPack:nitroDeviceSpeed
##### Expiration
##### Function
##### Name
NitroPack:visitorId
##### Expiration
##### Function
##### Name
NitroPack:targetUrl
##### Expiration
##### Function
##### Name
adobeCleanFontAdded
##### Expiration
##### Function
##### Name
[cf\_\*](https://cookiedatabase.org/cookie/unknown-service/cf_/)
##### Expiration
##### Function
##### Name
topicsLastReferenceTime
##### Expiration
##### Function
##### Name
wpe_backup_dismiss_timestamp
##### Expiration
##### Function
## 4. Browser and Device based Consent
When you visit our website for the first time, we will show you a pop-up with an explanation about cookies. Non-functional cookies and similar technologies are not placed until you actively provide consent. As soon as you click on “Accept”, you consent to us using the cookies and plug-ins as described in the pop-up and this Cookie Policy. You can withdraw or change your consent at any time.
### 4.1 Manage your consent settings
You have loaded the Cookie Policy without javascript support. On AMP, you can use the manage consent button on the bottom of the page.
## 5. Enabling/disabling and deleting cookies
You can use your internet browser to automatically or manually delete cookies. You can also specify that certain cookies may not be placed. Another option is to change the settings of your internet browser so that you receive a message each time a cookie is placed. For more information about these options, please refer to the instructions in the Help section of your browser.
Please note that our website may not work properly if all cookies are disabled. If you do delete the cookies in your browser, they will be placed again after your consent when you visit our website again.
## 6. Your rights with respect to personal data
You have the following rights with respect to your personal data:
- you may submit a request for access to the data we process about you;
- you may object to the processing;
- you may request an overview, in a commonly used format, of the data we process about you;
- you may request correction or deletion of the data if it is incorrect or not or no longer relevant, or to ask to restrict the processing of the data.
To exercise these rights, please contact us. Please refer to the contact details at the bottom of this Cookie Policy. If you have a complaint about how we handle your data, we would like to hear from you.
For more information about your rights with respect to personal data, please refer to our [Privacy Statement](https://independentadvisorsnw.com/about/privacy-policy/)
## 7. Contact details
For questions and/or comments about our Cookie Policy and this statement, please contact us by using the following contact details:
Independent Investment Advisors
9620 NE Tanasbourne Dr Suite 300, Hillsboro, OR 97124
United States
Website:
Email: info@ex.comindependentadvisorsnw.com
Phone number: 971.350.8068
This Cookie Policy was synchronized with [cookiedatabase.org](https://cookiedatabase.org/) on September 4, 2026.
---
### [Imprint](https://independentadvisorsnw.com/opt-out-preferences-2/)
**Published:** November 8, 2022
**Author:** MMGI Admin
**Content:**
*This page was last changed on August 28, 2026, last checked on August 28, 2026 and applies to citizens and legal permanent residents of the United States.*
## 1. Introduction
Our website, (hereinafter: “the website”) uses cookies and other related technologies (for convenience all technologies are referred to as “cookies”). Cookies are also placed by third parties we have engaged. In the document below we inform you about the use of cookies on our website.
We apply a prior-consent (opt-in) model on this website: non-functional cookies and similar tracking technologies are blocked and are not placed until you actively give your consent. You can grant, withdraw, or change your consent at any time.
We do not sell or share personal information to third parties for monetary consideration; however, we may disclose certain personal information to third parties under circumstances that might be deemed a “sale” or ”Sharing” for residents of Oregon (OCPA), California (CPRA), Colorado (CPA), Montana (MCDPA) and Utah (UCPA). We respect and understand that you may want to be sure that your personal information is not being sold or shared. You may request that we exclude your personal information from such arrangements, or direct us to limit the use and disclosure of possible sensitive personal information, by entering your name and email address below. You may need to provide additional identifying information before we can process your request.
×
Name Name
Email
Global opt-out from selling and sharing my personal information and limiting the use or disclosure of sensitive personal information.
Do not sell my personal information for cross-context behavioral advertising
Limit the use of my sensitive personal information
Request for access
Right to be Forgotten
Right to Data Portability
## 2. Cookies
When you visit our website it can be necessary to store and/or read certain data from your device by using technologies such as cookies.
### 2.1 Technical or functional cookies
Some cookies ensure that certain parts of the website work properly and that your user preferences remain known. By placing functional cookies, we make it easier for you to visit our website. This way, you do not need to repeatedly enter the same information when visiting our website and, for example, the items remain in your shopping cart until you have paid. We may place these cookies without your consent.
### 2.2 Statistics cookies
We use statistics cookies to optimize the website experience for our users. With these statistics cookies we get insights in the usage of our website.
### 2.3 Marketing/Tracking cookies
Marketing/Tracking cookies are cookies or any other form of local storage, used to create user profiles to display advertising or to track the user on this website or across several websites for similar marketing purposes.
### 2.4 Social media
On our website, we have included content from Facebook, X (Formerly Twitter), Instagram and LinkedIn to promote web pages (e.g. “like”, “pin”) or share (e.g. “tweet”) on social networks like Facebook, X (Formerly Twitter), Instagram and LinkedIn. This content is embedded with code derived from Facebook, X (Formerly Twitter), Instagram and LinkedIn and places cookies. This content might store and process certain information for personalized advertising.
Please read the privacy statement of these social networks (which can change regularly) to read what they do with your (personal) data which they process using these cookies. The data that is retrieved is anonymized as much as possible. Facebook, X (Formerly Twitter), Instagram and LinkedIn are located in the United States.
## 3. Placed cookies
Most of these technologies have a function, a purpose, and an expiration period.
1. A function is a particular task a technology has. So a function can be to “store certain data.”
2. Purpose is “the Why” behind the function. Maybe the data is stored because it is needed for statistics.
3. The expiration period shows the length of the period the used technology can “store or read certain data.”
### Tidio Live Chat
Functional
Consent to service tidio-live-chat
#### Usage
We use Tidio Live Chat for chat support. [Read more about Tidio Live Chat](https://cookiedatabase.org/service/tidio-live-chat/)
#### Sharing data
For more information, please read the [Tidio Live Chat Privacy Statement](https://www.tidio.com/privacy-policy/).
#### Functional
##### Name
[tidio\_state\_\*](https://cookiedatabase.org/cookie/tidio-live-chat/tidio_state_/)
##### Expiration
##### Function
### WordPress
Functional
Consent to service wordpress
#### Usage
We use WordPress for website development. [Read more about WordPress](https://cookiedatabase.org/service/wordpress/)
#### Sharing data
This data is not shared with third parties.
#### Functional
##### Name
[wpEmojiSettingsSupports](https://cookiedatabase.org/cookie/wordpress/wpemojisettingssupports/)
##### Expiration
session
##### Function
Store browser details
### Facebook
Marketing, Functional
Consent to service facebook
#### Usage
We use Facebook for display of recent social posts and/or social share buttons. [Read more about Facebook](https://cookiedatabase.org/service/facebook/)
#### Sharing data
For more information, please read the [Facebook Privacy Statement](https://www.facebook.com/policy/cookies).
#### Marketing
##### Name
[\_fbp](https://cookiedatabase.org/cookie/facebook/_fbp/)
##### Expiration
3 months
##### Function
Store and track visits across websites
##### Name
[\_fbc](https://cookiedatabase.org/cookie/facebook/_fbc/)
##### Expiration
2 years
##### Function
Store last visit
##### Name
[fbm\*](https://cookiedatabase.org/cookie/facebook/fbm_/)
##### Expiration
1 year
##### Function
Store account details
##### Name
[xs](https://cookiedatabase.org/cookie/facebook/xs/)
##### Expiration
3 months
##### Function
Store a unique session ID
##### Name
[fr](https://cookiedatabase.org/cookie/facebook/fr/)
##### Expiration
3 months
##### Function
Provide ad delivery or retargeting
##### Name
[act](https://cookiedatabase.org/cookie/facebook/act/)
##### Expiration
90 days
##### Function
Store logged in users
##### Name
[datr](https://cookiedatabase.org/cookie/facebook/datr/)
##### Expiration
2 years
##### Function
Provide fraud prevention
##### Name
[c\_user](https://cookiedatabase.org/cookie/facebook/c_user/)
##### Expiration
30 days
##### Function
Store a unique user ID
##### Name
[sb](https://cookiedatabase.org/cookie/facebook/sb/)
##### Expiration
2 years
##### Function
Store browser details
##### Name
[\*\_fbm\_](https://cookiedatabase.org/cookie/facebook/_fbm_/)
##### Expiration
1 year
##### Function
Store account details
#### Functional
##### Name
[wd](https://cookiedatabase.org/cookie/facebook/wd/)
##### Expiration
1 week
##### Function
Read screen resolution
##### Name
[csm](https://cookiedatabase.org/cookie/facebook/csm/)
##### Expiration
90 days
##### Function
Provide fraud prevention
##### Name
[actppresence](https://cookiedatabase.org/cookie/facebook/actppresence/)
##### Expiration
session
##### Function
Store and track if the browser tab is active
### Complianz
Functional
Consent to service complianz
#### Usage
We use Complianz for cookie consent management. [Read more about Complianz](https://cookiedatabase.org/service/complianz/)
#### Sharing data
This data is not shared with third parties. For more information, please read the [Complianz Privacy Statement](https://complianz.io/legal/privacy-statement/).
#### Functional
##### Name
[cmplz\_policy\_id](https://cookiedatabase.org/cookie/complianz/cmplz_policy_id/)
##### Expiration
365 days
##### Function
Store accepted cookie policy ID
##### Name
[cmplz\_consented\_services](https://cookiedatabase.org/cookie/complianz/cmplz_consented_services/)
##### Expiration
365 days
##### Function
Store cookie consent preferences
##### Name
[cmplz\_marketing](https://cookiedatabase.org/cookie/complianz/cmplz_marketing/)
##### Expiration
365 days
##### Function
Store cookie consent preferences
##### Name
[cmplz\_statistics](https://cookiedatabase.org/cookie/complianz/cmplz_statistics/)
##### Expiration
365 days
##### Function
Store cookie consent preferences
##### Name
[cmplz\_preferences](https://cookiedatabase.org/cookie/complianz/cmplz_preferences/)
##### Expiration
365 days
##### Function
Store cookie consent preferences
##### Name
[cmplz\_functional](https://cookiedatabase.org/cookie/complianz/cmplz_functional/)
##### Expiration
365 days
##### Function
Store cookie consent preferences
##### Name
[cmplz\_banner-status](https://cookiedatabase.org/cookie/complianz/cmplz_banner-status/)
##### Expiration
365 days
##### Function
Store if the cookie banner has been dismissed
##### Name
[cmplz\_id](https://cookiedatabase.org/cookie/complianz/cmplz_id/)
##### Expiration
365 days
##### Function
Store cookie consent preferences
##### Name
[cmplz\_saved\_categories](https://cookiedatabase.org/cookie/complianz/cmplz_saved_categories/)
##### Expiration
365 days
##### Function
Store cookie consent preferences
##### Name
[cmplz\_saved\_services](https://cookiedatabase.org/cookie/complianz/cmplz_saved_services/)
##### Expiration
365 days
##### Function
Store cookie consent preferences
##### Name
[cmplz\_user\_data](https://cookiedatabase.org/cookie/complianz/cmplz_user_data/)
##### Expiration
365 days
##### Function
Read to determine which cookie banner to show
### Google Analytics
Statistics
Consent to service google-analytics
#### Usage
We use Google Analytics for website statistics. [Read more about Google Analytics](https://cookiedatabase.org/service/google-analytics/)
#### Sharing data
For more information, please read the [Google Analytics Privacy Statement](https://business.safety.google/privacy/).
#### Statistics
##### Name
[\_ga\_\*](https://cookiedatabase.org/cookie/google-analytics/_ga_/)
##### Expiration
1 year
##### Function
Store and count pageviews
##### Name
[\_ga](https://cookiedatabase.org/cookie/google-analytics/_ga/)
##### Expiration
2 years
##### Function
Store and count pageviews
##### Name
[\_gid](https://cookiedatabase.org/cookie/google-analytics/_gid/)
##### Expiration
1 day
##### Function
Store and count pageviews
##### Name
[\_gat\_gtag\_UA\_\*](https://cookiedatabase.org/cookie/google-analytics/_gat_gtag_ua_-2/)
##### Expiration
1 minute
##### Function
Store a unique user ID
### Heap Analytics
Statistics
Consent to service heap-analytics
#### Usage
We use Heap Analytics for website statistics. [Read more about Heap Analytics](https://cookiedatabase.org/service/heap-analytics/)
#### Sharing data
For more information, please read the [Heap Analytics Privacy Statement](https://heap.io/privacy).
#### Statistics
##### Name
[\_hp2\_id.\*](https://cookiedatabase.org/cookie/heap-analytics/_hp2_id/)
##### Expiration
14 months
##### Function
Store and track interaction
##### Name
[\_hp2\_id\_\*](https://cookiedatabase.org/cookie/heap-analytics/_hp2_id_/)
##### Expiration
14 months
##### Function
Store a unique user ID
##### Name
[\_hp2\_ses\_props\*](https://cookiedatabase.org/cookie/heap-analytics/_hp2_ses_props/)
##### Expiration
30 minutes
##### Function
Store performed actions on the website
### Nitropack
Functional
Consent to service nitropack
#### Usage
We use Nitropack for page loading speed improvement. [Read more about Nitropack](https://cookiedatabase.org/service/nitropack/)
#### Sharing data
This data is not shared with third parties.
#### Functional
##### Name
[nitropack\_webhook\_sync](https://cookiedatabase.org/cookie/nitropack/nitropack_webhook_sync/)
##### Expiration
##### Function
Provide functions across pages
### CloudFlare
Functional
Consent to service cloudflare
#### Usage
We use CloudFlare for content distribution network (CDN) services. [Read more about CloudFlare](https://cookiedatabase.org/service/cloudflare/)
#### Sharing data
For more information, please read the [CloudFlare Privacy Statement](https://www.cloudflare.com/privacypolicy).
#### Functional
##### Name
[\_\_cf\_bm](https://cookiedatabase.org/cookie/cloudflare/__cf_bm/)
##### Expiration
30 minutes
##### Function
Read and filter requests from bots
### Twitter
Functional, Marketing
Consent to service twitter
#### Usage
We use Twitter for display of recent social posts and/or social share buttons. [Read more about Twitter](https://cookiedatabase.org/service/twitter/)
#### Sharing data
For more information, please read the [Twitter Privacy Statement](https://twitter.com/en/privacy).
#### Functional
##### Name
[local\_storage\_support\_test](https://cookiedatabase.org/cookie/twitter/local_storage_support_test/)
##### Expiration
persistent
##### Function
Provide load balancing functionality
#### Marketing
##### Name
[metrics\_token](https://cookiedatabase.org/cookie/twitter/metrics_token/)
##### Expiration
persistent
##### Function
Store if the user has seen embedded content
### WP Engine
Purpose pending investigation
Consent to service wp-engine
#### Usage
We use WP Engine for website hosting. [Read more about WP Engine](https://cookiedatabase.org/service/wp-engine/)
#### Sharing data
For more information, please read the [WP Engine Privacy Statement](https://wpengine.com/legal/privacy/).
#### Purpose pending investigation
##### Name
[rtk\_gdpr\_c](https://cookiedatabase.org/cookie/wp-engine/rtk_gdpr_c/)
##### Expiration
session
##### Function
##### Name
[rtkuuid](https://cookiedatabase.org/cookie/wp-engine/rtkuuid/)
##### Expiration
session
##### Function
##### Name
[rtk\_gdpr\_a](https://cookiedatabase.org/cookie/wp-engine/rtk_gdpr_a/)
##### Expiration
session
##### Function
##### Name
[rtk\_p](https://cookiedatabase.org/cookie/wp-engine/rtk_p/)
##### Expiration
session
##### Function
##### Name
[rtk\_sid](https://cookiedatabase.org/cookie/wp-engine/rtk_sid/)
##### Expiration
session
##### Function
##### Name
[rtk\_rps](https://cookiedatabase.org/cookie/wp-engine/rtk_rps/)
##### Expiration
session
##### Function
##### Name
[rtk\_sat](https://cookiedatabase.org/cookie/wp-engine/rtk_sat/)
##### Expiration
session
##### Function
### Zendesk
Statistics
Consent to service zendesk
#### Usage
We use Zendesk for Customer Relations Management. [Read more about Zendesk](https://cookiedatabase.org/service/zendesk/)
#### Sharing data
This data is not shared with third parties.
#### Statistics
##### Name
[ZD-buid](https://cookiedatabase.org/cookie/zendesk/zd-buid/)
##### Expiration
persistent
##### Function
Store a unique user ID
##### Name
[ZD-suid](https://cookiedatabase.org/cookie/zendesk/zd-suid/)
##### Expiration
20 minutes
##### Function
Store a unique session ID
### OptinMonster
Marketing
Consent to service optinmonster
#### Usage
We use OptinMonster for mailing list subscriptions. [Read more about OptinMonster](https://cookiedatabase.org/service/optinmonster/)
#### Sharing data
This data is not shared with third parties.
#### Marketing
##### Name
[omWpApi](https://cookiedatabase.org/cookie/optinmonster/omwpapi/)
##### Expiration
##### Function
### Stripe
Functional
Consent to service stripe
#### Usage
We use Stripe for payment processing. [Read more about Stripe](https://cookiedatabase.org/service/stripe/)
#### Sharing data
For more information, please read the [Stripe Privacy Statement](https://stripe.com/privacy/).
#### Functional
##### Name
[\_\_stripe\_mid](https://cookiedatabase.org/cookie/stripe/__stripe_mid/)
##### Expiration
1 year
##### Function
Provide fraud prevention
### Automattic
Statistics
Consent to service automattic
#### Usage
We use Automattic for website development. [Read more about Automattic](https://cookiedatabase.org/service/automattic/)
#### Sharing data
For more information, please read the [Automattic Privacy Statement](https://automattic.com/cookies/).
#### Statistics
##### Name
[tk\_qs](https://cookiedatabase.org/cookie/automattic/tk_qs/)
##### Expiration
30 minutes
##### Function
Provide functions across pages
### Microsoft Clarity
Statistics, Marketing
Consent to service microsoft-clarity
#### Usage
We use Microsoft Clarity for heat maps and screen recordings. [Read more about Microsoft Clarity](https://cookiedatabase.org/service/microsoft/)
#### Sharing data
For more information, please read the [Microsoft Clarity Privacy Statement](https://www.microsoft.com/en-us/privacy/privacystatement).
#### Statistics
##### Name
[\_cltk](https://cookiedatabase.org/cookie/microsoft/_cltk/)
##### Expiration
##### Function
Store and track interaction
##### Name
[\_clsk](https://cookiedatabase.org/cookie/microsoft/_clsk/)
##### Expiration
1 day
##### Function
Store and combine pageviews by a user into a single session recording
#### Marketing
##### Name
[\_clck](https://cookiedatabase.org/cookie/microsoft/_clck/)
##### Expiration
1 year
##### Function
Store a unique user ID
##### Name
[ANONCHK](https://cookiedatabase.org/cookie/microsoft/anonchk/)
##### Expiration
##### Function
##### Name
[MUID](https://cookiedatabase.org/cookie/microsoft/muid/)
##### Expiration
1 year
##### Function
Store and track visits across websites
### Google Adsense
Statistics, Marketing
Consent to service google-adsense
#### Usage
We use Google Adsense for showing advertisements. [Read more about Google Adsense](https://cookiedatabase.org/service/google-adsense/)
#### Sharing data
For more information, please read the [Google Adsense Privacy Statement](https://business.safety.google/privacy/).
#### Statistics
##### Name
[\_gcl\_ls](https://cookiedatabase.org/cookie/google-adsense/auto-draft-23/)
##### Expiration
##### Function
Store and track interaction
#### Marketing
##### Name
[\_gcl\_au](https://cookiedatabase.org/cookie/google-adsense/_gcl_au/)
##### Expiration
persistent
##### Function
Store and track conversions
##### Name
[google\_adsense\_settings](https://cookiedatabase.org/cookie/google-adsense/google_adsense_settings/)
##### Expiration
persistent
##### Function
Provide ad delivery or retargeting
### WP Google Maps
Functional
Consent to service wp-google-maps
#### Usage
We use WP Google Maps for maps display. [Read more about WP Google Maps](https://cookiedatabase.org/service/wp-google-maps/)
#### Sharing data
This data is not shared with third parties.
#### Functional
##### Name
[wpgmza-api-consent-given](https://cookiedatabase.org/cookie/wp-google-maps/wpgmza-api-consent-given/)
##### Expiration
1 year
##### Function
Store cookie consent preferences
### LinkedIn
Functional, Marketing, Statistics, Preferences
Consent to service linkedin
#### Usage
We use LinkedIn for display of recent social posts and/or social share buttons. [Read more about LinkedIn](https://cookiedatabase.org/service/linkedin/)
#### Sharing data
For more information, please read the [LinkedIn Privacy Statement](https://www.linkedin.com/legal/privacy-policy).
#### Functional
##### Name
[sdsc](https://cookiedatabase.org/cookie/linkedin/auto-draft-20/)
##### Expiration
session
##### Function
Provide load balancing functionality
##### Name
[li\_gc](https://cookiedatabase.org/cookie/linkedin/auto-draft-16/)
##### Expiration
6 months
##### Function
Store cookie consent preferences
##### Name
[BizographicsOptOut](https://cookiedatabase.org/cookie/linkedin/bizographicsoptout/)
##### Expiration
10 years
##### Function
Store privacy preferences
#### Marketing
##### Name
[lms\_ads](https://cookiedatabase.org/cookie/linkedin/auto-draft-19/)
##### Expiration
30 days
##### Function
Store and track visits across websites
##### Name
[\_guid](https://cookiedatabase.org/cookie/linkedin/_guid/)
##### Expiration
90 days
##### Function
Store and track a visitor’s identity
##### Name
[li-oatml](https://cookiedatabase.org/cookie/linkedin/li-oatml/)
##### Expiration
1 month
##### Function
Provide ad delivery or retargeting
##### Name
[li\_sugr](https://cookiedatabase.org/cookie/linkedin/li_sugr/)
##### Expiration
90 days
##### Function
Store and track a visitor’s identity
##### Name
[UserMatchHistory](https://cookiedatabase.org/cookie/linkedin/usermatchhistory/)
##### Expiration
30 days
##### Function
Provide ad delivery or retargeting
#### Statistics
##### Name
[lms\_analytics](https://cookiedatabase.org/cookie/linkedin/auto-draft-18/)
##### Expiration
30 days
##### Function
Store and track a visitor’s identity
##### Name
[AnalyticsSyncHistory](https://cookiedatabase.org/cookie/linkedin/analyticssynchistory/)
##### Expiration
30 days
##### Function
Store and track visits across websites
#### Preferences
##### Name
[li\_alerts](https://cookiedatabase.org/cookie/linkedin/li_alerts/)
##### Expiration
1 year
##### Function
Store if a message has been shown
##### Name
[bcookie](https://cookiedatabase.org/cookie/linkedin/bcookie-2/)
##### Expiration
1 year
##### Function
Store browser details
##### Name
[lidc](https://cookiedatabase.org/cookie/linkedin/lidc/)
##### Expiration
1 day
##### Function
Provide load balancing functionality
##### Name
[bscookie](https://cookiedatabase.org/cookie/linkedin/bscookie/)
##### Expiration
1 year
##### Function
Store logged in users
### Miscellaneous
Purpose pending investigation
Consent to service miscellaneous
#### Usage
#### Sharing data
Sharing of data is pending investigation
#### Purpose pending investigation
##### Name
nitroPv
##### Expiration
##### Function
##### Name
nitroVisitor
##### Expiration
##### Function
##### Name
WP_DATA_USER_4
##### Expiration
##### Function
##### Name
lastExternalReferrer
##### Expiration
##### Function
##### Name
lastExternalReferrerTime
##### Expiration
##### Function
##### Name
NPTelemetryMeta:lastpv
##### Expiration
##### Function
##### Name
endpage
##### Expiration
##### Function
##### Name
exitintent_show
##### Expiration
##### Function
##### Name
nitroScrollPos
##### Expiration
##### Function
##### Name
nitro_prefetched_urls
##### Expiration
##### Function
##### Name
nitroTargetUrl
##### Expiration
##### Function
##### Name
nitroNavStartTime
##### Expiration
##### Function
##### Name
predictStrategy
##### Expiration
##### Function
##### Name
[\*.appUserId](https://cookiedatabase.org/cookie/unknown-service/appuserid/)
##### Expiration
##### Function
##### Name
[\*.clientId](https://cookiedatabase.org/cookie/unknown-service/clientid/)
##### Expiration
##### Function
##### Name
monsterinsights_sitespeed_current_device
##### Expiration
##### Function
##### Name
[autotrack:\*:session](https://cookiedatabase.org/cookie/unknown-service/autotracksession/)
##### Expiration
##### Function
##### Name
activated_addons
##### Expiration
##### Function
##### Name
jetpack-ai-jwt-token
##### Expiration
##### Function
##### Name
AMP-CONSENT
##### Expiration
##### Function
##### Name
nitroDeviceSpeed
##### Expiration
##### Function
##### Name
predictStrategyOnPrevPage
##### Expiration
##### Function
##### Name
NitroUX:Aggregated:1710191674283h50osexp1t
##### Expiration
##### Function
##### Name
nitroVisitorJourney
##### Expiration
##### Function
##### Name
NitroUX:Aggregated:1711922806992c32ghg9gbq
##### Expiration
##### Function
##### Name
nitroVisitorId
##### Expiration
##### Function
##### Name
NitroPack:visitorJourney
##### Expiration
##### Function
##### Name
NitroPack:pv
##### Expiration
##### Function
##### Name
NitroPack:NPTelemetryMeta:lastpv
##### Expiration
##### Function
##### Name
NitroPack:nitroDeviceSpeed
##### Expiration
##### Function
##### Name
NitroPack:visitorId
##### Expiration
##### Function
##### Name
NitroPack:targetUrl
##### Expiration
##### Function
##### Name
adobeCleanFontAdded
##### Expiration
##### Function
##### Name
[cf\_\*](https://cookiedatabase.org/cookie/unknown-service/cf_/)
##### Expiration
##### Function
##### Name
topicsLastReferenceTime
##### Expiration
##### Function
##### Name
wpe_backup_dismiss_timestamp
##### Expiration
##### Function
## 4. Browser and Device based Consent
When you visit our website for the first time, we will show you a pop-up with an explanation about cookies. Non-functional cookies and similar technologies are not placed until you actively provide consent. As soon as you click on “Accept”, you consent to us using the cookies and plug-ins as described in the pop-up and this Cookie Policy. You can withdraw or change your consent at any time.
### 4.1 Manage your consent settings
You have loaded the Cookie Policy without javascript support. On AMP, you can use the manage consent button on the bottom of the page.
## 5. Enabling/disabling and deleting cookies
You can use your internet browser to automatically or manually delete cookies. You can also specify that certain cookies may not be placed. Another option is to change the settings of your internet browser so that you receive a message each time a cookie is placed. For more information about these options, please refer to the instructions in the Help section of your browser.
Please note that our website may not work properly if all cookies are disabled. If you do delete the cookies in your browser, they will be placed again after your consent when you visit our website again.
## 6. Your rights with respect to personal data
You have the following rights with respect to your personal data:
- you may submit a request for access to the data we process about you;
- you may object to the processing;
- you may request an overview, in a commonly used format, of the data we process about you;
- you may request correction or deletion of the data if it is incorrect or not or no longer relevant, or to ask to restrict the processing of the data.
To exercise these rights, please contact us. Please refer to the contact details at the bottom of this Cookie Policy. If you have a complaint about how we handle your data, we would like to hear from you.
For more information about your rights with respect to personal data, please refer to our [Privacy Statement](https://independentadvisorsnw.com/about/privacy-policy/)
## 7. Contact details
For questions and/or comments about our Cookie Policy and this statement, please contact us by using the following contact details:
Independent Investment Advisors
9620 NE Tanasbourne Dr Suite 300, Hillsboro, OR 97124
United States
Website:
Email: info@ex.comindependentadvisorsnw.com
Phone number: 971.350.8068
This Cookie Policy was synchronized with [cookiedatabase.org](https://cookiedatabase.org/) on September 4, 2026.
---
## Downloads
### [Can I Make a Backdoor Roth IRA Contribution? (2026 Decision Guide)](https://independentadvisorsnw.com/download/3053/?tmstv=1788998122)
**Published:** April 17, 2026
**Author:** MMGI Admin
**Content:**
### Can I Make a Backdoor Roth IRA Contribution? (2026 Decision Guide)
This flowchart helps determine whether a Backdoor Roth IRA contribution is appropriate based on income, existing IRA balances, and employer retirement plan options. It outlines the key considerations that often impact the tax outcome of a conversion, including the aggregation and pro rata rules that apply when pre-tax IRA assets are present. The guide also walks through the basic steps involved in completing a Backdoor Roth contribution—from making a non-deductible IRA contribution to converting the funds into a Roth IRA—helping individuals avoid common planning mistakes.
---
### [Can I Contribute to a Roth IRA? (2026 Eligibility Flowchart)](https://independentadvisorsnw.com/download/3049/?tmstv=1788998122)
**Published:** April 17, 2026
**Author:** MMGI Admin
**Content:**
### Can I Contribute to a Roth IRA? (2026 Eligibility Flowchart)
This decision flowchart helps determine whether you are eligible to contribute to a Roth IRA based on income, filing status, and earned income requirements. It walks through the key thresholds that govern full, partial, or ineligible contributions, including the 2026 contribution limits of up to **$7,500 (or $8,600 if age 50 or older)** and the income phaseout ranges that apply to single and married taxpayers. This guide is especially useful for year-end tax planning and retirement savings decisions
---
### [Financial Planning Milestones by Age (2026 Guide)](https://independentadvisorsnw.com/download/3045/?tmstv=1788998122)
**Published:** April 17, 2026
**Author:** MMGI Admin
**Content:**
### Important Financial Planning Milestones by Age (2026 Guide)
This guide outlines key financial planning milestones that occur at different ages throughout life, helping individuals anticipate important eligibility rules and planning opportunities before they arise. It highlights critical ages related to retirement contributions, Social Security benefits, Medicare enrollment, Required Minimum Distributions (RMDs), and other planning triggers that often drive financial and tax decisions. Having visibility into these milestones can help families avoid missed deadlines and make more informed long-term planning decisions.
---
### [Important Numbers 2026](https://independentadvisorsnw.com/download/3042/?tmstv=1788998122)
**Published:** April 17, 2026
**Author:** MMGI Admin
**Content:**
### 2026 Important Financial Planning Numbers
This quick-reference guide summarizes many of the key tax thresholds, retirement plan limits, and planning figures that frequently change each year. It is designed to help individuals and families stay informed about important numbers that can influence contribution decisions, tax planning strategies, and retirement planning opportunities. The guide includes updated limits for retirement accounts, income tax brackets, Social Security thresholds, Medicare premiums, and other commonly referenced planning figures for 2026.
---
### [Reviewing My Property And Casualty Insurance Policies](https://independentadvisorsnw.com/download/2685/?tmstv=1788998122)
**Published:** September 18, 2023
**Author:** MMGI Admin
**Excerpt:** A client’s property and casualty insurance policies are a key part of their overall financial plan. It’s important to review these policies each year to ensure that your client has the coverage they need.
**Content:**
A client’s property and casualty insurance policies are a key part of their overall financial plan. It’s important to review these policies each year to ensure that your client has the coverage they need. If there are gaps, you can work with your client to implement proper coverage.
In this checklist we focus on issues to consider when [reviewing your client’s policies,](https://independentadvisorsnw.com/?post_type=dlm_download&p=2688) including:
Real Estate/Property Insurance
- Did the client buy or sell a primary residence or vacation property? It’s important to review their coverage, and perhaps their insurer, in order to ensure that the policies cover an adequate amount of the property’s replacement value.
- Has the client made substantial improvements to the property or has the property appreciated significantly in value? They need to be sure that their coverage keeps up with any increases in the value of the property.
Auto Insurance
- The client should review their collision and comprehensive coverage. Depending upon the age of the vehicle and other factors, they may want to make some adjustments.
- Are the client’s children now of driving age? If so, they need to be sure that the children are covered as drivers and that their liability limits are adequate.
Personal Property and Umbrella Insurance
- If the client owns personal property with a value that exceeds the ordinary policy limits, they may need to schedule these items to ensure coverage.
- If the client needs additional liability coverage over and above what their homeowner’s policy offers, they may need an umbrella policy.
This is a comprehensive checklist of the types of issues that advisors should be discussing with their clients when reviewing their property and casualty insurance policies. These types of policies play a key part in their overall financial planning and in protecting their family’s assets from losses of all magnitudes.
---
### [Can I Contribute to a Roth IRA in 2025?](https://independentadvisorsnw.com/download/2968/?tmstv=1788998122)
**Published:** May 14, 2025
**Author:** MMGI Admin
**Excerpt:** Confused about Roth IRA contribution rules for 2025?
Our free downloadable flowchart breaks it all down—clearly, visually, and with updated IRS income limits. Whether you're filing solo or jointly, this tool helps you determine eligibility in seconds.
**Content:**
**Confused about Roth IRA contribution rules for 2025?**
Our free downloadable flowchart breaks it all down—clearly, visually, and with updated IRS income limits. Whether you’re filing solo or jointly, this tool helps you determine eligibility in seconds.
---
### [Important Numbers 2023](https://independentadvisorsnw.com/download/2710/?tmstv=1788998122)
**Published:** November 7, 2023
**Author:** MMGI Admin
**Excerpt:** Important Financial & Tax Numbers of 2023.
**Content:**
Important Financial & Tax Numbers of 2023.
---
### [Reviewing My Health And Life Insurance Policies](https://independentadvisorsnw.com/download/2688/?tmstv=1788998122)
**Published:** September 18, 2023
**Author:** MMGI Admin
**Excerpt:** A client’s life and health insurance policies are a key part of their overall financial plan. It’s important to review these policies each year to ensure that your client has the coverage they need. If there are gaps, you can work with your client to implement proper coverage.
**Content:**
A client’s life and health insurance policies are a key part of their overall financial plan. It’s important to review these policies each year to ensure that your client has the coverage they need. If there are gaps, you can work with your client to implement proper coverage.
In this checklist, we focus on issues to consider when reviewing your client’s policies, including:
Health Insurance
- If clients are married and both have access to health coverage, does it make sense for them to each take their own coverage or to choose the better of the two plans to cover both?
- If the client is paying for coverage on their own, has their situation changed such that they should consider shopping for a new policy?
- If the client is retired and on Medicare, they should review their situation each year to see if they need to make any changes during the annual enrollment period. They also need to ensure that they either have creditable drug coverage or that they select a Part D option in order to avoid lifetime penalties.
Life Insurance
- If the client is covered by life insurance offered by their employer, have the coverage options or limits changed?
- For those who own permanent life insurance, it’s a good idea to review the policy including how any dividends are being applied and how the policy is performing.
- For those who own a term policy, review the time left on the policy’s term and consider whether the client’s needs have changed.
Disability Insurance
- If the client’s employer provides disability insurance, have there been any changes to this coverage and is it adequate?
- Do the client’s other sources of disability income, such as Social Security and their own personal savings, sufficiently cover their potential needs, or should they consider additional insurance?
Long-Term Care Insurance
- Does the client’s policy have appropriate covered services, benefit amounts, and riders, such as inflation protection?
- Has the client experienced a large increase in their premium? If so, it might make sense to review other options.
This is a comprehensive checklist of the types of issues that advisors should be discussing with their clients when reviewing their life and health insurance policies. These types of policies play a key part in their overall financial plan and in protecting their family’s assets.
---
### [“Hidden” 401 (k) Strategies Used by Some Investors](https://independentadvisorsnw.com/download/1741/?tmstv=1788998123)
**Published:** September 2, 2021
**Author:** MMGI Admin
**Excerpt:** In this guide, you’ll discover why your 401(k) strategy should be “engineered” like a groundhog burrow, because there’s a lot more to it than what you see on the surface.
Most high earners are already leveraging the power of their employer-sponsored 401(k) to save for retirement. They understand the well-publicized advantages: tax deferral, the “free money” provided by the employer match, and the “catch-up” provision after age 50.
**Content:**
In this guide, you’ll discover why your 401(k) strategy should be “engineered” like a groundhog burrow, because there’s a lot more to it than what you see on the surface.
Most high earners are already leveraging the power of their employer-sponsored 401(k) to save for retirement. They understand the well-publicized advantages: tax deferral, the “free money” provided by the employer match, and the “catch-up” provision after age 50.
---
### [Are You Facing Early Retirement?](https://independentadvisorsnw.com/download/1731/?tmstv=1788998123)
**Published:** September 2, 2021
**Author:** MMGI Admin
**Excerpt:** Facing Early Retirement Decision?
You weren’t planning on making retirement decisions so soon. You thought you had years to go before you entered the critical transition period, where the choices you make now set the stage for the next 30 years of your life. But the timer is ticking. You’ve got to make good decisions, fast. Most folks at this crossroads have arrived from three paths. Which one is yours?
**Content:**
Facing Early Retirement Decision?
You weren’t planning on making retirement decisions so soon. You thought you had years to go before you entered the critical transition period, where the choices you make now set the stage for the next 30 years of your life. But the timer is ticking. You’ve got to make good decisions, fast. Most folks at this crossroads have arrived from three paths. Which one is yours?
---
### [What should I do with my old 401(k) or employer plan?](https://independentadvisorsnw.com/download/1703/?tmstv=1788998123)
**Published:** August 16, 2021
**Author:** MMGI Admin
**Excerpt:** A clear guide to your options for 401(k), 403(b), and some 457 plans.
(Including how to avoid a surprise tax bill or IRS penalties that could put you in the crosshairs)
When you leave an employer (whether you’re changing jobs or retiring), your retirement plan doesn’t automatically move for you. You must make a critical decision (or risk having that decision made for you in a way that’s better for the company or costs you money). Your employer plan is one of your most valuable retirement assets and deciding where it should go next is a decision with plenty of nuances, pitfalls, and opportunities.
**Content:**
A clear guide to your options for 401(k), 403(b), and some 457 plans.
(Including how to avoid a surprise tax bill or IRS penalties that could put you in the crosshairs)
When you leave an employer (whether you’re changing jobs or retiring), your retirement plan doesn’t automatically move for you. You must make a critical decision (or risk having that decision made for you in a way that’s better for the company or costs you money). Your employer plan is one of your most valuable retirement assets and deciding where it should go next is a decision with plenty of nuances, pitfalls, and opportunities.
---
## Categories
### [All Posts](https://independentadvisorsnw.com/category/all-posts/)
**Description:** Market analysis videos and commentary by Registered Investment Advisor
---
### [Financial Planning](https://independentadvisorsnw.com/category/financial-planning/)
**Description:** Our blog represents several points of view. One is of an Financial Planner. Read more to learn how our Financial Planners view and act on market events.
---
### [Active Trading](https://independentadvisorsnw.com/category/active-trading/)
**Description:** Our blog represents several points of view. One is of an Active Trader. Read more to learn how our Active Traders view and act on market events.
---
### [Investment Advisor](https://independentadvisorsnw.com/category/investment-advisor/)
**Description:** Our blog represents several points of view. One is of an Investment Advisor. Read more to learn how our Investment Advisors view and act on market events.
---
### [Portfolio & Market Reviews](https://independentadvisorsnw.com/category/monthly-markets-insight-video/)
**Description:** Watch our Monthly Market(s) insights videos. There are several points of view represented, such as Investment Advisor, Active Trader, and Financial Planner.
---
### [News and Announcements](https://independentadvisorsnw.com/category/news/)
**Description:** Read more about Independent Investment Advisers latest company news and announcements
---
### [Featured Article](https://independentadvisorsnw.com/category/featured-article/)
---